

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Tattoo Ink Market to Reach USD 274.9M by 2032 at 5.36% CAGR

Tattoo Ink Market 2026: Strategic Imperatives from PW Consulting’s Market Study
Executive snapshot
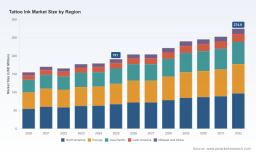
By 2025 the global tattoo ink market had established itself as a resilient niche within specialty pigments and personal-care adjacencies, with the market size reaching approximately USD 191.0 Million (base year 2025). Our forecast models project a steady compound annual growth rate (CAGR) of 5.36% through the 2026–2032 horizon, with the market approaching roughly USD 275 Million by 2032. Behind these headline numbers lies a market shaped by regulatory scrutiny, manufacturing quality differentiation, evolving consumer preferences (from traditional body art to cosmetic and medical applications), and an increasingly visible premiumization trend among professional artists and clinics.
Tattoo Ink Market
Why this study matters for 2026 decision-makers
2026 will be a pivotal year for executives, product leaders, and investors in the tattoo ink ecosystem. The combination of sustained demand, amplified regulatory oversight, and concentrated competitive dynamics means that small executional advantages will translate into outsized commercial outcomes. PW Consulting’s Tattoo Ink Market study is designed as a decision-support tool for that environment: it translates raw market trajectories into actionable strategic options, prioritizes risk mitigations tied to regulation and contamination, and models revenue and margin sensitivity across realistic scenarios — without leaking the proprietary segmentation tables that form the core of our value proposition.
Tattoo Ink Market
Market dynamics: what is driving growth and reshaping choices
- End-market diversification: Traditional body art remains the largest visible demand engine, but cosmetic permanent makeup and medical tattooing (e.g., areola repigmentation, scar masking) are important growth vectors that alter product specifications, regulatory exposure, and acceptable pricing.
- Product and formulation differentiation: Manufacturers are competing on sterilization standards, color stability, healed appearance, and claims such as vegan/cruelty-free or organic. These attributes now carry commercial premiums and influence salon/clinic purchasing decisions.
- Regulatory and safety pressure: Recent U.S. regulatory activity — including October 2024 FDA guidance on contamination prevention and a May 2025 FDA public health advisory regarding contaminated inks — has elevated compliance costs and reputational risk for producers and distributors. Complementary clinical findings (e.g., a 2025 study on systemic retention of soluble ink components) have nuanced the debate on long-term safety and are shaping labelling and testing expectations globally.
- Supply-chain control and traceability: Direct-from-manufacturer sales models, batch-level sterility certification and tighter supplier audits are emerging as competitive needs, not optional virtues. Companies that can guarantee consistent healed results and documented safety enjoy pricing leverage and broader access to professional channels.
Competitive landscape — who matters and how they compete
The market displays a moderate level of concentration. The top three suppliers collectively represent a meaningful share of professional demand, while the top five widen that advantage further — a structure that favors brands with strong manufacturing credibility and direct ties to artist communities. Key strategic archetypes in the market include:
Tattoo Ink Market
- Manufacturing-first brands: Firms that invest in controlled-production processes, batch sterility and rigorous QA to command premium positioning among professional artists and clinics. These players emphasize predictable handling, color clarity and healed results.
- Artist-first challenger brands: Competitors building loyalty through co-development with prominent tattoo artists, community engagement, and channel-specific services (training, sample programmes, and localized logistics).
- Quality-led niche specialists: Smaller players focused on specific formulation categories (e.g., vegan or organic pigments, UV/white inks, or metallics) who monetize uniqueness and serve advanced use-cases in cosmetic and medical tattooing.
Representative players include firms with strong U.S.-based manufacturing reputations and focused brand identities. Their common strategic moves — sterilization claims, vegan formulations, and direct distribution — define current best practice and set the bar for new entrants.
Report contents — what the PW Consulting study delivers
The study is built for executives who need both the strategic horizon and the tactical playbook. Core elements include:
- Market sizing and robust forecast models (historical 2020–2025 context and 2026–2032 scenarios), with sensitivity analysis around pricing, product-mix, and regulatory shocks.
- Granular product and application frameworks that map R&D priorities to commercial outcomes (note: detailed segmental tables and regional breakdowns are reserved in the full report to preserve competitive advantage and guide primary-market decisions).
- Regulatory risk assessment and compliance roadmaps tied to recent FDA guidance, health advisories, and clinical literature — including operational checklists for contamination prevention and label-claim substantiation.
- Competitive benchmarking: manufacturing practices, go-to-market models, channel footprints, and innovation pipelines for leading players.
- Go-to-market playbooks for B2B and D2C channels, pricing strategy templates, and a prioritized M&A target list informed by capability gaps and consolidation opportunities.
- Implementation tools: three 12-month tactical roadmaps (Regulatory-First, Premiumization, and Channel Acceleration) with milestone KPIs and cost-estimate ranges.
Strategic imperatives for 2026 (what we advise clients to act on now)
PW Consulting recommends a three-track approach for leaders seeking to convert 2026 market conditions into durable advantage.
- Track 1 — Certificate-first quality governance: Adopt a documented contamination-prevention program aligned with recent FDA guidance, including periodic third-party sterility testing, batch-level traceability, and proactive recall protocols. The near-term cost of tighter QA is offset by faster market access in regulated channels and reduced recall-related reputational losses.
- Track 2 — Portfolio rationalization and premium route-to-market: Prioritize formulations that deliver reliable healed results and justify price premiums (e.g., clinically validated pigments for cosmetic/medical applications). Consolidate SKUs that underperform on margin and redistribute R&D spend toward high-return formulation improvements and claim substantiation.
- Track 3 — Channel and community enablement: Fortify direct relationships with artists and clinics through education, refill programs, and guarantee policies. Build hybrid distribution networks that combine selective wholesale partnerships with digital direct-to-artist offerings to optimize margins while maintaining market access.
Risk management and compliance playbook
Regulatory developments in 2024–2025 shifted compliance from a table-stakes item to a strategic differentiator. To operationalize risk reduction:
- Implement end-to-end traceability from pigment sourcing to finished product lot — including supplier audits and raw-material certificates of analysis.
- Design labeling and customer communication frameworks that reflect current clinical evidence and real-world safety data; avoid overstated permanence claims that invite regulatory scrutiny.
- Invest in transparent customer-facing documentation: batch testing results, sterilization certificates and recommended aftercare protocols reduce legal exposure and accelerate adoption by clinics and medical facilities.
M&A and capital allocation lens
With the market moderately concentrated, strategic acquisitions remain a pragmatic route to accelerate capability building. Targets should be assessed against three capability gaps: manufacturing sterility at scale, clinically validated pigment portfolios, and established distribution/artist community networks. Private-equity buyers and strategic acquirers will find differentiated valuations for assets that demonstrate documented quality systems and proven success in cosmetic/medical channels.
Measuring success in 2026
We recommend monitoring a compact set of KPIs that connect operational inputs to market outcomes:
- Percentage of revenue from certified-sterile or clinically-validated SKUs
- Artist/clinic retention and repurchase rates (by cohort)
- Time-to-market for new formulations (R&D cycle time)
- Cost per batch-quality test and recall incidence (target: zero serious contamination events)
- Gross margin expansion attributable to premium SKUs and direct channels
Final note — why a “trailer” reads as value
This introduction surfaces the strategic contours and actionable imperatives that PW Consulting’s Tattoo Ink Market study provides. It deliberately omits the granular regional and application-level split tables — those are the proprietary intelligence that executives use to size investments, prioritize product launches, and identify acquisition targets. If your 2026 plan depends on precise market share by channel, regional growth pockets, product-type revenue trajectories, or scenario-specific sensitivity outputs, the full report delivers that calibrated data along with the operational playbooks you need to move decisively.
Next steps
For a tailored briefing, scenario walkthrough, or to acquire the full dataset and implementation toolkits referenced here, PW Consulting is prepared to arrange a confidential executive session. In an environment where regulatory scrutiny, product quality and community trust determine winners, having the right intelligence — and the playbook to act — is the competitive edge for 2026.
For detailed analysis of this topic, please visit the official page: Tattoo Ink Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com