

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Automotive Glow Plugs Market Poised for 4.17% CAGR Through 2032

Automotive Glow Plugs Market — Strategic Preview for 2026 Decision-Makers
Executive snapshot
The global automotive glow plugs market is on a steady growth trajectory as diesel engine platforms evolve to meet ever-tightening emissions standards and OEMs seek cleaner cold-start performance. PW Consulting’s market model (base year 2025) shows the market recovering and expanding from the pandemic-era volatility, with global revenues rising from an observed level in 2020 to approximately USD 377.4 Million in 2025, and a forecasted climb to just over USD 504.7 Million by 2032. Our forecast period (2026–2032) embeds a compound annual growth rate (CAGR) of 4.17%, reflecting a mix of technological substitution, regulatory-driven demand for enhanced combustion control, and sustained aftermarket replacement cycles.
Automotive Glow Plugs Market
Why this briefing matters for 2026 strategy
For executives making capital allocation, product road‑map, or M&A decisions in 2026, the glow plug market presents a nuanced set of opportunities and risks. The market sits at the intersection of traditional internal‑combustion powertrain dynamics, rapid regulatory lift (notably Euro 7 and similar jurisdictional moves), and selective innovation—such as ceramic heating elements and integrated sensing—that materially change product value propositions. This preview synthesizes the market dynamics that should influence near‑term choices without revealing the granular segmentation data contained in the full PW Consulting report.
Automotive Glow Plugs Market
Market trajectory and what the numbers imply
- Historical resilience: After a dip during the early 2020s, aggregate market revenues rebounded and stabilized by 2024–2025. The 2025 base figure (~USD 377.4M) represents recovery plus incremental gains from both OEM upgrades and a healthier aftermarket replacement environment.
- Predictable growth, selective upside: Our 2026–2032 projection to approximately USD 504.7M by 2032 (CAGR 4.17%) indicates dependable long‑cycle demand rather than explosive expansion. The implication for investors and suppliers is that steady, margin‑focused plays—product quality, cost discipline, and selective technology differentiation—will often outperform high‑risk capacity expansion.
- Concentration matters: Market concentration is meaningful. The top three players account for a majority share of the market, and the top five control roughly three‑quarters of demand. This structure creates advantages for incumbent technologists (scale, OE relationships) and challenges mid-tier suppliers seeking price‑competitive access to global channels.
Key market drivers and headwinds for 2026 decisions
- Regulatory tightening as a demand amplifier. Euro 7 (effective 2026) and analogous moves increase technical requirements for combustion control during cold starts and low‑load ops. For diesel OEMs and tier‑1 suppliers, this becomes a specification issue: glow plugs must contribute to sustained low‑emission combustion cycles. The immediate commercial effect: replacement of legacy designs and elevated OEM qualification thresholds.
- Technology bifurcation — ceramic vs. metal vs. sensor‑integrated designs. Ceramic elements deliver faster heat‑up times and improved high‑temperature durability; sensor‑integrated glow plugs enable closed‑loop cold‑start optimization and ancillary NOx-reduction strategies. Product road maps should prioritize modular platforms that can accept incremental sensing or alternative element materials to meet divergent OEM specifications without full redesign.
- Aftermarket endurance vs. OEM innovation. While OEMs demand high‑performance, often higher‑cost solutions, the aftermarket remains volume-rich and margin‑sensitive. Successful suppliers will maintain dual‑channel strategies: defend OE business through rigorous validation and tap aftermarket revenue with cost‑effective, coverage‑focused portfolios.
- Consolidation and capability transactions. Recent deals reshuffle capabilities and distribution reach. Buyers and sellers should evaluate acquisitions for their ability to deliver scale in validated part coverage, proprietary heating or sensing IP, and faster time‑to‑market for emissions‑compliant solutions.
- Electrification’s asymmetric impact. BEV penetration reduces future absolute demand for glow plugs, but the near‑ and medium‑term window (particularly in regions with heavy diesel presence in commercial fleets) sustains sizeable demand. Firms should use scenario analyses to balance near‑term revenue harvesting with longer‑term product diversification.
Competitive landscape — what differentiates winners
The competitive map is dominated by a handful of established component OEMs and a broad base of regional producers. The leaders combine OE heritage, deep vehicle application coverage, and product innovation; smaller suppliers compete on nimbleness, cost, and aftermarket specialization. Key strategic differentiators we see influencing competitive outcomes in 2026:
Automotive Glow Plugs Market
- Proven OE validation and factory testing regimes — companies with long‑standing OE relationships capture higher‑value specifications and are insulated from price‑only competition.
- Proprietary heating and sensing technologies — suppliers offering faster warm‑up, greater thermal endurance, or integrated pressure/combustion sensing command premium positioning in emissions‑constrained programs.
- Global aftermarket coverage and fill‑rate capabilities — ensuring replacement part availability for vast installed bases is decisive for sustaining aftermarket revenue.
- Manufacturing footprint flexibility — strategic capacity in multiple geographies mitigates supply chain shocks and local content requirements.
Company archetypes and implications for partners and buyers
- Large OE incumbents with deep validation (example archetype): Companies that supply factory‑tested sheathed and ceramic designs excel at commanding OE specifications and extended warranties. For suppliers, partnering with these incumbents requires meeting rigorous quality processes but unlocks stable large‑volume contracts; for OEM procurement, these incumbents reduce qualification risk.
- Technology leaders focusing on next‑gen solutions: Firms embedding sensors or advanced ceramics enable system‑level benefits (faster starts, NOx reduction). These providers are attractive targets for engine management system integrators or for OEMs seeking integrated combustion‑control solutions.
- Regional and cost‑focused aftermarket specialists: These players maintain profitability through part coverage, inventory velocity, and localized logistics. They are prime partners for aftermarket distributors and can be acquisition targets for larger players seeking fill‑rate uplift.
Recent industry movements and operational consequences
- Notable capability transfers and product portfolio refreshes have taken place in the last 18 months. Such moves accelerate consolidated part coverage and alter competitive dynamics in both OE and aftermarket channels; they also materially affect supplier selection conversations during RFQs.
- Product updates that expand premium aftermarket ranges or add sensors into the product stack are compressing technology gaps between OE and aftermarket offerings. Buyers should anticipate shorter windows for exclusive OE advantages and plan dual sourcing strategies.
What the PW Consulting report delivers (practical, actionable contents)
PW Consulting’s full study provides the decision support and operational detail teams need to convert these high‑level insights into executable plans. Highlights of the report’s actionable elements include:
- Market size and validated growth profiles (historical and forecast) at the global level, with scenario pathways tied to regulatory timelines and powertrain trends.
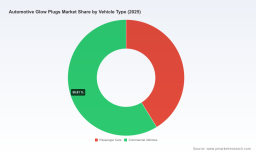
- Segment‑level demand drivers and resilience assessments across vehicle and channel archetypes (note: detailed segment tables and regional splits are available in the full report).
- Competitive benchmarking with technology positioning, OE coverage, part‑number breadth metrics, and supplier concentration analytics to inform sourcing and partnership strategies.
- Supply chain risk maps—raw material exposure, critical manufacturing nodes, and mitigation playbooks for inventory and dual‑sourcing.
- M&A and partnership screening criteria with accretion/dilution sensitivity models tailored to common deal structures in the component space.
- Go‑to‑market playbooks for OEM and aftermarket channels, including pricing architecture, warranty alignment, and product differentiation checklists.
Practical strategic actions for 2026
- For OEM procurement teams: prioritize suppliers with validated ceramic or sensor‑integrated platforms that can meet new emissions and cold‑start testing at scale, and build contingency second sources for critical vehicle programs.
- For component manufacturers: invest selectively in modular heating/sensing platforms and broaden part coverage strategically through bolt‑on acquisitions rather than greenfield expansion to preserve margins.
- For aftermarket distributors: double down on coverage, logistics, and fitment accuracy. Use data to prioritize SKUs that serve the largest installed bases while partnering with premium‑technology suppliers to capture a higher margin tier.
- For private equity and strategics: prioritize targets that (a) improve market concentration in adjacent geographies, (b) add proprietary heating or sensing IP, or (c) deliver immediate aftermarket fill‑rate synergies.
Why PW Consulting’s full report is a necessary next step
This preview surfaces the strategic levers and risks that will matter in 2026, but effective execution requires the granular inputs—application coverage matrices, regional demand curves, segmented price and margin benchmarks, and supplier part‑level concentration data—that we intentionally withhold here to preserve the commercial value of the full study. PW Consulting’s comprehensive report contains those datasets, validated supply‑chain maps, and executable templates that procurement, product, and corporate development teams can use immediately to model decisions and structure contracts.
Concluding guidance
The glow plug market in 2026 is not a winner‑takes‑all arena, but it is one in which scale, validated OE craftsmanship, and selective technological differentiation drive outsize returns. Firms that combine rigorous regulatory preparedness, modular product architecture, and disciplined aftermarket strategies will capture the majority of available upside as the market grows at an expected mid‑single‑digit CAGR through 2032. For organisations facing 2026 planning cycles, the right combination of supplier selection, targeted investment, and M&A can convert a predictable market into a durable competitive position.
To translate these insights into executable plans for 2026, request PW Consulting’s full Automotive Glow Plugs Market report for the detailed datasets, segmentation tables, and tactical toolkits that underpin this strategic preview.
For detailed analysis of this topic, please visit the official page: Automotive Glow Plugs Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com