

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Agricultural Inoculants Market Poised for 10.41% CAGR Through 2032

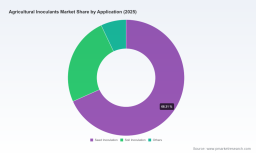
Agricultural Inoculants Market: Strategic Outlook for 2026 Decision‑Makers
As PW Consulting’s senior strategy advisor and lead industry analyst, I present a focused executive preview of our Agricultural Inoculants Market research—the intelligence you need to inform investment, product, and commercial decisions in 2026. The market is no longer niche: our base‑year analysis (2025) shows the sector expanding rapidly from USD 0.85 Billion in 2020 to USD 1.42 Billion in 2025, with a projected trajectory to roughly USD 2.84 Billion by 2032 at a compound annual growth rate (CAGR) of 10.41%. This preview explains why that growth matters, how competitive dynamics are shifting, and what leaders must prioritize next. (Note: we intentionally withhold granular segment allocations here to drive executives to the full report for the supporting datasets and models.)
Agricultural Inoculants Market
Why this research is strategically valuable for 2026
- Capital allocation clarity: Quantified growth and scenario modelling let CFOs and corporate development teams size investment tranches for R&D, manufacturing scale‑up, or acquisitions with lower execution risk.
- Go‑to‑market playbooks: Sales and commercial teams get priority tactical options—channel mixes, seed‑treatment partnerships, and farmer adoption incentives—that shorten time to revenue.
- Regulatory and compliance roadmap: Legal and policy teams gain an operational view of permissioned organisms, registrational timelines, and market access barriers that materially affect product cadence.
- Risk‑adjusted product strategy: Product leaders can prioritize microbe platforms (biocontrols, growth promoters, nitrogen fixation, mycorrhizae) against market returns and regulatory risk.
What the full report delivers (practical, actionable contents)
- Market sizing and 7‑year forecast models built from farmer economics, product adoption curves, and commercial roll‑outs (base year 2025, forecast 2026–2032).
- Scenario stress tests (policy shock, raw‑material constraints, rapid adoption, slow commercial conversion) that convert uncertainty into decision triggers.
- Segment structure and demand drivers by product archetype, application pathway, and route to market—presented with underlying assumptions and sensitivity tables. (Note: specific segment allocations are reserved for the full report.)
- Competitive landscape intelligence with strategic profiles, capability maps, and product positioning for the sector’s leading companies and scaling challengers.
- Commercial playbooks—pricing frameworks, bundling options with seed/chemical portfolios, distribution and retailer incentives, and farmer trial roadmaps that accelerate adoption.
- Regulatory matrix covering major jurisdictions, registration pathways, and restrictions that influence product design and market entry sequencing.
- Supply‑chain and manufacturing feasibility assessments, including active ingredient sourcing, formulation stability, and cold‑chain implications for scale.
- M&A and partnership playbook: evaluating targets, integration risks, and a checklist for technology, regulatory, and channel synergies.
- Primary research appendices: farm trial data, grower willingness‑to‑pay experiments, and expert interview transcripts underpinning our conclusions.
Dynamics powering near‑term growth
Three structural forces underpin the industry’s 10.41% CAGR and the forecasted doubling over the coming decade.
Agricultural Inoculants Market
- Policy and public funding acceleration: Governments and public agencies are directing significant resources toward soil health and climate‑smart agriculture programs, expanding the addressable market for microbial approaches and enabling subsidized piloting and scaled demonstrations.
- Commercial readiness of advanced microbial platforms: Gene‑edited and next‑generation inoculants are moving from field trials to commercial launches—evidence that science is translating into farm‑scale ROI. Recent commercial introductions of nitrogen‑fixing products for key row crops underscore a new phase of adoption.
- Demand shifts among growers and supply chains: Growing acreage under organic, regenerative, and low‑input programs (material annual increases in certified land in primary markets) raises demand for permitted biological inputs. At the same time, input suppliers are integrating microbial solutions with seed and crop protection portfolios to offer differentiated bundles.
Counterbalancing these tailwinds are regulatory frictions and market readiness barriers. For example, existing regulations in certain jurisdictions limit marketing claims or restrict the range of organisms that can be classified as biofertilizers. Those constraints materially affect product design and go‑to‑market sequencing for international roll‑outs.
Agricultural Inoculants Market
Competitive landscape: who matters and why
The market exhibits a middle level of concentration (indicative CR3 roughly in the mid‑30s and CR5 in the mid‑40s), signaling meaningful room for both incumbent expansion and specialist entrants. Three strategic archetypes dominate the field:
- Integrated crop‑protection and seed incumbents (examples: BASF SE, Bayer AG, Corteva, Syngenta Group): these players leverage existing seed treatment channels, regulatory experience, and farmer relationships to bundle inoculants with legacy products—accelerating adoption where commercial alignment exists.
- Pure‑play biological innovators (examples: Pivot Bio, Novonesis, Valent BioSciences, XiteBio): their advantage is platform science and rapid iteration; successful commercialization of disruptive platforms—especially for nitrogen fixation or root symbionts—can re‑write crop input economics.
- Regional specialists and formulators (examples: Lallemand, Premier Tech, Bioceres, Verdesian, Groundwork, Koppert): these firms focus on formulation stability, local regulatory pathways, and niche crop applications—often serving as acquisition targets or regional partners for larger groups.
Notable recent activity signals escalating commercial competition: gene‑edited nitrogen‑fixing products have moved into commercial use for major crops, validating the technical pathway from lab to field and creating new benchmarks for efficacy and farmer ROI. Expect incumbents to respond with both internal development and M&A to shore up capabilities.
Strategic implications for executives in 2026
- Prioritize product architectures that align with regulation and claims: Design platforms that meet permissibility in critical markets—this lowers the barrier to entry and speeds time to revenue.
- Build commercial proofs that matter to growers: Short, high‑quality on‑farm trials that demonstrate net margin improvement drive adoption far faster than lab efficacy data alone.
- Choose channels selectively: Seed‑treatment partnerships and established distribution networks reduce friction; direct‑to‑farmer digital models work where traceability and subscription economics are viable.
- Mitigate supply risk early: Secure active ingredient supply and plan for formulation scale; biologicals require different cold‑chain, QC, and shelf‑life considerations than chemicals.
- Use M&A as capability accelerant, not shortcut: Targeted acquisitions should fill gaps in manufacturing, registration expertise, or proprietary microbe platforms—validated through rigorous technical and regulatory due diligence.
How to use this research in your 90/180/365‑day planning
- 0–90 days: Conduct a regulatory gap analysis for your product pipeline versus key markets; initiate high‑value farmer demonstrations; evaluate partner lists in seed and distribution.
- 90–180 days: Run pricing and bundling pilots; finalize formulation scale plans; sign first‑round commercial partnerships or supply agreements that de‑risk initial scale.
- 180–365 days: Execute channel roll‑out across prioritized territories; implement a data capture framework to quantify ROI for growers; pursue high‑value M&A or licensing to close capability gaps.
Conclusion — why PW Consulting’s full dataset matters now
The Agricultural Inoculants Market is moving from scientific promise to commercial reality. Our headline metrics—USD 0.85 Billion in 2020 → USD 1.42 Billion in 2025, and an expected rise to about USD 2.84 Billion by 2032 at a 10.41% CAGR—capture the growth story. But executive decisions in 2026 hinge on granular, defensible specifics: regional demand shapes, product‑type economics, application pathways, channel unit economics, and regulatory timelines. This preview intentionally demonstrates the analytical depth you can expect while withholding the granular segment allocations and financial tables that operational teams require to execute with confidence.
For access to the full market model, detailed segment splits, company benchmarking matrices, and our recommended 12‑month action plan template, please consult the complete PW Consulting Agricultural Inoculants Market report. That is where the data, scenario models, and playbooks needed to make high‑stakes 2026 decisions are provided in full.
For detailed analysis of this topic, please visit the official page: Agricultural Inoculants Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com