

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Niacin Market Set for 6.65% CAGR in 2026-2032

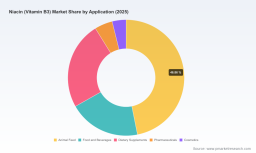
Niacin (Vitamin B3) Market — Strategic Briefing for 2026 Decisions
This briefing distils the strategic implications of PW Consulting’s latest Niacin (Vitamin B3) Market research (base year 2025) for corporate leaders planning investments, sourcing, and product strategies in 2026. The market has evolved from a mid-single-digit commercial specialty to a strategically significant ingredient across animal feed, human nutrition, pharmaceuticals, cosmetics and personal care. Our analysis blends a multi-year historical view (2020–2025) with a seven-year forecast horizon (2026–2032), capturing both cyclical risks and structural growth drivers that will shape high-consequence choices this year.
Niacin (Vitamin B3) Market
High-level market trajectory: what the numbers tell you
- Historical momentum: The Niacin market expanded materially over 2020–2025, reflecting recovery in downstream demand, expanded feed and supplement usage, and incremental penetration in personal-care formulations.
- Near-to-medium term outlook: PW Consulting’s forecast projects a compound annual growth rate (CAGR) of 6.65% for 2026–2032. Under the baseline scenario, the total market moves from its 2025 base into substantially larger absolute scale by the end of the forecast window, underpinning the economics for new capacity, product premiumization, and vertical integration.
- Market structure signal: Concentration metrics indicate a concentrated supplier base — the top three firms control a dominant share of volume, and the top five capture the overwhelming majority of supply. This structural feature amplifies the impact of strategic moves by incumbents and creates both entry barriers and consolidation opportunities for challengers.
Why this report matters to decision-makers in 2026
- Investment calibration: With clear historical series and scenario-modeled forecasts covering 2026–2032, executives can align CAPEX timelines (e.g., new synthesis lines or bio-based capacity) to demand inflection points rather than guesswork.
- Sourcing and procurement strategy: The research identifies where margin pressure is most likely to emerge because of feedstock volatility and concentration — essential for designing hedging strategies, dual-sourcing plans, and long-term supplier agreements.
- Product and route prioritization: The report benchmarks synthetic versus bio-based production economics and maps where premiumization (pharma-grade, high-purity, certified sustainable) can support margin expansion in 2026 and beyond.
- M&A and partnership signaling: Given the market’s concentration and a wave of strategic repositioning among incumbents, the dossier provides decision-support for bolt-on targets, JV structures, and production-sharing opportunities targeted at immediate 2026 integration windows.
- Regulatory and compliance planning: The dossier flags specific regulatory regimes and certification requirements that will materially affect time-to-market for pharmaceutical and nutraceutical grades — critical for 2026 product launches and contract timelines.
Key dynamics shaping the market landscape
- Feedstock and input cost volatility — The primary upstream precursor for niacin derivatives is sensitive to petrochemical cycles. Fluctuations in 3-cyanopyridine pricing and periodic supply tightness (with geopolitical exposure concentrated in certain production hubs) inject episodic cost pressure that cascades through pricing and margin negotiations.
- Regulatory and documentation friction — Pharmaceutical-grade product flows require jurisdictional approvals and bioequivalence or GMP documentation at multiple production nodes, which extends lead times and raises inventory carry requirements for regulated customers.
- Sustainability and certification as commercial differentiators — ISO, food-safety, religious certifications, and growing demand for bio-based feedstocks are now table stakes for many buyers. Companies that can demonstrate third-party-verified sustainability and traceability access premium channels in cosmetics and health-oriented products.
- Supply-chain choreography — Inventory cycles are lengthening in regulated segments as manufacturers and buyers manage documentation and compliance cycles; this alters the classical cadence of supply and requires precise inventory optimization to avoid stockouts or costly excesses.
- Concentration and competitive reaction — High market share among a few firms means that plant outages, strategic pricing moves, or divestitures by incumbents have outsized effects on global availability and price signaling.
Competitive landscape: positioning, moves, and implications
The Niacin market’s competitive map is a mix of global chemical majors, specialty CDMOs, dedicated vitamin producers, and regional biological manufacturers. PW Consulting’s competitive profiles focus on how each firm’s capabilities translate into 2026 strategic options:
Niacin (Vitamin B3) Market
- Lonza Group AG (Basel, Switzerland) — A leading CDMO and specialty ingredients provider with strong positioning in pharmaceutical- and cosmetic-grade niacin derivatives. Lonza’s integrated services model allows customers to bundle development and supply, shortening time-to-market for high-value formulations.
- dsm-firmenich (Maastricht, Netherlands) — Historically strong in nutritional and personal-care solutions. Recent portfolio reshaping (including a divestiture agreement for certain nutrition assets) signals potential redistribution of capacity and shift toward core strategic priorities; this creates windows for competitors and buyers to renegotiate terms or source alternatives.
- BASF SE (Ludwigshafen, Germany) — A major chemical-synthesis producer whose scale supports cost-competitive supply into animal feed and industrial applications. BASF’s capabilities are a structural price anchor for bulk niacin supply.
- Jubilant Ingrevia Limited (Noida, India) — A high-volume producer that has moved rapidly into bio-based product lines and active presence at relevant industry shows. Its Bio-Niacinamide launch underscores a strategic push to capture premium segments in personal care through sustainable feedstocks.
- Aurorium (Indianapolis, United States) — Focused on high-purity, pharmaceutical-grade vitamin B3; attractive to customers with stringent quality and regulatory needs.
- Zhejiang NHU Co., Ltd. (China) — A global leader in production volume with deep integration across domestic and export channels. Its scale makes it a pivotal supplier in global balancing of supply and demand.
- Merck KGaA (Darmstadt, Germany) — Positioned on the pharma-grade, life-science side, with technical depth relevant to high-regulatory-burden customers.
- Bactolac Pharmaceutical Inc. (Hauppauge, NY) and Shandong Kunda Biotechnology (Linyi, China) — Represent contract manufacturing and biological production niches that are attractive for customers seeking formulation flexibility and alternative production routes.
Collectively, these players create a dynamic mix of scale, technical differentiation, and route-to-market choices. The market’s CR3 and CR5 concentration levels materially increase the value of strategic supplier relationships and partnership-first go-to-market models in 2026.
Niacin (Vitamin B3) Market
Recent strategic developments worth watching
- Jubilant Ingrevia’s Bio-Niacinamide launch (Dec 2025) and focused showcase activities at regional industry events (Oct 2025) demonstrate an accelerated commercialization path for bio-based intermediates in personal-care formulations.
- dsm-firmenich’s divestiture of selected nutrition assets (announced early 2026) highlights industry reshuffling that will reallocate production capacity and open bidding and partnership opportunities for vertically aligned suppliers and private-equity-backed consolidators.
- Ongoing raw-material price swings and supply-chain constraints continue to drive short-term contract renegotiations and prompt buyer interest in long-term offtake agreements tied to sustainability or dual-sourcing clauses.
What PW Consulting’s report delivers — practical, actionable content
The full research package is engineered as an executive decision-support tool rather than a descriptive summary. Key pragmatic deliverables include:
- Time-series market model (2020–2025 actuals; 2026–2032 forecast) with scenario toggles for high/low feedstock prices and demand shocks.
- Supply-risk heat maps and supplier scorecards that evaluate capacity, certifications, geographic concentration, and alternative-route readiness.
- Price-sensitivity and margin-impact models to quantify how feedstock volatility and certification premiums affect profitability under alternative contracting structures.
- Regulatory dossier checklist and market-entry timing guide for pharmaceutical- and nutraceutical-grade products across major jurisdictions.
- Deal and M&A playbook outlining valuation heuristics and go/no-go triggers calibrated to the market’s concentration and forecasted growth.
- Commercial roadmaps for product premiumization: go-to-market sequencing for bio-based and certified products, supported by trade-channel targeting and promotional positioning.
- Downloadable datasets and scenario workbooks to integrate into corporate planning systems — enabling CFOs and strategy teams to stress-test assumptions under 2026 planning cycles.
Concise operational playbook for 2026
- Secure feedstock optionality: lock partial hedges and establish secondary suppliers in geographies less exposed to single-node disruptions.
- Prioritize certification and traceability investments where they unlock premium channels — cosmetic and pharma customers are increasingly willing to pay for verified sustainability and quality credentials.
- Pursue pragmatic capacity plays: consider brownfield expansions or tolling arrangements over greenfield builds to align with the forecasted CAGR while preserving capital flexibility.
- Explore strategic alliances with contract manufacturers and CDMOs to accelerate market entry into high-purity segments without bearing full CAPEX risk.
- Add scenario-based covenants to customer contracts to share input-cost risk transparently, reducing margin erosion during raw-material spikes.
Next steps — how to use this briefing
Use this note as a framework to prioritize topics for your 2026 strategic planning cycle: supply risk mitigation, selective capacity plays, product premiumization, and M&A screening. PW Consulting’s full report supplies the granular segment-level forecasting, regional and application splits, supplier-level analytics, and downloadable modeling assets that translate insights into executable plans — including the proprietary datasets and supplier scorecards referenced here. For teams preparing budgets, negotiations, or investment memoranda in 2026, those detailed inputs are the difference between directional conviction and executable certainty.
To unlock the full dataset, supplier scorecards, country- and application-level forecasts, and the scenario workbooks that underpin these recommendations, please consult the full Niacin (Vitamin B3) Market report on PW Consulting’s portal.
For detailed analysis of this topic, please visit the official page: Niacin (Vitamin B3) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com