

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: SCBA Market Eyes USD 2,508M by 2032 with 6.5% CAGR

SCBA Market 2026: Strategic Preview for Corporate Decision-Makers
Executive snapshot
As organizations re-evaluate safety, continuity, and resilience investments in 2026, the Self Contained Breathing Apparatus (SCBA) market presents both a steady growth story and a shifting competitive and regulatory landscape. Our base-year analysis (2025) positions the global market at approximately USD 1,640 Million (USD Million basis), rising from roughly USD 1,270.5 Million in 2020 and projected to reach about USD 2,508.0 Million by 2032. This trajectory implies a compound annual growth rate (CAGR) of approximately 6.5% over the 2026–2032 forecast period.
Self Contained Breathing Apparatus (SCBA) Market
This preview highlights why the 2026 planning cycle is pivotal: regulatory updates, certification refreshes, and supplier product cycles converge to create near-term procurement windows, upgrade imperatives, and service-contract opportunities. PW Consulting’s full report provides the detailed, actionable intelligence required to convert those inflection points into defensible capital, procurement, and product strategies.
Self Contained Breathing Apparatus (SCBA) Market
Why 2026 matters — the strategic context
- Regulation-driven refresh: The NFPA 1970 (2025 Edition) consolidation — folding prior standards into a harmonized set of requirements — introduces mandatory facepiece performance upgrades (notably radiant heat and elevated temperature resistance) effective January 1, 2026. This has immediate implications for buyer specifications, capital replacement plans, and aftermarket demand for facepiece retrofits and training.
- Certification clarity matters: NIOSH’s updated Certified Equipment List (data current as of June 1, 2026) is now the single source for authorized SCBA models in many regulated jurisdictions. Buyers that can align procurement timelines with certification cycles will reduce compliance risk and simplify approval processes.
- Market momentum: After recovering from cyclical pressures observed earlier in the decade, the SCBA market demonstrates durable demand—expanding from ~USD 1,270.5 Million in 2020 to ~USD 1,640 Million in 2025, and projected to accelerate toward ~USD 2,508.0 Million by 2032. That growth supports investment in product innovation, service ecosystems, and aftermarket services while maintaining opportunistic M&A interest.
Competitive dynamics — what the field looks like in 2026
The SCBA competitive landscape is characterized by several global specialists and a broad long tail of niche suppliers. The market concentration remains moderate: the top three vendors account for less than one quarter of total market revenue, and the top five for roughly a third—indicating meaningful room for regional players, private-label offerings, and service-oriented differentiation.
Self Contained Breathing Apparatus (SCBA) Market
Among notable incumbents, several large-established suppliers are actively aligning product lines with the new NFPA requirements and certification regimes:
- 3M Scott Fire & Safety (Monroe, NC, USA) — Continues to refresh its portfolio to meet the latest safety standards and has recently secured NFPA 1970 (2025 Edition) certification for leading SCBA platforms, signaling readiness for major institutional procurement.
- MSA Safety (Pittsburgh, PA, USA) — Rapidly positioning new-generation SCBA for frontline fire and industrial users; key models received NFPA 1970 (2025 Edition) recognition in late 2025.
- Dräger (Lübeck, Germany) — A technology-heavy competitor that has secured certification for flagship systems, reinforcing its competitive standing in high-spec applications.
- Biomarine Inc. (Exton, PA, USA) and Interspiro (Täby, Sweden) — Important players in selected verticals and geographies, leveraging specialized product attributes and service propositions.
Recent certification events (MSA and Dräger in November 2025; 3M Scott in March 2026) create a two-fold market effect: (1) immediate procurement clarity for compliant models and (2) a compression of the replacement cycle for non-compliant inventory. For organizations that must maintain NFPA compliance, alignment with certified product availability will be a procurement priority in 2026.
Key demand drivers and disruptive pressures
- Regulatory harmonization and compliance spend: Consolidated standards reduce ambiguity but increase the technical bar for facepieces and materials. Expect elevated capital spend in 2026 from customers needing to accelerate upgrades to meet new heat-resistance requirements.
- Aftermarket and services expansion: With many operators deferring full-system replacements, demand for retrofits, certification support, calibrated maintenance programs, and training will grow—creating higher-margin service monetization paths for suppliers.
- Technology differentiation: Innovations in air management, lighter composite cylinders, integrated electronics (e.g., HUDs, health monitoring), and modularity will be the primary product-level battlegrounds. Vendors that can demonstrate validated durability under the new NFPA criteria will capture value.
- Procurement cycles and capital planning: Municipal fire services, industrial fleets, and oil & gas operators face different budget rhythms. Smart suppliers will offer flexible financing, managed services, or shared-risk models to smooth procurement and accelerate adoption.
What the PW Consulting report delivers — practical, decision-grade content
PW Consulting’s full SCBA Market report is designed as an operational playbook for strategic and procurement leaders. Highlights include:
- Revenue-size market model (2020–2032) with scenario-based forecasts and sensitivity analyses tied to certification adoption rates and regional compliance timelines.
- Actionable buyer decision trees for 2026 procurement windows—covering capital replacement, retrofit vs. replace economics, and compliance risk mitigation.
- Competitive landscaping with capability matrices: product attributes, certification status, distribution reach, service capability, and digital feature-set comparisons for leading vendors.
- Supply-chain and cost-pressure assessment, identifying single-source risks, critical component bottlenecks (e.g., composite cylinders, advanced facepiece lenses), and mitigation levers for buyers and suppliers.
- Commercial playbooks for vendors: go-to-market strategies, aftermarket monetization models, pricing architecture, and strategic M&A themes attractive to private equity and corporate buyers.
- Operational tools: procurement templates, risk scoring frameworks, and an Excel-based model that allows users to re-run forecasts under client-specific assumptions.
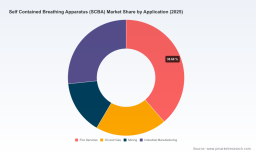
Note: To preserve the strategic value of our synthesis and to protect the integrity of model inputs, we intentionally do not disclose core segmentation granularity in this preview. The full report includes revenue splits by type, application, and region, along with underlying assumptions and modeled sensitivity ranges.
How executives should use these insights in 2026
- Procurement & Operations: Re-assess replacement schedules against NFPA 1970 adoption timelines. Prioritize models with confirmed certification to avoid mid-cycle rework and regulatory non-compliance exposures.
- Product & R&D Leaders: Fast-track facepiece materials and elevated-temperature testing programs. Consider modular upgrades (e.g., replaceable facepiece assemblies) to extend installed-base value and capture aftermarket revenue.
- Corporate Development & M&A: Focus on targets that provide service infrastructure, regional distribution strength, or proprietary components that mitigate the low-to-moderate market concentration and fragmented competitor landscape.
- Service & Aftermarket Teams: Build certification-assist offerings and subscription-based maintenance plans—these create sticky revenue and offset the capital variability of buyers.
- Risk & Compliance: Update supplier contracts to require proactive certification monitoring, recall protocols, and data-sharing clauses for model changes linked to NFPA or NIOSH updates.
Scenario thinking — three plausible 2026–2028 paths
- Baseline (most likely): Gradual adoption of certified models with pockets of accelerated procurement among high-risk users. Services expand steadily as providers capture retrofit and maintenance contracts.
- Accelerated regulatory adoption: Jurisdictional enforcement tightens, prompting earlier-than-expected fleet upgrades—favoring well-capitalized OEMs and lease/financing partners.
- Supply-constrained spike: Supply chain disruptions for critical components lengthen lead times, pushing buyers toward aftermarket retrofit solutions and rental fleets.
Conclusion — the strategic imperative for 2026
For 2026, the SCBA market is less about a single technology shift and more about timing, certification alignment, and service-led differentiation. The convergence of NFPA consolidation, updated certification listings, and recent vendor product certifications creates a narrow window in which procurement decisions will have outsized impact on compliance, cost, and operational readiness.
PW Consulting’s full SCBA Market report equips decision-makers with the models, scenario analyses, and commercial playbooks necessary to convert regulatory and market shifts into defensible strategies. If your organization faces capital allocation, vendor selection, or M&A decisions tied to SCBA capability, the full report will accelerate and de-risk those choices.
Next step
Access the complete report for the full segmentation, the downloadable forecasting model, and tailored advisory options from PW Consulting. The detailed segmentation and revenue builds have been withheld from this preview to preserve their strategic value—contact PW Consulting to obtain the complete dataset and a customized briefing aligned to your 2026 priorities.
For detailed analysis of this topic, please visit the official page: Self Contained Breathing Apparatus (SCBA) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com