

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Plastic Food Containers Market to Reach USD 344.8M by 2032 at 6.98% CAGR

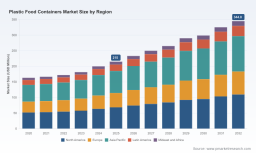
Plastic Food Containers Market — Strategic Outlook for 2026 Decision‑Makers
Executive snapshot
As companies prepare budgets and strategic roadmaps for 2026, the plastic food containers market presents a clear, measurable growth corridor — driven by secular demand for convenient foodservice solutions, accelerating regulatory pressure on packaging sustainability, and ongoing raw‑material volatility. Our research anchors decisions in a consolidated macro view: the market grew steadily through the 2020–2025 base period and, at a compound annual growth rate of approximately 6.98% across the 2026–2032 forecast window, is projected to expand further by 2032. This combination of predictable topline expansion and shifting structural forces creates both near‑term tactical choices and longer‑term strategic inflection points for manufacturers, brand owners, retailers, and investors.
Plastic Food Containers Market
Market trajectory and strategic implications
-
Scale and momentum. The market’s aggregate value rose through the early 2020s and reached our 2025 base year. Between 2025 and 2032 the market expands at close to a 7% CAGR, producing meaningful incremental volume and revenue opportunities for incumbents and entrants alike.
Plastic Food Containers Market -
Near‑term inflection. Our baseline forecast shows the market stepping up in 2026, reflecting recovery in out‑of‑home consumption and continued uptake of on‑the‑go formats. That near‑term uplift is where many 2026 commercial plans will be validated or need recalibration.
Plastic Food Containers Market -
Margin pressure and opportunity. Sustained demand provides room for revenue growth, but margin dynamics are increasingly determined by raw‑material cost volatility and the timing of compliance with new packaging mandates. Firms that can optimize material mixes, improve recycled content economics, and pass through costs selectively will secure outsized margins.
What’s changing — the dynamics you cannot ignore
-
Regulatory acceleration. Policymakers are shifting from aspirational targets to enforceable obligations. Recent regulations in major jurisdictions — including EU packaging mandates with binding recyclable‑by deadlines and regional extended producer responsibility (EPR) programs — create concrete compliance calendars and recycled content requirements that will become procurement and product design constraints for many businesses.
-
Localized bans and mandates. Several U.S. states have moved beyond guidance to prohibition and producer fee regimes for single‑use formats; these actions create patchwork compliance needs for national operators and open routes for differentiated regional strategies.
-
Raw‑material cost dynamics. Plastics resin price indices and producer price trends have risen and remain structurally more volatile than during the prior decade. This elevates the importance of hedging, long‑term offtake arrangements, and investment in recyclate supply chains.
-
Material innovation and commercialization. Partnerships between polymer innovators and established packaging firms are accelerating commercialization of non‑plastic and fully compostable alternatives — offering plausible substitution pathways for specific use cases in foodservice and retail.
Competitive landscape — strategic profiles and implications
The market is characterized by a mix of global packaging majors, specialized foodservice system suppliers, and high‑volume regional producers. While the sector is not tightly concentrated at the top, leading players exert influence through scale, channel relationships, and innovation capability. Key strategic takeaways from our company analysis:
-
Global integrated suppliers (e.g., Amcor plc, Berry Global, Sealed Air) — These players leverage broad polymer portfolios, advanced barrier and print capabilities, and direct customer relationships with brand owners. Their strengths lie in supplying large retail and consumer packaged goods programs and in deploying recycling and lightweighting at scale. For customers, these suppliers offer reliability and integrated sustainability roadmaps; for competitors, they raise the bar on technical and logistical capabilities.
-
Foodservice specialists (e.g., Dart Container, Pactiv Evergreen, Genpak, Sabert, Novolex) — Focused on quick‑service and foodservice channels, these firms compete on speed to market, product functionality (microwaveability, leak resistance), and compliance (PFAS‑free, compostable lines). Their agility means rapid product lineup changes and strong customer intimacy with restaurant chains.
-
Paper/plastic hybrid and sustainability innovators (e.g., Huhtamaki, International Paper) — These incumbents are actively pursuing alternative substrates and partnerships to deliver plastic‑free and recyclable options. Their strategic moves are relevant for customers shifting to paper or polymer‑free propositions and for manufacturers planning to augment portfolios to satisfy EPR and recyclability rules.
-
Regional exporters and contract manufacturers (e.g., Jinhua Lanxin) — Price‑sensitive channels remain served by high‑volume regional suppliers; these companies matter for private‑label programs and cost optimization in price‑competitive markets.
Recent corporate developments underscore these dynamics: expansion of sustainable production capacity by a major paper‑based supplier, partnership agreements to commercialize plastic‑free food packaging, and extensions to compostable product lines with PFAS‑free claims. Each move demonstrates how product innovation and capacity investments are being used defensively and offensively to capture upgrade cycles among buyers while responding to regulation.
What our full report delivers — practical tools for 2026 action
Beyond macro trends and corporate profiles, the report provides a suite of decision‑grade deliverables designed for 2026 planning cycles:
-
Commercial playbooks for OEMs and brand owners — channel segmentation, pricing levers, and margin optimization paths across retail and foodservice.
-
Regulatory compliance matrix and timeline — jurisdictional impact assessments, cost-to‑comply estimates, and recommended compliance sequencing.
-
Material strategy models — comparative cost and carbon models for resin types, mixed‑material constructions, and recyclate supply scenarios.
-
Supplier scorecards and negotiation templates — capability mapping, risk scoring, and suggested contractual terms to secure feedstock and capacity.
-
Strategic M&A and partnership shortlist — screens for targets that deliver access to recyclate streams, biodegradables, or high‑value foodservice channels.
-
Scenario and sensitivity analyses — upside/downside demand cases, pass‑through pricing mechanics, and capex breakeven horizons under multiple resin price paths.
To preserve competitive value in this “trailer” overview, granular sub‑segment tables and region/application percentage breakdowns are withheld here; the full interactive datasets, dashboards and templates are available in the complete PW Consulting report.
Actionable recommendations for 2026
-
Prioritize compliance‑first product redesigns for jurisdictions with near‑term mandates — map SKUs to regulatory calendars and sequence reformulations where cost‑to‑comply is highest.
-
Accelerate recyclable/recycled content integration where economics are close — pilot with strategic customers to co‑share supply risk and to generate data for EPR reporting.
-
Hedge or contractually stabilize resin supply — deploy a mix of short‑term hedges and multiyear offtakes to reduce margin volatility while retaining flexibility for material substitution.
-
Expand compostable and paper‑based options selectively — focus on use cases where post‑consumer collection is feasible or where brand value justifies a premium.
-
Pursue bolt‑on M&A in recyclate, sorting, and specialty trays to access feedstock and narrow the gap with larger integrated rivals; consolidation is an effective path to scale in a fragmented market.
-
Build customer partnerships to co‑fund recyclate sourcing and to trial circular‑economy pilots — shared investment reduces the adoption barrier and accelerates regulatory compliance.
-
Revise commercial contracts to incorporate cost escalation triggers tied to resin indices and to include sustainability KPIs that are auditable for EPR reporting.
-
Invest in traceability and labeling capabilities — transparency will be required by many buyers and regulators as recyclability claims and recycled content thresholds rise.
Why this matters for 2026 planning
Market growth provides the revenue runway for product and capability investments; regulatory timelines and raw‑material dynamics define the risk and cost horizon. With the market expanding robustly through the end of the decade, 2026 is a high‑leverage year: decisions made now about materials, partnerships, capacity, and commercial terms will determine which players capture the bulk of incremental value. The market is large enough to reward both scale and smart differentiation, yet sufficiently fragmented that well‑timed consolidation or vertical integration can rapidly change competitive positions.
Next steps
PW Consulting’s complete Plastic Food Containers Market report contains the full data matrices, regional and application splits, interactive scenario tools, supplier scorecards, and a downloadable strategic playbook tailored for 2026 implementation. For executives building budgets, procurement leaders negotiating resin contracts, and investors sizing acquisition opportunities, the full report is the operational reference you’ll use through the 2026 planning cycle.
To access the comprehensive datasets, sub‑segment analyses, and proprietary modeling used to generate the forecasts and recommendations summarized here, please download the full report on our website or contact the PW Consulting advisory team for a tailored briefing.
For detailed analysis of this topic, please visit the official page: Plastic Food Containers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com