

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Optical Isolators Market Set to Expand at 5.38% CAGR Through 2032

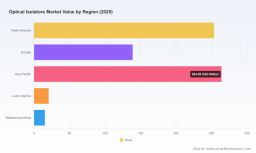
Optical Isolators Market — Strategic Briefing for 2026 Decision-Makers
As companies plan resource allocation for 2026, the optical isolators market presents a mix of steady demand expansion, concentrated supply-side risks, and accelerating product innovation. PW Consulting’s base-year 2025 study values the global optical isolators market at USD 692.91 Million and projects the market to reach approximately USD 1,001.42 Million by 2032, representing a compound annual growth rate (CAGR) of 5.38% over the 2026–2032 forecast horizon. These headline metrics mask a nuanced competitive landscape: market concentration remains modest (CR3 ≈ 24.5%; CR5 ≈ 32.1%), indicating room for both incumbent scale plays and specialist challengers.
Optical Isolators Market
Why this analysis matters for 2026 strategy
-
Resource allocation under uncertainty: The market’s mid-single-digit CAGR supports continued investment, but supply-side shocks and component cost inflation demand disciplined capital deployment and contingency planning.
Optical Isolators Market -
Product and channel differentiation: Advances in chip-scale isolators, SWaP-optimized modules, and high-power fiber solutions are changing buyer economics across telecommunications, data centers, industrial lasers, medical devices, and defence systems.
Optical Isolators Market -
M&A and partnership timing: Fragmentation and specialized IP pockets create opportunities for bolt-on acquisitions and strategic partnerships—timing and target selection will be decisive.
-
Procurement and risk management: Firms that systematically stress-test their raw material and supplier exposure will avoid costly lead-time and price shocks that can erode margins and time-to-market.
What PW Consulting’s report gives you — operational, decision-ready outputs
-
Market sizing and forecast model (base year 2025, forecast period 2026–2032) with scenario variants (base, constrained-supply, accelerated-innovation) to quantify revenue and margin sensitivity.
-
Supplier risk heatmap and lead-time stress tests, including probabilistic scenarios for YIG and rare-earth availability and cost pass-through impacts on product-level gross margins.
-
Technology roadmaps mapping incumbent Faraday-based isolators against emerging chip-scale and femtosecond-written waveguide approaches; TRL (Technology Readiness Level) assessments and commercialization timelines.
-
Go-to-market playbooks by buyer segment (telecom, data center, industrial lasers, medical, military/aerospace), covering value propositions, pricing benchmarks, and channel strategies.
-
Manufacturing and SWaP optimization templates for product engineering teams, including thermal management and integrated TEC/isolator module design considerations.
-
M&A screening and valuation framework tailored to optical isolator synergies—target criteria, expected synergies, and integration risk checklists.
-
Regulatory and IP watchlist—patent fences, quality standards (including mandatory quality certifications for high-reliability products), and export-control sensitivities affecting cross-border supply chains.
Competitive landscape: incumbents, challengers, and strategic moves
The market comprises global optical-component houses, laser-system integrators, and specialized micro-optics startups. Notable players include established optics suppliers and laser OEMs headquartered across North America, Europe, and Asia. Key strategic positions observed:
-
Thorlabs (Newton, NJ, USA) continues to leverage a broad product catalog across visible and NIR wavelengths, appealing to laboratory and OEM buyers that value configurability and catalog depth.
-
TOPTICA Photonics SE (Garching, Germany) competes on high-isolation tunable free-space isolators for laser-integration use cases, targeting precision and performance-sensitive customers.
-
Coherent (Milpitas, CA, USA) is focusing on integrated modules and higher average power handling; recent investor communications highlight product demos combining lasers, isolators, and thermal control modules—an important direction for integrators seeking turnkey subsystems.
-
CrystaLaser (Reno, NV, USA), OZ Optics (Ottawa, Canada), and LightComm Technology (Nanjing, China) are advancing high-power fiber-to-fiber and fiber-to-free-space isolator capabilities, reflecting rising demand from high-power industrial and scientific lasers.
-
Edmund Optics and Newport Corporation remain influential through distribution channels and SWaP-optimized offerings, making them preferred suppliers for rapid procurement cycles.
-
Startups and specialized design houses—Agiltron, AC Photonics, GLSUN, and AEPONYX—are investing in narrowband/broadband fiber isolators, integrated photonic isolators, and chip-scale fabrication techniques that could upend cost and footprint assumptions over the medium term.
Recent product and market events reinforce these trends: Edmund Optics launched compact SWaP-optimized isolators in April 2025; AEPONYX announced femtosecond direct-write spiral waveguide isolator demonstrations in late 2025; Advanced Fiber Resources showcased dual-stage high-power designs at Photonics West 2026; Coherent’s March 2026 investor presentation emphasized module-level integration. These moves underscore a bifurcation in customer demand—between tried-and-true high-reliability Faraday isolators for critical applications and a rising appetite for integrated, lower-footprint solutions where cost and size drive adoption.
Critical market dynamics and risks in 2026
-
Material and supplier risk: Supply interruptions at Japanese YIG producers have materially extended lead times, with market intelligence indicating single-stage isolator lead times exceeding 14 weeks and an estimated ~14% annual cost pressure through 2026. Geopolitical concentration of terbium and dysprosium supply further amplifies this vulnerability.
-
IP and regulatory shifts: Recent patent grants related to lower-loss mounting and mechanical designs (granted late 2025) shift the innovation boundary and can affect licensing and integration strategies. Concurrently, quality certifications (e.g., ISO 9001) remain de facto requirements for high-reliability production—non-compliance creates go-to-market barriers.
-
Innovation acceleration: Chip-scale and femtosecond direct-writing techniques lower unit cost and footprint, threatening the incumbent value chain—but those approaches have funnelled into the market unevenly, with performance trade-offs that buyers will evaluate carefully.
-
Concentration and channel dynamics: Moderate market concentration leaves room for consolidation but also for niche specialists; distributors and systems integrators will remain gatekeepers for many OEMs.
Strategic playbook for 2026 — prioritized actions
-
Immediate (0–12 months): perform supplier stress tests, secure contingent supply contracts for YIG and rare-earth inputs, implement agile pricing clauses to mitigate short-term cost inflation, and fast-track SWaP product concepts for laser OEM partners.
-
Near-term (12–24 months): invest selectively in chip-scale R&D partnerships, pursue co-development with laser integrators to bundle isolators with thermal control and electronics, and deploy targeted M&A to acquire capability gaps—particularly in integrated isolator modules and fiber-to-fiber high-power solutions.
-
Medium-term (24–36 months): strengthen IP position through defensive patents on mounting and integration techniques, consider vertical assurance for critical magnet/rotator supplies, and scale manufacturing with focus on automation and quality controls that meet medical and aerospace certifications.
-
Ongoing: maintain a regulatory and geopolitical watch; calibrate inventory policy to balance working capital with the risk of 14+ week lead times; develop contingency logistics routes and dual-sourcing strategies.
How PW Consulting’s Optical Isolators Market report accelerates your 2026 decisions
The full PW Consulting deliverable operationalizes the executive brief above into actionable artifacts: downloadable financial models, supplier scorecards, prioritized target lists for partnership or acquisition, and step-by-step go-to-market templates customized by buyer segment. To preserve competitive value for subscribing clients, this briefing intentionally abstracts granular segment-level revenue splits and channel-level pricing tables. Those detailed worksheets—covering regional and application breakdowns, product-level ASP curves, and granular unit forecasts—are available in the complete report package and are essential for building internal business cases and investment memoranda.
For executives evaluating capacity investments, launch timing, or acquisition targets in 2026, the combination of medium-term market growth (CAGR 5.38% through 2032), supply fragility around Faraday rotator inputs, and accelerating product innovation creates a window of opportunity—and risk. Organizations that align procurement resilience, targeted R&D, and selective inorganic moves will convert market growth into lasting competitive advantage.
PW Consulting’s Optical Isolators Market study is designed to be the operational backbone for those moves. Access to the full dataset and models will enable you to quantify trade-offs, prioritize investments, and execute with confidence in 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Optical Isolators Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com