

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Reveals RMC Market at USD 760 Billion in 2025, Poised for 8.1% CAGR

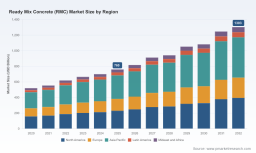
Ready Mix Concrete (RMC) Market — Strategic Preview for 2026 Decision-Makers
As PW Consulting’s lead industry analyst, I present a concise strategic preview of our forthcoming Ready Mix Concrete (RMC) Market study. This piece is written as a decision-oriented trailer: it synthesizes the macro dynamics, competitive fault lines, and near-term regulatory and supply risks that will matter most to executives in 2026, while preserving the report’s proprietary, granular segment-level intelligence for subscribers.
Ready Mix Concrete (RMC) Market
Executive snapshot
The global RMC market has entered a phase of structurally higher growth. After a steady climb through the early 2020s, the market reached an estimated USD 760 Billion in our base year (2025). Our modelling projects a compounded annual growth rate (CAGR) of 8.1% across the 2026–2032 forecast window, taking the market well beyond the USD 1 trillion threshold within the decade. At the same time, the market shows moderate concentration — the top three players account for roughly a third of industry revenues, while the top five approach mid‑forties — signalling both scale advantages and meaningful opportunities for regional or capability-focused challengers.
Ready Mix Concrete (RMC) Market
Why this matters for 2026 corporate strategy
- Timing and prioritization of capital: With an elevated growth trajectory, 2026 will be a critical inflection point for capex phasing. Companies that sequence plant investments, fleet expansions, and automation projects to coincide with regional demand upticks will capture outsized returns while avoiding costly overcapacity.
- Regulatory-driven product repositioning: Emerging procurement rules and low‑carbon codes are shifting specification power toward certified low‑emission mixes. Producers who can rapidly operationalize low‑carbon binders and document Environmental Product Declarations will secure projects that increasingly favour decarbonized material sourcing.
- Supply-chain differentiation: Raw material volatility — especially on cement clinker, fly ash and slag availability — will distinguish resilient operators from those exposed to input cost swings. Integrating backward (strategic sourcing / alternative binders) or forward (logistics and on‑site services) will be decisive for margin protection.
- M&A and joint‑ventures as accelerants: Given the market’s mix of scale benefits and regional fragmentation, 2026 is likely to see targeted consolidation and capability-based partnerships (sustainability tech, dispatch systems, admixture suppliers) rather than broad roll-ups.
Market sizing and growth drivers — a data-driven view
Our base-year assessment and seven-year forecast are built from a bottom-up aggregation of production, construction starts, concrete intensity metrics and logistics constraints, plus scenario stress‑testing against input‑cost shocks and regulatory scenarios. The headline numbers given above reflect a convergence of demand tailwinds — infrastructure renewal, urban housing programmes in emerging markets, and an uptick in heavy commercial construction — combined with supply-side modernization that improves utilization rates.
Ready Mix Concrete (RMC) Market
Key growth drivers we quantify and stress-test in the full report include:
- Public infrastructure investments and their multi-year project pipelines.
- Urban densification and mid‑rise residential programs that alter per‑project concrete intensity.
- Technological adoption (dispatch/route optimization, plant automation) that reduces lead time and increases on‑spec delivery capacity.
- Decarbonization policies that create premium pricing bands for low‑carbon RMC variants.
Practical outputs inside the full report (what executives will use in 2026)
This study is structured as a playbook, not just a narrative. Highlights of the practical deliverables include:
- Actionable investment matrices that map capacity decisions to demand scenarios and payback windows, with sensitivity to input‑cost stress and carbon‑price assumptions.
- Go‑to‑market playbooks for launching low‑carbon product lines, including operational checklists for binder substitution, EPD generation, and client procurement engagement templates.
- Logistics optimization frameworks that translate route and fleet data into utilization KPIs and ROI on telematics and dispatch software investments.
- Regulatory readiness checklists for major procurement regimes, including documentation workflows for Environmental Product Declarations and compliance templates aligned to state/provincial code changes.
- Competitive benchmarking dashboards covering capacity, vertical integration indices, product portfolios, and M&A appetites — designed for boardroom briefing and investment committee use.
Competitive landscape — strategic posture of the incumbents
The RMC industry’s incumbent set blends global integrated materials majors with strong regional specialists. Our report profiles the strategic positioning and tactical moves of the leading players, and synthesizes where each is likely to compete or collaborate in 2026:
- CEMEX S.A.B. de C.V. (Monterrey): A global RMC and materials leader with scale in batching plants and specialist mixes. CEMEX’s strengths are its broad distribution network and experience in tailored mixes for infrastructure projects. Expect continued investment in logistics digitalization and sustainability claims as a competitive differentiator.
- LafargeHolcim Ltd. (Zurich): An integrated materials supplier with a strong portfolio of high‑performance and low‑carbon concrete solutions. Their global R&D and product standardization give them leverage in markets tightening specifications; watch for partnerships that accelerate binder alternatives.
- HeidelbergCement AG (Heidelberg): A heavyweight in customizable mixes for infrastructure, whose European footprint and manufacturing depth position it well for projects requiring certified EPDs. Strategic moves may focus on regional consolidation and technology licensing.
- Buzzi Unicem S.p.A. (Milan): A quality‑focused producer with a pronounced European presence. Likely to pursue premium market segments and selective technology upgrades rather than aggressive scale plays.
- China National Building Material Co., Ltd. (Beijing): A capacity powerhouse capable of supplying large-scale mixes. Its extensive batching network and process efficiencies make it a formidable contender in markets that prize scale and price competitiveness.
- CRH plc (Dublin), Vicat SA (Paris): European materials groups with growing low‑carbon portfolios and regional service capabilities; strategic playbooks will center on sustainable product rollouts and procurement channel partnerships.
- U.S. Concrete, New Enterprise Stone & Lime, Martin Marietta Materials (U.S.): Regional U.S. players with tight integration to heavy construction and highway work. Expect targeted capacity builds, fleet modernization and bidding strategies aligned to fast‑moving infrastructure programmes.
Across the board, the incumbents vary in approach — some are pushing product innovation and sustainability certification, others emphasize logistics efficiency and local relationships. That divergence creates white space for nimble challengers to win RFPs by aligning price, documented emissions, and reliable delivery cadence.
Recent signals and near‑term events to watch
- Greenfield capacity and strategic consolidations — several operators opened low‑emission or additional plants in 2025, signalling renewed appetite for localized capacity to meet sustainability‑driven demand.
- Industry trade shows and technology expos in 2025 showcased dispatch software, dosing systems and logistics innovations — a clear marker that digitization will be an operational battleground over the next 18 months.
- Regional strategic merges and alliances are accelerating at the country level; these moves are tactical to secure feedstock, expand mix portfolios, or accelerate certification pipelines for public contracts.
Regulatory and raw‑material dynamics that will reshape margins
Two sets of non‑market forces will drive strategic choices in 2026: raw material composition and procurement/low‑carbon regulation.
- Carbon intensity and binder mix: Portland cement continues to represent the bulk of concrete’s lifecycle emissions. Industry trends show a modest decline in clinker‑to‑binder ratios in recent years, but the pace will need to quicken for producers to meet tightening procurement standards without eroding physical performance. Investing in alternative binders, admixtures and supply contracts for by‑product materials will become a line‑item strategy.
- Procurement codes and EPDs: Jurisdictions are moving from aspirational targets to enforceable procurement rules. For example, codes that cap allowable GWP per cubic metre and “Buy Clean” style laws raising transparency requirements are already changing bid dynamics for medium‑ and large‑scale projects. Companies that can operationalize EPD generation and embed low‑carbon mixes into standard offerings will gain preferential access to public and institutional spend.
How to use this preview — recommended executive actions for 2026
- Reassess capex timing against our demand scenarios: defer non‑critical expansions while accelerating investments that unlock low‑carbon mix capability or logistic efficiencies.
- Prioritize compliance playbooks: ensure at least one product line per major market is fully EPD‑certified and contract‑ready for Buy Clean and similar regimes.
- Forge supply partnerships for alternative binders and by‑product inputs to stabilize input cost volatility and secure low‑carbon feedstocks.
- Pilot dispatch and batch‑plant automation programs in high‑density corridors to extract utilization gains and reduce variance in delivery quality.
- Targeted M&A: look for tuck‑ins that add local footprint, digital capability, or sustainability credentials rather than headline market share alone.
Next steps — where the full intelligence lives
This preview highlights the structural forces and competitive playbooks that will define success in the RMC market during 2026. Our full report contains the granular, executable intelligence that executives and investment committees need: segmented demand models, regional plant‑level capacity maps, supplier scorecards, pricing ladders for low‑carbon mixes, and playbooks for procurement compliance. That level of granularity is intentionally reserved for subscribers to ensure confidentiality and actionable advantage.
If your 2026 roadmap includes capacity allocation, sustainability certification, or M&A, the full PW Consulting RMC Market study will give you the scenario tools and operational checklists to move from strategy to execution with confidence.
For detailed analysis of this topic, please visit the official page: Ready Mix Concrete (RMC) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com