

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Mobile Phone Insurance Ecosystem to hit USD 68.6B by 2032 (8.5% CAGR)

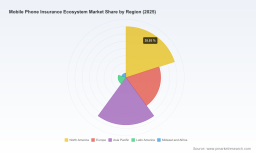
Mobile Phone Insurance Ecosystem Market — Strategic Briefing for 2026 Decision Makers
Executive snapshot
Between 2020 and 2025 the global mobile phone insurance ecosystem expanded from a nascent protection market into a mature, digitally enabled commercial channel — rising from roughly USD 23.4 Billion in 2020 to USD 39.0 Billion in 2025 (base year). Our analysis projects continued, steady expansion through the forecast window (2026–2032) and expects the market to approach roughly USD 68.6 Billion by 2032, underpinned by an 8.5% CAGR across the forecast period. This growth trajectory reflects the confluence of higher device penetration, subscription-style protection products, improved digital activation and claims flows, and new distribution models embedded in OEM, carrier and retail platforms.
Mobile Phone Insurance Ecosystem Market
Why this report matters to executives in 2026
-
Strategic clarity in a dynamic growth market: As the mobile phone insurance ecosystem scales, 2026 is a pivotal year for resource allocation — whether to double down on product innovation, establish exclusive distribution partnerships, or pursue bolt-on M&A. The report synthesizes macro drivers and micro levers so leaders can translate growth forecasts into capital and operating decisions.
Mobile Phone Insurance Ecosystem Market -
Regulatory and operational inflection points: Repairability rules, consumer protection mandates and evolving warranty standards are reshaping claims eligibility, repair economics and time-to-resolution. Our analysis isolates where regulatory changes materially affect loss ratios, reserve requirements and service-level expectations.
Mobile Phone Insurance Ecosystem Market -
Competitive differentiation that matters: With the market moderately concentrated (top three players account for approximately 30% of the market and the top five about 38%), the remaining share is addressable through superior digital experiences, distribution exclusives, and cost-efficient repair networks. The report maps which capabilities drive a sustainable competitive moat.
Market trajectory and what the headline numbers hide
The headline growth (from USD 39.0 Billion in 2025 to a projected USD ~68.6 Billion by 2032 at an 8.5% CAGR) belies significant heterogeneity beneath the aggregate. Growth pockets differ by distribution model (carrier-led vs retailer-led vs OEM direct), product architecture (subscription bundles, per-incident indemnity, theft-and-loss vs repair-first), and claims economics (regional repair supply chains, certified-part availability, and right-to-repair impacts). This briefing intentionally emphasizes structural trends and decision-relevant KPIs while withholding granular segment datapoints — the full report contains detailed splits by region, phone type and coverage that are essential when modeling your commercial options.
What the report delivers — practical, executable content
-
Actionable go-to-market frameworks: Channel prioritization matrices that match product archetypes to commercial partners (OEMs, carriers, retailers, marketplaces) and quantify relative CAC, lifetime value and payback timelines.
-
Underwriting and pricing playbooks: Loss-ratio modeling templates, pricing sensitivity analyses for subscription vs single-incident models, and scenario-tested reserve guidance for 2026 regulatory regimes.
-
Claims and operations blueprint: End-to-end process maps for digital onboarding, remote diagnostics, and automated adjudication, including vendor-selection criteria for repair network partners and third-party logistics.
-
Regulatory impact assessments: Market-by-market implications from recent and pending regulations (consumer repairability standards, insurance consumer disclosure rules), with operational remediation plans and compliance checklists.
-
Technology & data strategy: Roadmaps for integrating device telemetry, app-based diagnostics, anti-fraud AI, and customer experience orchestration through single-pane dashboards.
-
M&A and partnership playbook: A prioritized target list archetypes, valuation benchmarks, diligence KPIs (claims leakage, repair yield, churn), and integration checklists to accelerate scale.
-
Financial models and KPI dashboards: Buildable models for unit economics, channel-level contribution margins, payback curves and scenario stress tests for macro shocks (device supply, regulatory change, repair cost inflation).
Competitive landscape — what matters to buyers, partners and acquirers
The competitive field is shaped by a mix of large vertically integrated players (OEMs and global insurers), specialized device protection specialists, and regional retail or carrier ecosystems. Four firms illustrate strategic archetypes you’ll encounter in 2026:
-
Apple Inc. — OEM-led subscription dominance: Apple’s launch of AppleCare One in July 2025 demonstrates the OEM playbook: subscription bundling across device families, frictionless digital activation, and integrated claims routing. OEMs can leverage brand trust, device telemetry and repair-channel control to command higher attach rates, but they must invest in scalable claims automation and cross-device pricing math to keep unit economics healthy.
-
Asurion LLC — carrier and retail distribution specialist: Asurion represents the carrier/retailer partnership model, combining wide distribution reach with consolidated claims processing and loss-prevention programs. Success here depends on optimizing per-claim cost and reducing fraud through data-sharing alliances with carriers; the business is sensitive to contract terms and revenue-share structures.
-
Assurant Inc. — integrator for partners and OEMs: Assurant operates as a B2B integrator, providing embedded protection services to carriers, retailers and OEMs. The differentiator is the ability to offer end-to-end managed services — underwriting, claims adjudication, and repair logistics — while keeping partner APIs and customer experiences consistent.
-
Allianz SE — insurer leveraging underwriting scale and AI: Allianz’s approach combines traditional underwriting discipline with emerging AI-driven claims orchestration in select markets. Global insurers can underwrite cross-border risks and deploy reinsurance strategies, but must localize products and claims processes to maintain regulatory compliance and customer satisfaction.
Regulatory and market dynamics shaping 2026 strategy
-
Right-to-repair and repairability standards: The EU’s Replaceable Battery Regulation (effective 2026) is a clear inflection — repair timelines, part availability and eligibility criteria for accidental damage claims are now encoded into compliance workflows. Insurers and service providers must rework repair SLAs, supplier contracts, and claims adjudication rules to align with evolving repairability requirements.
-
Retailer and platform innovations: Leading retailers have begun integrating extended protection products into point-of-sale and omnichannel platforms (for example, new retail insurance offerings introduced in 2025), shifting where and how customers encounter protection options. If you are a carrier or insurer, embedding into checkout and post-purchase communications is non-negotiable for attach-rate targets.
-
Embedded business services: Telecom and platform players have accelerated embedding insurance into broader SME and consumer packages (e.g., integrated protection services launched by major telcos in 2025). Such bundling reduces distribution friction but compresses margins when not coupled with exclusive servicing rights or data-sharing agreements.
-
Targeted, low-cost products: Insurers are experimenting with highly price-sensitive segments (student and entry-level plans introduced regionally in 2024–2025). These products increase penetration but require lean operations and alternative pricing constructs to remain viable.
-
Digital claims automation and AI: Across incumbents, AI-enhanced adjudication and fraud detection are moving from pilots to production. The technology reduces average cost-per-claim and turnaround time, creating measurable NPS uplifts and lower churn if integrated tightly with repair network orchestration.
Strategic imperatives for 2026 — what leaders should prioritize
-
Prioritize distribution scaffolding over standalone product innovation. While product differentiation remains important, the biggest near-term wins come from securing exclusive or favored positions within OEM, carrier and retailer ecosystems.
-
Invest now in claims automation and repair-supply resilience. Given repairability regulation and part-sourcing risks, build multi-sourcing strategies for repairs and standardized digital diagnostics to shorten cycle times and protect margins.
-
Adopt a portfolio approach to pricing. Mix subscription bundles for premium segments with simplified, automated low-cost products for price-sensitive cohorts. Use layered service-levels to protect premium economics.
-
Lock in data-sharing agreements. Telemetry and usage signals materially improve underwriting accuracy and fraud detection. Negotiate access to device diagnostics and carrier-originated signals as part of distribution contracts.
-
Prepare for regulatory variability. Build flexible policy wordings and modular claims rules engines so products can be localized without heavy rewrites or manual adjudication.
-
Explore inorganic options selectively. With market concentration moderate, targeted M&A or partnership plays (repair networks, niche insurers with proprietary distribution, or fraud-tech firms) can accelerate capability build and scale.
How to use this briefing and next steps
This briefing is a strategic primer designed to align leadership conversations and investment priorities in 2026. The full Mobile Phone Insurance Ecosystem Market report from PW Consulting includes the granular inputs necessary for transaction diligence, pricing model implementation, channel-specific playbooks and prioritized operational KPIs. To convert the directional insights above into executable plans — including downloadable financial models, vendor shortlists, and a 90–180 day implementation roadmap calibrated to your operating model — access the complete report and supporting data package on our site.
Final note
We intentionally limit the disclosure of detailed segment-level figures in this overview to preserve the utility of the analyses and to encourage targeted engagement. If you are evaluating strategic moves — whether product launches, distribution partnerships, or M&A activity — schedule a briefing with our industry leads to walk through the full dataset, scenario models and customized recommendations tailored to your organization’s objective in 2026.
For detailed analysis of this topic, please visit the official page: Mobile Phone Insurance Ecosystem Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com