

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Heat Sinks Market: 7.5% CAGR to USD 13.73M by 2032 | PW Consulting

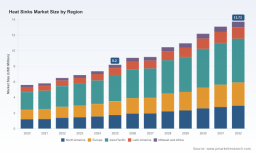
Heat Sinks Market 2026 Outlook: Strategic Briefing for Executive Decision-Making
As PW Consulting’s Chief Industry Analyst, I present an executive introduction to our latest Heat Sinks Market study — a research product designed to be immediately actionable for leadership teams planning capital allocation, supply-chain redesign, product roadmaps, and M&A in 2026. This briefing summarizes the strategic implications of the market’s current trajectory, highlights structural forces shaping competition, and outlines the practical tools within the full report that will be indispensable to decision makers. In line with the “trailer” principle, we demonstrate analytical depth while intentionally withholding granular sub-segment datapoints to encourage direct access to the full intelligence package.
Heat Sinks Market
Market Trajectory and What It Means for 2026
The heat sinks market has entered a sustained growth phase. Measured on a USD (Million) basis, the market expanded from the low-single-digit millions in 2020 to an estimated 8.2 (USD Million) in the 2025 base year. Our 2026–2032 forecast assumes a compound annual growth rate of 7.5% and points to a market size north of 13.7 (USD Million) by 2032. That trajectory is not speculative; it reflects technology-driven demand (high-density computing, power electronics in EVs, and telecom infrastructure), and structural shifts in manufacturing and trade that are re-shaping unit economics and supplier footprints.
Heat Sinks Market
For 2026 corporate planning cycles, three implications are immediate:
Heat Sinks Market
- Investment timing: With a mid-single-digit to high-single-digit CAGR, 2026 is a window to lock in capacity expansions before the mid-decade acceleration in advanced cooling solutions (vapor chambers, liquid cooling) materializes.
- Risk-reward calibration: Margins will be under pressure in commoditized aluminum extrusion lines but can be materially higher in engineered solutions and integrated thermal subsystems.
- Portfolio prioritization: Firms should prioritize product lines tied to AI datacenter cooling, power electronics for automotive, and high-reliability industrial applications — segments that are driving the bulk of near-term value capture.
Market Structure and Competitive Dynamics
The market remains fragmented. Our concentration analysis indicates a low top-three/top-five share (CR3 ≈ 24.6%; CR5 ≈ 26.2%), signaling opportunity for new entrants and for incumbent consolidation through product differentiation and service-led offerings. Below I summarize the strategic positioning of the principal players covered in our competitive landscape chapter.
- Aavid Thermalloy (Laconia, NH, USA) — https://www.aavid.com/ Focus: Extruded aluminum and bespoke thermal management systems for electronics and industrial customers. Strategic angle: scale in precision extrusion and aftermarket service bundles give Aavid advantages in mid-volume OEM programs.
- Advanced Thermal Solutions (Lawrence, MA, USA) — https://www.qats.com/ Focus: Device-specific heat sinks and fan sinks optimized for AI processors, CPUs, GPUs, and embedded systems. Strategic angle: strong engineering-led sales and custom-design acuity for high-performance computing (HPC) and enterprise AI.
- Ohmite Manufacturing Company (Skokie, IL, USA) — https://www.ohmite.com/ Focus: Industrial and custom units for power resistors and high-power devices. Strategic angle: depth in ruggedized thermal solutions and institutional relationships in industrial power electronics.
- Radian Thermal Products (USA) — https://radianheatsinks.com/ Focus: Plate-fin, vapor chamber, and liquid cooling solutions across standard and custom lines. Strategic angle: breadth of cooling technologies positions Radian to supply integrated thermal subsystems for next-gen server and telecom racks.
- Wellste Aluminum (Zhejiang, China) — https://www.wellste.com/ Focus: Extruded aluminum heat sinks serving industrial and consumer electronics needs. Strategic angle: cost leadership in commodity extrusions, with near-term exposure to tariff and freight volatility.
- Alpha Company Ltd. (Japan) — https://www.alphanovatech.com/ Focus: High-performance heat sinks including vapor chambers and copper-embedded products. Strategic angle: technology-first positioning and premium OEM relationships in high-reliability sectors.
- Heatell (Jiangsu, China) — https://www.heatell.com/ Focus: Round extrusions and custom aluminum solutions. Strategic angle: flexible manufacturing for mid-tier OEMs and quick-turn prototyping capabilities.
The competitive chapter in the full report contrasts these players across a consistent set of metrics: product breadth, engineering depth, NPI cycle time, supply-chain resilience, regulatory compliance, and channel access. We also map likely strategic moves each company is positioned to make in 2026 (e.g., vertical integration into cooling subsystems, selective joint development with semiconductor customers, or capacity re-shoring). The report stops short of revealing proprietary revenue splits for each vendor — a deliberate choice to preserve proprietary commercial sensitivity while providing actionable comparative judgment.
Industry Dynamics: Trade, Materials, and Regulation
Three cross-cutting dynamics are shaping 2026 decisions:
- Raw material pricing and trade policy: Geopolitical trade measures are directly influencing landed costs and supply choices. Notably, a US tariff environment on certain imports has materially increased landed costs for some cross-border supply flows. Buyers sourcing from exposed geographies should expect elevated landed costs and build-in scenario buffers to procurement models.
- Regulatory and compliance constraints: Access to regulated markets (notably the EU) is contingent on RoHS and REACH compliance, and quality management certifications (ISO 9001, ISO 14001) remain decisive purchase filters for export-focused suppliers. Documented compliance is therefore as important as product performance when competing for Tier-1 OEM contracts.
- Technology substitution: The product mix is evolving from plain extrusions to high-value engineered solutions (vapor chambers, embedded copper, liquid cold plates). This transition changes the supplier cost curve and creates a premium for thermal engineering capability.
For procurement teams and business unit heads, the implication is clear: value capture will depend as much on supplier QA/RA (quality and regulatory assurance) and inventory strategy as on raw per-unit pricing.
Recent Market Signals (Early 2026)
Early-2026 product and portfolio moves underscore the market’s bifurcation between commodity extrusion volumes and advanced cooling for high-density computing:
- Asetek commercialized next-generation AI-optimized liquid cooling heat sinks for high-density server racks (Feb 2026), signaling rapid commercialization timelines for datacenter cooling innovations.
- Momentive Technologies introduced ultra-thin ceramic heat sinks tailored to advanced 3D semiconductor packaging (Jan 2026), highlighting materials diversification beyond aluminum and copper for thermal challenges in miniaturized packages.
- Radian Thermal Products refreshed its catalogue (Mar 2026) with expanded plate-fin, vapor chamber, and liquid cooling options — a move that reinforces the need for buyers to consider total system performance, not just component cost.
These moves validate our thesis that 2026 will be a pivotal year for product differentiation and that OEMs will increasingly source complete thermal subsystems rather than discrete components alone.
What’s Inside the Full PW Consulting Report (Practical Deliverables)
The complete study provides operational tools and decision-enabling content crafted for executive teams and functional leaders:
- Market sizing and validated forecast model (2020–2032) with scenario toggles for raw material shocks, tariff regimes, and demand shocks in datacenter and automotive segments.
- Supplier scorecards and a go/no-go procurement matrix to assess vendor readiness on engineering capability, compliance, lead times, and total landed cost.
- Modular playbooks for capacity expansion, technology transition (e.g., from extrusion to vapor chamber capabilities), and nearshoring strategies — complete with capex estimates and payback ranges.
- Tariff and input-cost sensitivity models (including scenarios for aluminum price and scrap dynamics) that quantify margin impact under prevailing trade measures.
- Commercial due diligence templates for M&A and joint-venture evaluation, and negotiation playbooks for entering long-term supply agreements with high-growth OEMs.
We intentionally withhold granular region/application/type splits in this briefing. The full dataset in the report provides these sub-segment specifics and interactive dashboards that are essential for target-setting and channel strategy building.
Recommended 90‑Day Executive Action Plan for 2026
To translate the intelligence into operational advantage, consider this condensed plan:
- Immediate: Run an exposure audit of your supply chain to quantify tariff and freight impact on near-term P&L. Use our tariff sensitivity module to test three procurement scenarios.
- Short-term (60 days): Initiate design-for-thermal (DfT) workshops between product engineering and procurement to identify where higher-value thermal solutions can justify premium pricing.
- Medium-term (90 days): Shortlist strategic partners from our supplier scorecards for co-development pilots in either advanced cooling (vapor chamber/liquid) or in localized extrusion capacity depending on your product mix and margin profile.
Final Note: Why This Report Matters for 2026 Strategy
With a projected market growth path from approximately 8.2 (USD Million) in 2025 to over 13.7 (USD Million) by 2032, and a 7.5% CAGR driving that expansion, heat sinks are no longer commoditized throwaways in the electronics bill-of-materials. They are increasingly a lever for product differentiation, supply-chain resilience, and margin expansion. Whether you are a supplier assessing where to invest in next-gen cooling technologies, an OEM reevaluating procurement strategy, or a PE firm sizing attractive consolidation targets, the structured, operational intelligence in our full report is designed to convert market insight into boardroom decisions.
Access the full Heat Sinks Market report to obtain the granular segment analytics, interactive forecasting model, supplier comparisons, and executable playbooks necessary to finalize 2026 plans. PW Consulting’s team stands ready to deploy a tailored workshop to translate these findings into a firm-specific strategy roadmap.
For detailed analysis of this topic, please visit the official page: Heat Sinks Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com