

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Smartphone Power Management ICs to Reach USD 267M by 2032 (5.5% CAGR)

Smartphone Power Management ICs Market: Strategic Preview for 2026 Decision-Makers
Executive teaser
As smartphones continue to pack more compute, radios and sensors into ever-tighter power envelopes, Power Management Integrated Circuits (PMICs) have moved from utility components to strategic enablers of device differentiation. PW Consulting’s new Smartphone Power Management ICs Market study (base year 2025) synthesizes historical performance, technology inflection points and forward-looking scenarios to inform boardroom and product-lead decisions in 2026. This preview demonstrates the kind of analytical depth and practical outputs included in the full study while intentionally reserving granular segment-level figures and proprietary model outputs for subscribers.
Smartphone Power Management Ics Market
Market snapshot: a compact macro picture
-
Historical momentum: the market has expanded from approximately USD 140 million in 2020 to USD 185.0 million in the base year 2025, reflecting the confluence of higher per-device PMIC complexity and greater unit volumes in select segments.
Smartphone Power Management Ics Market -
Near-term anchor for planning: our 2026 projection places the market around USD 196.46 million — a useful reference point for 2026 budgeting, supplier negotiations, and product roadmap prioritization.
Smartphone Power Management Ics Market -
Medium-term trajectory: PW Consulting’s forecast through 2032 projects a rise toward roughly USD 267.0 million, representing a compound annual growth rate (CAGR) of about 5.5% across the forecast window. That growth embeds scenarios for evolving fast-charging adoption, incremental PMIC functional integration, and the penetration of new handset form-factors.
-
Competitive structure: the market remains fragmented relative to mature semiconductor segments — the top-three vendors account for low double-digit share while the top-five remain well below one-third concentration. This dispersion presents both supplier risk and opportunity for challengers pursuing niche differentiation.
Why this study matters for 2026 strategic decisions
-
Linking device-level product decisions to supplier economics. By anchoring product roadmaps to PMIC cost and integration scenarios, OEMs can quantify trade-offs between discrete component approaches and integrated PMIC strategies — crucial when negotiating design wins in 2026 handset programs.
-
Prioritizing engineering investment. As energy efficiency and thermal management shift from component to system concerns, finance and engineering leaders must decide where to allocate R&D. The report maps roadmap options (e.g., buck-boost + power-path vs. distributed LDO-heavy designs) to measured market value outcomes.
-
M&A and partnership screening. For corporate development teams, a 5–7 year view of PMIC adjacencies highlights targets that best accelerate capability gaps (e.g., fast-charge IP, advanced battery management algorithms, mixed-signal integration).
-
Supply-chain and sourcing resilience. The combination of modest market concentration and diverse regional supply realities means procurement strategies in 2026 should blend single-sourcing for design continuity with dual-sourcing for risk mitigation — guided by our supplier risk matrix and scenario stress tests.
What the full report delivers — practical, implementable outputs
-
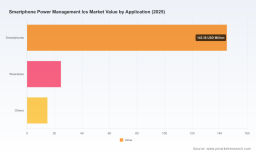
Transparent sizing and method: detailed market-sizing methodology, reconciled to device shipments, average selling prices, and BOM models used in the forecast. (Note: the public preview intentionally omits the detailed regional and application split tables.)
-
Technology deep dives: functional roadmaps and performance trade-offs across the primary PMIC classes (battery management ICs, regulators, multi-channel PMICs and other architectures), including thermal, layout and testing considerations for mobile OEMs.
-
Scenario-based forecasts: base, upside and downside scenarios incorporating factors such as accelerated fast-charge adoption, battery chemistry shifts, and component-level integration trends.
-
Go-to-market playbooks: tailored strategies for OEMs, IDMs, fabless suppliers and distributors — covering design-win tactics, pricing/licensing models, and after-sale software/firmware monetization for energy management.
-
Commercial tooling: downloadable BOM templates, supplier scorecards, and a sensitivity model that lets commercial teams quantify the impact of unit price, ASP erosion, and adoption curves on 2026–2028 P&L.
-
Competitive profiles and bench-tests: vendor feature matrices, strengths/weaknesses and comparative benchmark summaries for leading PMICs (power efficiency, quiescent current, thermal performance, integration level).
Competitive landscape: profiling incumbent and challenger strategies
The PMIC ecosystem for smartphones blends large analog-capable IDMs, SoC integrators and focused power specialists. Below we summarize strategic postures of principal players covered in the report; each profile contains a concise assessment of where that firm is likely to create or cede value in 2026.
-
Texas Instruments (Dallas, TX, https://www.ti.com) — Strengths in broad analog IP and multi-output PMIC families make TI a default partner for OEMs seeking mature solutions and strong supply continuity. Their legacy offerings coexist with newer, higher-integration parts aimed at established designs.
-
Analog Devices (Wilmington, MA, https://www.analog.com) — Positions around high-performance power-path management and fast-charge enablement. ADI’s value extends to applications that require tight analog control and high transient performance.
-
NXP Semiconductors (Eindhoven, https://www.nxp.com) — Leverages configurable sequencing and fault-protection IP tailored to application processors and memory rails, appealing to handset platforms emphasizing deterministic power-up and safety.
-
Renesas / Dialog (Tokyo, https://www.renesas.com) — A strong multi-channel and sub-PMIC supplier with capabilities in buck-boost topologies. Renesas’ play is to offer modular PMIC solutions that map easily to mid-to-high tier platforms.
-
ON Semiconductor (Phoenix, AZ, https://www.onsemi.com) — Focus on integration and efficiency for consumer electronics, making ON a reasonable partner where thermal and battery life optimization are prioritized.
-
Richtek Technology (New Taipei City, https://www.richtek.com) — A specialist in portable PMICs and buck-boost designs, often competing on price-performance and availability for high-volume handsets.
-
ROHM Semiconductor (Kyoto, https://www.rohm.com) — Offers a balanced portfolio of linear and switching regulators; attractive for display and mixed-power subsystems that require clean rails.
-
Skyworks Solutions (Irvine, CA, https://www.skyworksinc.com) — While best known for RF, Skyworks’ moves into power and power delivery aim to co-opt RF and PMIC synergies in advanced handset architectures.
-
Qualcomm Technologies (San Diego, https://www.qualcomm.com) — Integrates SoC power management with fast charging and platform-level power controllers; Qualcomm’s tight coupling of SoC and power management is a key differentiator in flagship devices.
-
MediaTek (New Taipei City, https://www.mediatek.com) — Builds PMICs matched to its SoC roadmaps, delivering cost-optimized multi-buck/LDO solutions that accelerate platform adoption in price-sensitive segments.
Strategic takeaways for 2026
-
Design-win timing matters: PMIC selection is a long-lead decision in handset design cycles. Teams that lock architecture and supplier choices early in 2026 capture the most leverage over cost and integration.
-
Invest in co-optimization: Significant gains accrue when firmware, battery algorithms and PMIC silicon are co-designed. Allocate a portion of 2026 R&D to system-level power profiling and adaptive charging features.
-
Prepare for heterogenous sourcing: Use quantitative supplier resilience scoring (provided in our report) to craft dual-sourcing strategies that reduce single-point-of-failure risk without sacrificing BOM economics.
-
Monetize beyond silicon: Consider software-enabled energy management features and subscription models tied to battery health — the hardware’s bill-of-materials may be modest, but the software premium can create recurring revenue.
-
Watch charging and battery tech: Fast-charging topologies, evolving battery chemistries and regulatory push on battery safety will reshape PMIC requirements; plan for incremental requalification cycles and certification budgets in 2026.
Closing and next steps
This preview demonstrates PW Consulting’s approach: rigorous macro sizing, scenario-based forecasting, and operationally focused recommendations. For executives preparing 2026 strategies, the study provides the analytical backbone to prioritize investments, choose partners, and define procurement and product-development playbooks.
To access the full report — including granular regional and application splits, the vendor market-share table, downloadable commercial tools, and our proprietary sensitivity model — please visit the report landing page. The detailed tables and spreadsheets are intentionally withheld from this overview to preserve the investigative value of the full subscription deliverable.
For detailed analysis of this topic, please visit the official page: Smartphone Power Management Ics Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com