

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Marine Audio Market to Grow at 5.8% CAGR, Reaching USD 200.1M by 2032

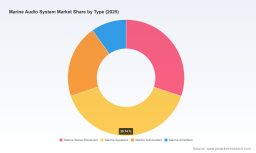
Marine Audio System Market — Strategic Preview for 2026 Decision Makers
PW Consulting’s latest Marine Audio System Market study is designed as an operational intelligence brief for executives, product leaders, and corporate development teams preparing strategic moves in 2026. This preview outlines the strategic returns you can extract from the full report, explains how macro dynamics will shape near-term choices, and highlights the competitive and regulatory pressures that will drive winners and laggards. We show the depth of our analysis while preserving the granular segment and regional tables to encourage direct access to the full dataset and interactive dashboards.
Marine Audio System Market
Why this study matters for 2026
-
Clear growth runway. The market has expanded steadily through the first half of the decade and, according to our base-year calibration (2025), is forecast to continue growing at a compound annual growth rate (CAGR) of 5.8% across the formal forecast window. That trajectory underscores expanding demand for marine-durable audio solutions and increasing content integration aboard recreational and commercial vessels.
Marine Audio System Market -
Timing-sensitive investment decisions. Suppliers and OEMs face a narrow window to align R&D, sourcing, and channel investments with product cycles and boatbuilder OEM specifications being finalized for 2026 model years. Our report converts growth projections into timing maps that show when to accelerate engineering spends, when to lock supplier contracts, and when to pressure-test pricing under different adoption scenarios.
Marine Audio System Market -
Strategic clarity for portfolio choices. Buyers evaluating product portfolios (e.g., premium integrated systems vs. commoditized aftermarket modules) need a data-driven basis for margin allocation, SKU rationalization, and platform investment. We translate top-line growth into prioritized roadmap recommendations and profitability breakeven analyses.
Macro snapshot (what we quantify and why it matters)
-
Historical base and forward view: our model reconciles historical sales trends (2020–2025) with bottom-up demand signals and supplier capacity mapping to produce a conservative-to-accelerated forecast for 2026–2032. For context: the market has shown consistent expansion through 2025 and—based on component lead times, boat production schedules, and aftermarket replacement cycles—our forecast projects material increases in installed bases toward 2032.
-
Concentration and competitive implications: industry concentration is modest. The combined market share of the three largest participants sits at a level that permits differentiated players to gain scale through engineered product advantages, channel partnerships, or contract manufacturing alliances. This creates space for both focused premium players and volume-oriented OEM/ODM specialists.
-
Capital and margin dynamics: we model component cost inflation (polymers, coatings, electronic components), regulatory compliance costs, and channel margins to forecast gross-to-net scenarios under multiple sourcing strategies. These outputs are directly actionable for procurement and pricing teams.
What the full report delivers (practical, executable content)
-
Market sizing and demand curves: a calibrated, bottom-up market model with yearly granularity (2020–2032), scenario toggles, and sensitivity analysis covering component cost shocks and adoption-rate variance.
-
Go-to-market playbooks: playbooks for OEM partnerships, dealer networks, and direct-to-consumer aftermarket channels—each with tactical KPIs and suggested commercial terms optimized for 2026 procurement cycles.
-
Technology and product roadmaps: comparative assessments of connectivity standards (including marine networking interoperability), DSP and A2B integration options, and modular architecture recommendations to shorten time-to-market while protecting IP.
-
Supplier and manufacturing strategy: supplier scorecards, risk matrices for raw-material exposure (rotomolded enclosures, UV-resistant polymers, corrosion-resistant metals), and cost-to-serve models for onshore vs. offshore manufacturing footprints.
-
Regulatory & compliance checklist: step-by-step requirements for marine durability certification and supply chain QA (including ISO quality frameworks and NMEA connectivity expectations) to reduce launch delays and retrofit costs.
-
M&A and partner screening toolkit: target prioritization framework that ranks acquisition or JV targets across strategic fit, manufacturing capability, channel access, and integration risk—designed for near-term roll-ups and bolt-on plays.
-
Interactive dashboards and executive summaries: downloadable slide sets and scenario simulators to run board-level discussions with finance and operations on the same data foundation.
Competitive landscape — how incumbents and specialists are positioning
The market is populated by a blend of premium audio specialists, marine-focused independents, and OEM/ODM producers. Below we summarize strategic postures and implications for 2026 planning.
-
Wet Sounds (Rosenberg, TX) — renowned for performance-focused marine speakers and tower systems engineered for harsh conditions. Their product-led reputation creates a reliable anchor for premium OEM programs; for competitors, Wet Sounds’ brand equity raises the bar on perceived value and shapes dealer expectations.
-
JL Audio (Miami, FL) — a premium audio leader with integrated system offers. Their focus on high-fidelity marine systems suggests sustained pressure on rivals to invest in acoustic engineering and integrated electronics or risk being relegated to lower-margin aftermarket segments.
-
Rockford Fosgate (Elkhart, IN) — broad portfolio spanning source units to power amplifiers with emphasis on marine-grade construction. Their scale advantages and distribution reach make them a logical partner for boatbuilders seeking single-vendor audio stacks.
-
Fusion / Garmin Fusion (Vancouver, WA) — drives differentiation via marine electronics integration (NMEA network compatibility). Their strength emphasizes the strategic importance of interoperability for OEM contracts and the premium commanded by integrated solutions.
-
Hertz Marine (Italy) — high-fidelity engineering focus. Recent product introductions at industry shows signal continued investment in DSP, digital networking (A2B), and modeling tools that shorten system tuning cycles—key for OEM co-development.
-
China Future Sound (Jiashan, Zhejiang) — an OEM/ODM specialist expanding bespoke production capabilities for Western distributors. Their evolution underscores the growing strategic choice between outsourcing to scale or investing in in-house manufacturing control to protect differentiators.
-
Kicker, BOSS, Poly-Planar, Maxxsonics — a mix of weather-proof consumer brands and marine specialists that collectively pressure price tiers and channel breadth. Their presence sustains a competitive aftermarket that requires clear value articulation from premium players.
Recent industry developments with strategic consequences
-
New premium outputs: notable product launches (DSP amplifiers with digital networking and fresh speaker lines) at recent industry events indicate that technical differentiation—especially digital audio networking, real-time loudspeaker modeling, and DSP—will be a key axis of competition into 2026 and beyond.
-
OEM sourcing shifts: recent publicized expansion of OEM/ODM capabilities by major contract manufacturers signals increased willingness among boatbuilders and distributors to push complex integration to third-party manufacturers—creating both opportunity and risk for branded vendors.
-
Standards and integration expectations: the market is converging on mandatory network compatibility and quality certification frameworks. Buyers should treat NMEA 2000 compatibility and ISO-aligned QA as minimum gate conditions for OEM tender participation in 2026.
-
Material and manufacturing pressures: specialized enclosures and UV/salt-resistant materials remain a cost driver. Procurement strategies that fail to account for rotomolding and advanced polymer lead times will face supply and margin pressure during peak boating seasons.
How to use this study for 2026 strategic plays
-
Product strategy: use our adoption curves and component cost models to set realistic R&D timelines for DSP-enabled systems and A2B networking—ensuring product readiness aligns with boat model production slots.
-
Sourcing & manufacturing: leverage supplier scorecards and risk matrices to decide which components to insource, which to dual-source, and where to negotiate long-term volume contracts to stabilize margins.
-
Commercial & channel decisions: apply our go-to-market playbooks to optimize SKU mix between OEM and aftermarket channels, design dealer incentive plans, and calibrate distributor discounts to protect margins while accelerating penetration.
-
M&A and partnerships: deploy the M&A toolkit to identify acquisition targets that accelerate capability in DSP engineering, marine-certified manufacturing, or direct boatbuilder relationships.
-
Regulatory readiness: follow the compliance checklist to avoid the most common launch delays tied to marine durability testing and integration with vessel electronics.
Next steps and how to access the full intelligence
This preview shows where the market is headed and what executives must do now to capture share, protect margin, and accelerate innovation. The full PW Consulting Marine Audio System Market report contains the proprietary segment-level dashboards, detailed regional and application breakouts, supplier-level cost models, and downloadable scenario tools that underpin the recommendations summarized here.
For teams making 2026 product, sourcing, or M&A decisions, the full dataset and scenario simulators are the only practical way to convert directional insights into executable plans. Contact PW Consulting to obtain the complete report, access interactive dashboards, and schedule a tailored briefing with our senior analysts.
For detailed analysis of this topic, please visit the official page: Marine Audio System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com