

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Magnetic Drill Press Market set to hit USD 1,053.5M by 2032 (6.2% CAGR)

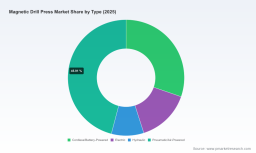
Magnetic Drill Press Market — Strategic Imperatives for 2026 Decision-Makers
Introduction
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present a high-fidelity briefing that situates the Magnetic Drill Press market in the context of near‑term strategic decision-making for 2026. This preview distills the research thrust of our full market study: macro growth trajectories, competitive dynamics, supply‑chain pressures, and pragmatic playbooks that executives, product leaders and investors must use to convert market movement into competitive advantage. To preserve the report’s commercial value, we foreground the analytical themes and strategic implications while intentionally withholding the full granular segmentation — those detailed data tables and model outputs are available in the complete report on our website.
Magnetic Drill Press Market
Executive snapshot — market trajectory and concentration
Between 2020 and 2025 the Magnetic Drill Press market demonstrated steady expansion, moving from institutional-scale beginnings to a broader mix of jobsite-mobile and industrial-grade demand. Our base‑year analysis (2025) anchors a forecast window covering 2026–2032 where the market grows at a compound annual growth rate (CAGR) of 6.2%. Under the baseline scenario this trajectory takes the market from mid‑2025 levels into a market exceeding one billion USD by the end of the forecast period.
Magnetic Drill Press Market
Concentration metrics confirm a moderately consolidated landscape: the top three firms control a material share of the market, and the top five widen that dominance further. This structure creates distinct strategic pathways for incumbents and challengers — from premium product differentiation to consolidation playbooks that target service and aftermarket capture.
Magnetic Drill Press Market
Why this matters for 2026 strategies
-
Demand composition is bifurcating: jobsite mobility and cordless solutions are rising in importance alongside enduring demand for heavy‑duty, industrial magnetic drill systems. The result is a market where product portfolios must span lightweight, battery‑optimized designs and robust, high‑torque systems for structural steel, maintenance and power‑generation segments.
-
Raw‑material and component volatility materially affects unit economics. Key inputs are under pressure: hot‑rolled coil steel moved higher in 2025 versus 2024, and scrap prices also tracked above long‑run averages. Meanwhile, magnet and motor inputs face supply‑side risk — rare earth prices grew substantially in the most recent year and copper has emerged as a critical mineral in regulatory frameworks. These trends create an environment in which design choices, supplier strategy and contract clauses (indexation, hedging) are central to margin defense.
-
Technology and service escalation: brushless motors, higher energy‑density battery systems, and modular low‑profile form factors are not mere product upgrades — they reshape total cost of ownership, operator productivity and adoption thresholds for rental and fleet models. Concurrently, digital after‑sales (remote diagnostics, consumable replenishment) is becoming a differentiator for premium OEMs.
-
Channel and go‑to‑market are evolving: professional contractors and fabricators increasingly expect integrated kits, annular cutter ecosystems and bundled service warranties. Rental companies and distributors are wielding outsized influence on spec behavior, effectively acting as latent OEM extension arms.
Competitive landscape — who matters and why
The competitive field blends long‑tenured niche manufacturers with large tool OEMs that leverage scale and distribution. Below I summarize strategic positioning of core players covered in our research (company summaries emphasize market role rather than disclosing proprietary segment revenue):
-
Hougen Manufacturing (Swartz Creek, MI) — Deep niche expertise in magnetic drills for structural fabrication. Their focused product line and fabricator kits make them a go‑to for heavy structural work and specialized cutter compatibility.
-
DEWALT (Baltimore, MD) — A scaled global power‑tool leader that has extended cordless and corded magnetic drills into its jobsite ecosystem. Their strength lies in channel reach and battery‑platform synergies.
-
Milwaukee Tool (Brookfield, WI) — Leverages its high‑torque 18V platform and fleet purchasing relationships. Positioning is premium professional, with emphasis on torque, run time and system connectivity.
-
CS Unitec (Norwalk, CT) — Focuses on portable industrial systems and specialized applications including underwater and heavy maintenance, where reliability and serviceability are paramount.
-
BDS Maschinen GmbH (Mönchengladbach, Germany) — European premium manufacturer with broad model coverage supporting twist, core drilling and tapping for industrial shops and precision work.
-
Champion Cutting Tool (Warren, OH) — Competes on low‑profile, lightweight designs that address tight‑space structural work — a clear advantage in retrofit and bridge‑work applications.
-
Evolution Power Tools (Coventry, UK) — Specializes in portable systems for framework and bridge work, emphasizing mechanical simplicity and field robustness.
-
Euroboor USA (Houston, TX) — Strong in the service and maintenance segment with quality certification pedigree supporting industrial procurement.
-
WEISS MACHINERY (Nanjing, China) — Differentiates via integration with CNC and lathe platforms for oil, gas and power generation applications — a pathway into industrial automation suites.
Strategically, incumbents with broad product ecosystems and distribution scale enjoy defensible positions, while smaller specialists exploit design agility and application depth. Our full report maps these firms across dimensions of product breadth, aftermarket strength, channel reach and technology roadmaps.
Recent market signals and tactical implications
-
New product introductions and promotions in early 2026 indicate continued race for jobsite share: entrants are emphasizing switchable magnets, compact 25–30 mm capacity units for confined work, and cordless upgrades with brushless motors. This signals rising competition on both performance‑per‑weight and battery run‑time metrics.
-
Promotional activity by established tool brands shows continued prioritization of system sales — battery platforms and accessory kits are being used to lock in channel loyalty and recurring consumable demand.
-
Supply‑side noise — rising steel and scrap prices, rare‑earth inflation, and the regulatory elevation of copper — amplifies the importance of design‑for‑material‑efficiency, supplier diversity, and contractual price‑protection mechanisms.
What the PW Consulting report delivers (practical components)
Our full study is built for deployable decisions. Key deliverables include:
- Validated market sizing and trend decomposition (historical 2020–2025; forecast 2026–2032) with scenario stress tests around commodity and policy shocks.
- Competitive heat maps and capability matrices that rank incumbents and challengers on product breadth, aftermarket reach, technology adoption and channel strength.
- Actionable go‑to‑market playbooks for three archetypal players — scale OEM, specialist challenger and private‑equity portfolio company — including pricing tactics, channel incentive models and partnership frameworks.
- Commercial models and Excel‑based sensitivity tools to simulate margin impact under alternative raw‑material, currency and battery cost scenarios.
- M&A target screening criteria and due‑diligence checklists focused on asset tangibility (IP, tooling, distribution) and recurring revenue from consumables and service.
- Procurement and supplier‑risk frameworks to operationalize hedging, dual‑sourcing and nearshoring decisions.
To respect the “preview” nature of this note, we have deliberately withheld the granular regional and application splits that underpin our models; these are available in full to report subscribers.
Strategic recommendations for executives in 2026
-
Prioritize product‑platform versatility. Invest in battery‑compatible variants and modular carcasses that share common motor and electronics across cordless and corded SKUs to compress R&D and simplify aftermarket logistics.
-
Lock in consumable ecosystems. Annular cutter compatibility and blade/cutter subscription models raise switching costs and create annuity streams — align marketing, warranty and training to maximize aftermarket attachment rates.
-
Hedge material exposure. Develop procurement playbooks that combine contracted volumes with financial hedging where available, and evaluate local sourcing for magnet and copper subassemblies to mitigate supply‑chain and regulatory risks.
-
Use rental and fleet partnerships to accelerate adoption. For heavier or capital‑intensive equipment, rentals lower buyer friction and provide real‑world performance data to inform design iteration.
-
Scan for consolidation opportunities focused on complementary service networks and high‑margin consumable portfolios. Given the market’s concentrated nature, tuck‑ins that extend aftermarket reach can be value‑accretive.
-
Embed digital services early. Remote diagnostics, simple usage telemetry and consumable replenishment drive lifetime value and can justify premium pricing while reducing service cost through predictive maintenance.
Scenario framing — what to monitor in 2026
Our baseline assumes continued 6.2% CAGR through 2032, but strategic plans must remain agile around three key levers: commodity inflation (steel, rare earths, copper), infrastructure stimulus and workforce trends that affect on‑site labor intensity and tool substitution. Each lever has asymmetric impacts across cordless vs. industrial segments; the report provides calibrated scenario matrices and break‑even analyses so leaders can set trigger points for investment and M&A.
Next steps
This briefing outlines the strategic inflection points that will define winners and laggards in the Magnetic Drill Press market through the end of the decade. For teams preparing 2026 budgets, product roadmaps or acquisition screens, our complete study supplies the full segmented tables, model spreadsheets and prioritized initiative trackers required to operationalize these insights. Contact PW Consulting or visit our report page to access the detailed dataset, bespoke modeling tools and a roadmap workshop with our strategy team.
For detailed analysis of this topic, please visit the official page: Magnetic Drill Press Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com