

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Non-PVC IV Bag Market poised to reach USD 291.51 Million by 2032

Non-PVC IV Bag Market — Strategic Briefing for 2026 Decisions
Executive snapshot
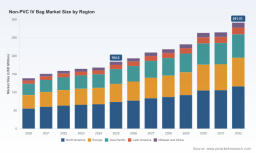
As healthcare procurement and regulatory landscapes tighten around phthalates and PVC, non-PVC intravenous (IV) bags have moved from a niche compliance play to a strategic supply-line and product-differentiation opportunity. PW Consulting’s new market research, benchmarked to a 2025 base year, shows the global non-PVC IV bag market has expanded materially over the past half decade and is expected to continue growing at a mid-single-digit compound annual growth rate (CAGR) through the early 2030s. For executives planning 2026 product investments, capacity allocation, or M&A activity, the data and strategic frameworks in this briefing map where risk is concentrated, where first-mover advantages persist, and what operational moves unlock durable share gains.
Non-PVC IV Bag Market
Market snapshot — macro numbers that matter to strategy
Key high-level metrics you should carry into boardroom discussions: the market reached a clear inflection by the 2025 base year, reflecting sustained adoption of polyolefin-, polyester- and EVA-based solutions across clinical settings, and the model projects continued expansion through the forecast window to 2032. The forecasted trajectory — driven by regulatory tailwinds, drug shortage mitigation programs, and hospital procurement preferences — creates a multi-year runway for targeted investments in manufacturing, quality systems, and clinical validation.
Non-PVC IV Bag Market
Why 2026 is a pivot year
-
Regulatory acceleration. Jurisdictions and hospital systems are formalizing DEHP/PVC restrictions and notification requirements, raising the compliance bar for legacy PVC suppliers and creating procurement incentives for DEHP-free alternatives.
Non-PVC IV Bag Market -
Supply continuity is now strategic. Public health authorities have used non-PVC imports in shortage responses, demonstrating that non-PVC bags are not just safer from a toxicology standpoint but are operationally integral to national resilience planning.
-
Product breadth and differentiation. Several incumbent device and materials firms are commercializing full non-PVC portfolios (including multi-chamber and ready-to-use formulations), altering the competitive calculus and contracts required to win large institutional tenders.
Competitive dynamics — what leading players reveal about the market
The competitive landscape combines global medical device leaders with specialized materials and contract-manufacturing players. Several themes emerge from recent corporate activity and product launches:
-
Baxter continues to leverage branded non-PVC platforms to support hospital shortage-response programs and to position its IVINA large-volume bags as alternatives in national contingency plans.
-
B. Braun has advanced regulatory clearances and product launches for multi-compartment and DEHP-free systems, demonstrating an aggressive route-to-market for hospital formularies seeking compliant, convenient therapeutic options.
-
ICU Medical’s recent joint-venture activity emphasizes capacity and regional supply security — a signal that vertical integration and co-manufacturing will be decisive for near-term supply contracts.
-
Specialist producers and material innovators (including firms focused on PP-based films, polyolefin extrusion, and elastomeric modifications) are carving downstream value by providing qualified materials and multi-chamber capabilities required by OEMs.
-
New manufacturing footprints in non-traditional geographies are enabling regional procurement strategies that prioritize shorter lead times and regulatory alignment with local health authorities.
Recent developments shaping short-term opportunities
-
Regulatory clearances and product launches by major suppliers have de-risked several high-volume therapeutic formats previously dominated by PVC-based solutions.
-
Collaborations and joint ventures in 2024–2025 signal that volume scale and supply security are now strategic assets — not merely operational considerations — for winning national tenders and hospital system contracts.
-
Authorities have explicitly used non-PVC products in shortage mitigation efforts, validating non-PVC bags within critical-care supply chain planning.
Supply chain and materials outlook
Material selection (polyolefin, polyester, EVA and other polymer blends) drives regulatory acceptance, manufacturing process design, and long-term cost. Suppliers that can demonstrate compliant, scalable film extrusion and aseptic assembly capture a premium in procurement evaluations. For 2026 planning, three supply-side realities matter:
-
Cost and availability of qualified polymer films will be the principal driver of gross margins and unit economics for new non-PVC lines; hedging and long-term supplier agreements reduce downside risk.
-
Qualification timelines for new materials remain non-trivial — robust validation, extractables/leachables testing and regulatory submissions delay time-to-revenue but create defensible barriers to entry once complete.
-
Manufacturing flexibility — the ability to switch between single- and multi-chamber formats, and to accommodate different fill volumes and closure systems — materially improves tender competitiveness.
Strategic implications — what to do in 2026
Below are prioritized, actionable moves for executives weighing investments this year. Each recommendation is calibrated to capture demand upside while limiting exposure to regulatory and supply volatility.
-
Prioritize regulatory-first product roadmaps. Treat DEHP/PVC exclusion as a product requirement, not a feature. Accelerate extractables/leachables programs and secure pathway alignment with major regulators to shorten hospital adoption cycles.
-
Lock supply with strategic partnerships. Negotiate long-term agreements with polymer film suppliers and consider capacity co-investments or tolling arrangements to guarantee throughput for multi-year tenders.
-
Invest in modular production. Deploy flexible aseptic lines capable of rapid format changeover (single vs. multi-chamber) to capture both emergency supply contracts and routine procurement channels.
-
Targeted M&A and JV playbooks. Pursue tuck-in acquisitions that add materials qualification, sterile filling capacity, or geographic regulatory approvals — prefer assets that shorten time-to-market rather than broad greenfield investments unless scale justifies.
-
Design hospital engagement pilots that demonstrate operational benefits. Partner early with health systems on clinical and workflow pilots (e.g., ready-to-administer medications, reduced contamination risk) to secure formulary positioning.
-
Embed sustainability and traceability as commercial differentiators. Third-party sustainability credentials and tamper-evident traceability will influence procurement decisions as sustainability reporting becomes part of hospital supplier evaluation.
-
Model contingencies into pricing. Build scenarios that reflect raw material shocks and regulatory changes, ensuring tender prices maintain margin headroom under adverse inputs.
What PW Consulting’s full report delivers (practical tools)
This briefing is an orientation. The full PW Consulting market study provides the granular, operational intelligence needed to execute the recommendations above — while protecting the proprietary market segmentation logic. Key deliverables include:
-
An integrated market model (historical 2020–2025; forecast 2026–2032) with scenario toggles for regulatory acceleration, supply shocks, and adoption curves.
-
Detailed competitor dossiers: product portfolios, regulatory status, recent investments, and decision matrices to prioritize partnership or M&A targets.
-
Supply chain maps and a polymer-sourcing playbook: validated supplier lists, qualification timelines, and cost-sensitivity analyses.
-
Regulatory and reimbursement matrix: jurisdiction-by-jurisdiction guidance for labelling, DEHP discourse, and procurement notification rules.
-
Commercial playbooks and tender-response templates for hospital systems and national buyers, including clinical evidence checklists and ROI calculators.
-
Primary interview transcripts and methodology annex — enabling traceable assumptions for CFO-level investment decisions.
Closing — how to use this briefing in your 2026 planning
For procurement leaders, this market is now a line-item in resilience plans. For product and business development teams, 2026 is the year to convert regulatory momentum into commercial traction. For corporate development, the most valuable assets will be those that shorten validation timelines, secure polymer supply, and deliver sterile fill capacity close to large institutional buyers.
PW Consulting’s complete study contains the confidential, granular splits and vendor scorecards required to prioritize projects and justify capital deployment. Use this briefing to align stakeholders on the strategic stakes; obtain the full report to execute with certainty.
For detailed analysis of this topic, please visit the official page: Non-PVC IV Bag Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com