

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: MIM Furnace Market to Hit USD 302.1 Million by 2032 at 6.7% CAGR

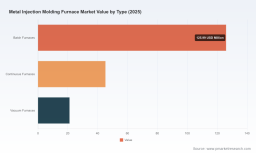
Metal Injection Molding Furnace Market: Strategic Briefing for 2026 Decisions
As lead industry analysts at PW Consulting, our latest Metal Injection Molding (MIM) Furnace Market study is designed to be the operative intelligence package decision-makers will consult as they set capital budgets, sourcing strategies, and product roadmaps for 2026. Built on a 2025 base year and a 2026–2032 forecast horizon, the study synthesizes historical performance (2020–2025) and projects forward under multiple macro and micro scenarios. At the topline, the market has grown steadily from 2020 through 2025 and is projected to expand at a compound annual growth rate of 6.7% over the forecast window—an expansion trajectory that materially alters investment timing and technology selection calculus for furnace OEMs, captive MIM producers, and their supply-chain partners.
Metal Injection Molding Furnace Market
Why this study matters in 2026
-
Capital allocation: With the market demonstrating multi-year growth and predictable momentum into the early 2030s, 2026 is a pivotal year for committing to multi‑million-dollar furnace projects or choosing modular, upgradeable solutions that protect against rapid technical change.
Metal Injection Molding Furnace Market -
Technology competitiveness: Material standards and process advances are compressing time-to-market for high-value MIM applications (notably aerospace and medical). Furnace selection now determines whether a MIM producer competes on cost, capability, or both.
Metal Injection Molding Furnace Market -
Regulatory and trade risk: Tariff policies and defense contracting clauses are reshaping sourcing economics and supplier qualifications—factors that should be embedded into procurement and contractual planning for 2026 purchases.
Market trajectory: what the numbers imply
Our modeling captures the market’s measured recovery and subsequent acceleration. The MIM furnace market’s total revenue base has moved upward over the 2020–2025 historical window and continues to expand in our baseline forecast through 2032. That steady growth, underpinned by a 6.7% CAGR in the forecast period, implies expanding installed bases, rising aftermarket service demand, and clear economics for both incremental capacity additions and higher‑margin, application‑specific furnace platforms. For boards and executive teams, the implication is straightforward: deferment of modernization projects risks higher unit costs and missed technical opportunities; conversely, well-timed investments can capture disproportionate share in fast-adopting subsegments.
Dynamics shaping the market in 2026
-
Standards-driven material adoption: The March 2025 update to MPIF Standard 35 introduced new material definitions and performance expectations for several titanium and stainless systems. This has immediate implications for furnace design (temperature profiles, atmosphere control, and contamination mitigation) and for qualification timelines in regulated industries.
-
Process innovation: Suppliers are advancing one-step debinding/sintering cycles, catalytic debinding options, and higher‑temperature vacuum capabilities. These process innovations shorten cycle times and broaden feasible material sets—favoring furnaces that can be configured for hybrid cycles and precise atmosphere management.
-
Atmosphere and safety: Hydrogen-bearing processes and high-temperature vacuum sintering are increasing in prevalence for high-performance parts. Equipment that integrates safe hydrogen handling, robust seals, and low‑leakage vacuum chambers becomes a purchasing differentiator.
-
Event and network effects: Industry exhibitions and technical congresses (notably the Euro PM series) are concentrating innovation, forging supplier-buyer linkages, and accelerating standards harmonization. Participation in these venues is an effective leeway to validate supplier claims and shorten qualification cycles.
-
Trade and procurement friction: Trade measures and defense-related procurement clauses are complicating global sourcing strategies. Organizations must now weigh nearshoring, dual sourcing, and supplier risk profiles into capital and service contracts.
Competitive landscape — reading the field
The competitive set is a mix of established industrial furnace manufacturers and specialists focused on MIM process requirements. Market concentration metrics show a fragmented industry structure, indicating considerable opportunity for niche leadership and selective consolidation. For procurement and corporate development teams, this fragmentation means multiple viable strategic paths: partner with a specialist, standardize on an OEM platform, or vertically integrate select capabilities.
-
Elnik Systems, LLC (Pineville, NC) has emphasized process integration with solutions that combine debinding and sintering cycles—an attractive value proposition for producers seeking reduced footprint and simplified material handling.
-
Nabertherm GmbH (Germany) offers matched furnace families for debinding and sintering, with thermal and catalytic options—positioning itself for customers that value seamless transfer and tight thermal control.
-
CARBOLITE GERO (Germany) builds application-specific equipment—catering to the segment that prioritizes validated, repeatable process windows for demanding alloy systems.
-
CM Furnaces Inc. (Bloomfield, NJ) focuses on continuous and batch systems optimized for MIM with hydrogen atmosphere handling—appealing to high-throughput operations.
-
TAV Vacuum Furnaces S.p.A. (Italy) and Seco/Warwick Group (Poland) bring vacuum expertise and custom solutions that are increasingly used for aerospace- and medical-grade MIM components where atmosphere purity and high temperature ceilings are decisive.
Recent vendor and industry developments reflect these trends: a leading standards update in early 2025, delivery of custom vacuum equipment for aerospace applications in 2025, and the release of a major technical programme for a 2026 metallurgy congress. Each of these events tightens the link between equipment capability and product qualification timelines—heightening the strategic value of early supplier engagement.
What the PW Consulting study contains (practical, executable elements)
-
Topline market sizing and growth model calibrated to 2025 base-year metrics and projected through 2032, with scenario variants to stress-test demand under differing macro, regulatory, and technology adoption paths.
-
Technology and process taxonomy—detailed descriptions of furnace architectures, atmosphere strategies, and process flows (debinding, pre-sinter, sinter, HIP) with vendor-agnostic design checklists that engineering teams can use during specification.
-
Buyer’s guide and procurement playbook—total cost of ownership templates, qualification milestones, service and spares planning, and contracting clauses that mitigate tariffs and defense-related procurement risks.
-
Competitive positioning maps and vendor capability briefings—comparative strengths, go-to-market focus, and likely roadmaps for OEM partners and acquisition targets (note: granular vendor ranking tables and segment-level revenue breakdowns are reserved for the full report).
-
Strategic scenarios—capex timing matrices and ROI sensitivity analyses that let CFOs test greenfield vs retrofit investments under the market’s 6.7% CAGR baseline and two alternate growth scenarios.
-
M&A and partnership playbook—criteria for target screening, integration checklists, and valuations drivers specific to furnace makers and system integrators in the MIM ecosystem.
Actionable recommendations for 2026
-
Prioritize flexibility: Procure furnace platforms that can be retrofitted for catalytic debinding and/or vacuum sintering to protect against shifting material demands.
-
Embed standards compliance early: Align equipment specs with the 2025 MPIF Standard 35 updates to shorten product qualification cycles in regulated markets.
-
Design for hydrogen safety: If targeting advanced stainless or titanium MIM alloys, incorporate hydrogen atmosphere capabilities and related safety systems into purchase specifications.
-
Hedge supply-chain risk: Build dual sourcing or near‑shore options into supplier strategies to mitigate tariff and defense procurement shocks.
-
Use events to accelerate learning: Deploy product validation pilots at industry congresses and leverage those venues to accelerate supplier audits and co-development agreements.
-
Evaluate tuck‑in M&A: Given the fragmented market structure, small acquisitions can rapidly fill capability gaps—particularly in atmosphere control, automation, or aftermarket service networks.
How to use this briefing with your 2026 planning cycle
For CFOs: integrate the forecast trajectory and scenario TCOs into three‑ and five‑year capex plans—align financing to modular upgrade paths rather than single large monolithic buys.
For CTOs: use the process taxonomy and vendor-agnostic checklists in the report to set minimum acceptable control tolerances, atmosphere management requirements, and qualification milestones tied to material standards.
For Business Development and Supply Chain leaders: prioritize supplier audits and contractual protections against tariff volatility; use the competitive mapping to identify partner candidates and to benchmark service level agreements.
Next steps
This briefing outlines the strategic implications and high-level intelligence from our Metal Injection Molding Furnace Market study. The full PW Consulting report delivers the granular models, vendor benchmarking, and segment-level analysis required to execute procurement, product, and M&A decisions in 2026. For teams preparing capital submissions or strategic roadmaps, access to the full dataset and appendices is essential—our full report contains the detailed segmentations, heatmaps, and supplier scorecards referenced here (these detailed tables are intentionally excluded from this preview to protect proprietary analyses and to ensure sourcing of the complete report via our distribution channel).
Contact PW Consulting to arrange a tailored briefing, request the underlying financial model, or commission a bespoke scenario analysis aligned with your 2026 planning priorities.
For detailed analysis of this topic, please visit the official page: Metal Injection Molding Furnace Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com