

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Asia Pacific Leads Baby Bottles Market with USD 1,105.8M; 5.32% CAGR to 2032

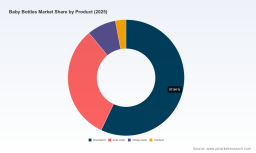
Baby Bottles Market — 2026 Strategic Preview
Executive summary
As PW Consulting’s lead industry analyst, I present a strategic preview of our comprehensive Baby Bottles Market study — a decision-focused briefing designed for executives planning actions in 2026. The baby bottles market is in structural growth: after recovering from pandemic-year volatility, global revenues reached an estimated USD 2,760 Million in the base year (2025) and, under our central forecast, will expand to roughly USD 3,938 Million by 2032 at a compound annual growth rate (CAGR) of 5.32% across the 2026–2032 forecast window. Market concentration is moderate and rising: the top three players account for nearly half of the market, and the top five control just over half, creating a landscape where scale, trusted safety credentials, and channel reach remain decisive.
Baby Bottles Market
Why this report matters for 2026 decision cycles
-
Timing: 2026 is a pivot year as industry players recalibrate after a series of product recalls, new safety standards and material innovations. Tactical responses in the next 6–12 months will determine competitive positions across 2026–2028.
Baby Bottles Market -
Regulatory risk is front-and-center. Recent recall and ban actions (domestic recalls and new national prohibitions) have shifted buyer sensitivity and retailer acceptance thresholds. Companies that move fastest to prove compliance will convert regulatory scrutiny into competitive advantage.
Baby Bottles Market -
Profitability inflection: steady demand growth combined with premiumization trends (anti-colic, performance materials, sustainability) opens margin opportunities for differentiated players; conversely, commoditized suppliers face margin compression unless they pursue scale or vertical integration.
Key market dynamics and actionable implications
-
Safety and certification as market currency. High-profile safety events in 2022–2026 have raised the bar for product certification. Expect buyers (retailers, e-commerce platforms, healthcare purchasers) to require third-party test documentation and clearer traceability. Action: establish a certification playbook (testing partners, labeling claims, audit cadence) and accelerate compliance proofs into product listings.
-
Material and design innovation are demand multipliers. Advances in thermoplastics, borosilicate glass substitutes and silicone formulations have created distinct value propositions around durability, weight, and perceived safety. Action: prioritize a two-track R&D cadence — quick-to-market material swaps for existing SKUs and a longer horizon program for next-generation materials tied to sustainability credentials.
-
Channel bifurcation — premium specialty vs. mass convenience. Premium brand strategies (design-led, certification-backed) thrive in specialty and online mono-brand channels; legacy mass brands continue to dominate big-box and value segments. Action: adopt differentiated go-to-market plays: premium SKUs for direct and specialist channels; value-engineered assortments for mass distribution with tailored logistics and packaging.
-
Supply chain concentration and input risks. Raw material costs and single-source components for vent systems and valves are potential pinch points. Action: map critical components, qualify second-source suppliers, and model cost pass-through scenarios into 2027 pricing plans.
-
Consumer education converts into premium adoption. Parents increasingly purchase based on clinical claims (anti-colic efficacy, nipple ergonomics) and sustainability narratives. Action: invest in clinician-facing evidence and scalable consumer education (short clinical summaries, demo videos, retail training kits).
Competitive landscape — how to read the field in 2026
The market is populated by a mix of global household brands, specialist premium challengers and agile regional manufacturers. Key incumbents we profile include established names with differentiated venting technologies and clinical positioning, premium design-led brands from Europe, hospital-trusted suppliers from Germany and Japan, and rapidly scaling Chinese players focused on certified performance at competitive prices.
-
Large multi-market incumbents maintain advantage through scale, channel partnerships and trademarked venting systems — their challenge is to maintain trust after episodic product safety events.
-
Premium European and Scandinavian brands trade on design, materials and boutique distribution; they can expand selectively by licensing clinical data or co-branding with pediatric networks.
-
US-based specialists with clinical vent systems compete on proven outcomes; their defensibility depends on clinical publications and IP protection for internal vent architectures.
-
Emerging Asia-based players are accelerating through certifications and strategic material partnerships — they aim to combine lower-cost manufacturing with validated safety claims, presenting an attractive alternative for private label and regional retail partners.
Recent developments to watch
-
Major recall event in mid-2026 focused attention on product sheathing and choking risks; retailers tightened marketplace acceptance rules and two-tier listing requirements emerged.
-
New product launches from certified challengers introducing clinically validated vent designs have demonstrated measurable reductions in spit-up and colic symptoms in controlled testing, shifting the conversation from feature to evidence.
-
Manufacturers are securing high-performance thermoplastic supply agreements and third-party testing reports, accelerating product rollouts with improved durability claims.
-
Historical recalls dating back to 2022 remain important memory markers influencing procurement policies and consumer trust; firms with fast, transparent remediation narratives restored placement faster than those that delayed.
What the PW Consulting report contains — practical, decision-ready modules
Our full study is organized to support corporate strategy, product development, commercial planning and M&A diligence. Highlights include:
-
Market sizing and trend analytics: rigorous historical series (2020–2025) and granular forecast modeling through 2032, incorporating demand drivers, material substitutions and regulatory scenarios.
-
Segmentation frameworks: multiple views by product design, material and channel, with scenario sensitivity (price, material cost shocks, certification hurdles). Note: the preview intentionally omits our full segment-level allocations — these are proprietary and provided in the full report to subscribers.
-
Price and margin benchmarking: SKU-level price ladders, bill-of-materials cost models and margin impact simulations under alternative sourcing strategies.
-
Go-to-market playbooks: tailored strategies for premium, mass-market and private-label players, including channel mix optimization, promotional calendars and digital conversion tactics.
-
Regulatory and safety matrix: a prioritized checklist of certifications, testing protocols and labeling requirements across principal markets along with templated risk remediation roadmaps.
-
Competitive deep dives: company profiles, recent product actions, patent and IP posture, and challenger opportunity maps for M&A and partnership scouting.
-
Executive decision tools: dashboard-ready KPIs, an M&A target short-listing methodology, and a 100-day integration/action plan for post-deal value capture.
Strategic plays for 2026 — where to allocate focus and capital
-
Fast compliance and transparency program. Investment in third-party testing, traceability and consumer-facing proof points is a high-return defensive play to stabilize listings and retain wholesale partners.
-
Premiumization with evidence. Prioritize a small portfolio of clinically substantiated premium SKUs and back them with clinician outreach and retailer exclusives.
-
Value engineering for mass channels. Re-design bill-of-materials for high-volume SKUs to protect margin if raw material prices rise or if private label pressure increases.
-
M&A and partnerships. Target acquisition of niche vent-system IP, or clinical research shops that can shorten time-to-evidence for anti-colic claims.
-
Sustainability and lifecycle narratives. Consumers reward perceived lower-waste solutions; consider material take-back pilots and recyclable packaging to win shelf differentiation.
How executive teams should use this intelligence
The full PW Consulting deliverable is structured to convert insight into action. Use it to:
-
Inform the 2026 product roadmap: prioritize SKUs by margin impact and regulatory readiness.
-
Design channel-specific promotion calendars based on forecasted demand elasticities.
-
Run M&A diligence faster: our shortlists and value-capture templates reduce screening time and improve integration outcomes.
-
Stress-test procurement and pricing strategies: deploy our cost-shock scenarios to set hedging policies and supplier contracts.
Next steps — access and deployment
This preview is intended as a strategic trailer: it highlights the depth and practical orientation of our research while reserving the granular segment allocations and proprietary datasets for the full report. Subscribers receive detailed spreadsheets, scenario engines and custom briefings tailored to board-level decision cycles. Given the medium-term market momentum (5.32% CAGR across the forecast window) and the heightened regulatory environment, firms that adopt a structured, evidence-first approach in 2026 will secure outsized commercial returns.
To obtain the complete dataset, segment-level forecasts, and the operational playbooks referenced above, visit our report page or contact PW Consulting for a tailored briefing and a deployment roadmap. Our team is prepared to deliver executive summaries, investor decks, and rapid-response advisory support for acquisition or product remediation scenarios.
For detailed analysis of this topic, please visit the official page: Baby Bottles Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com