

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Automatic Tire Inflation Market to Reach USD 344.8 Million by 2032 at 6.98% CAGR — PW Consulting

Automatic Tire Inflation System Market: Strategic Imperatives for 2026
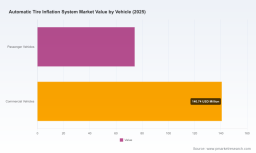
The Automatic Tire Inflation System (ATIS) market is entering a phase of sustained, measurable expansion that will shape procurement, engineering, and M&A agendas across fleets, OEMs, and Tier‑1 suppliers in 2026. Our PW Consulting market study — built on a 2025 base year and a robust historical series (2020–2025) — projects the global market to grow at a compound annual growth rate (CAGR) of approximately 6.98% over the 2026–2032 forecast window. To put this trajectory into context: the market expanded from roughly USD 163 million in 2020 to about USD 215 million in 2025 and is modeled to rise toward the mid‑hundreds of millions by 2032. This growth is neither speculative nor monolithic; it is driven by a convergence of operational economics, regulatory nuance, and rapid technology integration.
Automatic Tire Inflation System Market
Why this report matters to 2026 decision-makers
-
Actionable allocation: For capital planners and procurement leads, the report translates macro growth into investable themes — where to prioritize retrofit programs, which OEM partnerships to pursue, and how to size pilot investments with measurable payback windows.
Automatic Tire Inflation System Market -
Competitive intelligence: For corporate strategy and business development teams, the analysis isolates supplier strengths, capability gaps, and probable consolidation vectors across the value chain without divulging client‑level proprietary data.
Automatic Tire Inflation System Market -
Risk‑informed compliance: For safety, compliance, and regulatory affairs functions, the study synthesizes inspection guidance and equipment classification trends so you can anticipate enforcement risk and design compliant integration strategies.
-
Product roadmap calibration: For R&D and product management, the research spotlights technology inflection points — sensor fusion, telematics convergence, per‑tire control prototypes — enabling closer alignment of roadmaps to buyer willingness‑to‑pay.
What the PW Consulting study delivers (high‑utility contents)
-
Transparent market sizing and growth model: A clear, audit‑ready top‑down and bottom‑up methodology anchored to the 2025 base year, with scenario variants and sensitivity testing for fuel price, OEM penetration, and aftermarket retrofit adoption.
-
Go‑to‑market playbooks: Actionable frameworks for fleets, OEMs, and service networks that prioritize pilot design, measurement KPIs, and commercial terms that accelerate adoption while protecting margins.
-
Deal and partner scorecards: Investment and partnership-ready profiles of incumbent suppliers, adjacent technology entrants, and emerging innovators — including capability maps, integration risk matrices, and likely M&A targets.
-
Commercial models and ROI calculators: Standardized templates that translate tire pressure management into lifecycle cost savings, tire life extension, fuel economy gains, and downtime reduction for different fleet archetypes.
-
Regulatory impact assessment and mitigation planning: Practical guides for navigating inspection regimes, EMC compliance, and local homologation pathways across major markets.
-
Supply chain and component analysis: Insight into critical inputs (sensors, valves, seals, control modules), single‑point risks, and near‑term innovation (e.g., self‑adjusting seals that improve seal life under varied terrain).
Market dynamics driving the 2026 agenda
-
Operational economics: Fleets continue to demand technologies that deliver predictable TCO reductions. ATIS value propositions — reduced tire wear, extended tread life, improved fuel economy, and fewer roadside incidents — remain the primary adoption rationale. Our models explicitly quantify these drivers under variable fuel and tire cost scenarios to help investment committees prioritize pilots.
-
Technology convergence: The fusion of high‑reliability pressure sensors, low‑power telematics, and cloud analytics is shifting ATIS from a safety adjunct to an asset optimization platform. Expect integrators to increasingly bundle ATIS telemetry into fleet management systems rather than selling standalone mechanical kits.
-
Product differentiation: Two broad technical approaches coexist and compete — centralized systems that manage multiple axles collectively and continuous/per‑tire approaches that enable finer per‑tire control. Each has distinct engineering tradeoffs and value capture profiles; choosing among them is a strategic decision for OEMs and fleets based on mission profile and total cost imperatives.
-
Regulatory noise versus clarity: Inspection guidance in several jurisdictions clarifies that ATIS is generally not mandatory equipment, and defective systems may not automatically trigger violations. That nuance reduces regulatory compulsion as a growth lever and increases the importance of demonstrating direct fleet-level ROI to drive voluntary adoption. At the same time, industry conformity to EMC and environmental standards remains critical for cross‑market interoperability.
-
Component innovation and supply risk: Incremental improvements in sealing and valve technology — for example, adaptive seals that perform across diverse terrains — are increasing system reliability and lifetime value. Procurement teams must balance supplier concentration risks and the lead times of specialty components when structuring contracts.
Competitive landscape — who to watch and why
The market exhibits moderate concentration: the top three suppliers account for roughly a third of market value, while the top five approach just under forty percent. That profile points to an open competitive environment with room for specialist challengers and strategic consolidation.
-
Aperia Technologies (United States) — Aperia’s Halo Connect i3 represents a sophisticated convergence of integrated sensors, connectivity, and cloud reporting optimized for heavy‑duty fleets. Their product positioning emphasizes fleet telematics integration and analytics-led maintenance programs, making them a natural partner for data‑driven operators seeking measurable uptime gains.
-
Cummins Inc. — Meritor Tire Inflation System (United States) — Meritor’s installed base and OEM relationships are a structural advantage; their system is already equipped on a very large number of trailers, demonstrating both manufacturability at scale and real‑world efficacy in fuel and tire management. For strategic buyers, Meritor’s breadth suggests defensive moves (tie‑ups with large fleets) and potential to upsell systems into broader drivetrain service contracts.
-
Hendrickson International (United States) — Hendrickson’s TIREMAAX family has broadened into CP, PRO and PRO‑LB models aimed at the trailer segment. Their approach illustrates the classic OEM strategy of modular product lines that address differentiated price/performance points across trailer platforms.
-
Pressure Systems International (P.S.I.) (United States) — A long‑standing vendor in the ATIS category, P.S.I. combines field experience with integration into TPMS solutions. Their historical leadership is a reminder that market incumbency and installer networks remain valuable assets in adoption cycles that depend on retrofit services.
-
Rotex Automation (Europe) — Rotex’s patented centralized systems and strong European penetration underscore regional variation in technical preference. Their track record of installations provides a useful comparator for program managers assessing regional roll‑out strategies.
-
Stemco (United States) — With tooling and installation toolkits like Aeris, Stemco plays an enabling role in accelerating aftermarket deployment. Their presence signals the importance of reducing retrofit complexity as a pathway to uptake.
-
Notable emergent activity — Small innovators continue to push the envelope: for example, RIX Industries secured early‑stage government SBIR funding to prototype per‑tire, real‑time pressure management systems that could change the precision and value proposition of ATIS for certain applications.
Strategic implications and recommended actions for 2026
-
Fleets: Prioritize measured pilots that capture baseline tire and fuel metrics. Negotiate vendor agreements that include data access, API integration, and shared performance KPIs to protect upside.
-
OEMs and Tier‑1 suppliers: Integrate ATIS as part of broader vehicle electrification and telematics propositions. Evaluate partnerships with specialists to accelerate time‑to‑market while retaining aftersales capture.
-
Investors and M&A teams: Focus diligence on firms that combine hardware robustness with cloud analytics and recurring revenue services. Mid‑market consolidation is likely where installed‑base owners seek to monetize recurring service streams.
-
Regulatory & compliance leads: Maintain a monitoring posture; inspection guidance today is permissive in many jurisdictions, increasing the need to motivate adoption commercially rather than rely on regulatory compulsion.
Research approach and credibility
The PW Consulting analysis uses a blended methodology: triangulation of supplier revenues, installed‑base estimates, OEM build plans, aftermarket retrofit programs, and macro fleet‑level economics. The model year base is 2025 and the forecast span is 2026–2032. Sensitivity analyses are provided for fuel price volatility, tire cost inflation, and differing adoption curves to support scenario planning. The study also reports concentration metrics that indicate a moderately fragmented market, supportive of differentiated entrants and targeted consolidation.
How to use this briefing
This article is a strategic preview: it demonstrates the market’s trajectory, the levers that will determine winners and losers, and the practical areas where executives should act in 2026. The full PW Consulting study contains the granular segmentation, regional and application splits, supplier scorecards, financial models, and implementation playbooks necessary to convert strategic intent into executable programs. For procurement briefs, investment memos, and product roadmaps that require executable detail, access to the full dataset and the accompanying interactive models is essential.
-
Next step: review the full report to obtain the detailed splits, the downloadable ROI calculators, and the vendor scorecards that will allow you to operationalize a 2026 ATIS strategy.
For detailed analysis of this topic, please visit the official page: Automatic Tire Inflation System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com