

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Pressure Vessels Market Poised for 4.93% CAGR to 2032

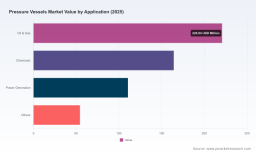
Pressure Vessels Market: Strategic Intelligence Briefing for 2026 Decision-Makers
Executive trailer — what this briefing delivers
As PW Consulting’s lead industry analyst, I present a compact, decision-focused preview of our full Pressure Vessels Market study. This piece is intentionally structured as a high-value “trailer”: it surfaces the critical trends, competitive dynamics, regulatory catalysts, and practical actions executives must consider for 2026 — while preserving the detailed segment-level data and proprietary tables for the full report. Use the insights below to align near‑term strategic moves (procurement, certification, partnerships, and capex phasing). For granular segmentation, downloadable models, and supplier scorecards, the full study remains the authoritative source.
Pressure Vessels Market
Market trajectory at a glance (context for immediate decisions)
The global market for pressure vessels shows steady expansion. Our base-year assessment places total market revenue at USD 550.2 Million in 2025, up from USD 422.4 Million in 2020. Under the scenarios modeled across the forecast window (2026–2032) we estimate a compound annual growth rate of 4.93%, with the market proceeding to an addressable size near USD 769.0 Million by 2032.
Pressure Vessels Market
This growth profile reflects a combination of maintenance-and-replacement demand, new build activity across energy and industrial sectors, and an emergent aftermarket for upgraded designs and instrumentation. Importantly, the profile is uneven — shaped by project cycles in upstream oil & gas and power, regulatory refreshes, and evolving material and fabrication technologies.
Pressure Vessels Market
Why this report is strategic for 2026 decisions
- Capital allocation with timing precision. Our models quantify mid‑cycle versus structural growth so CFOs can sequence CAPEX — accelerating modularization investments while deferring lower‑IRR greenfield capacity in select regions.
- Supplier risk and sourcing playbook. The report’s supplier heatmaps and procurement stress tests show how raw‑material volatility and certification depth (ASME/API) change supplier competitiveness and lead times.
- Regulatory compliance as competitive moat. With 2025 ASME code updates now mandatory, firms that fast-track engineering and documentation changes will win retrofit and certification-dependent projects in 2026.
- Aftermarket and digital service opportunities. The dataset highlights higher-margin service windows (inspection, re-rating, life-extension) that can be monetized within 12–24 months.
What the full report contains — practical, deployable tools
- Comprehensive market model (historical 2020–2025 and forecasts 2026–2032) with downloadable assumptions and sensitivity levers to run custom scenarios.
- Decision frameworks for CAPEX prioritization, including NPV and payback ranges for fabrication capacity, automated testing lines, and localized service centers.
- Supplier evaluation matrix and regional capacity maps (interactive), enabling procurement teams to shortlist vendors by certification, lead time, and technical capability.
- Regulatory impact playbook addressing the 2025 ASME BPVC changes and API inspector certification cycles, with templates for engineering documentation updates and audit checklists.
- Raw‑material cost model linking steel and alloy price pathways to finished-vessel margins — critical because carbon steel remains the dominant cost driver (our analysis references industry data indicating carbon steel can account for roughly 35–45% of production cost).
- Technology and disruption briefing: additive manufacturing case studies, digital twins for fatigue management, and predictive maintenance commercial models.
- Company profiles and strategic scorecards for leading fabricators and OEMs, with playbook-level M&A and partnership recommendations.
Key dynamics shaping 2026 strategy
- Code and certification shocks: The 2025 edition of the ASME Boiler and Pressure Vessel Code (BPVC) Section VIII introduced updated requirements for design-by-analysis and flange design. These changes are mandatory and already driving specification edits across procurement documents. ASME-hosted webinars in March 2026 clarified expectations for documentation and design practices — firms that acted early reduced rework on bids and improved win rates.
- Inspector pipeline and compliance timing: API 510 certification cycles were adjusted across 2025–2027 windows, creating temporary inspector capacity constraints. Project managers and QA leads should embed certification timelines into planning — ignoring them is a common cause of schedule slippage.
- Raw material cost volatility: Steel and specialty alloy pricing remains the largest cost variable for manufacturers. Our stress tests show margin sensitivity to steel price swings; procurement teams need hedging and long‑lead purchasing strategies, particularly for large projects.
- Manufacturing innovation: Additive manufacturing certification advances (notably recent product certification activity in high‑pressure valve components) lower barriers to producing certain complex parts domestically or near‑site, affecting lead times and aftermarket responsiveness.
Competitive landscape — structure and strategic positions
The market shows moderate concentration: the top three players capture roughly a third of market activity while the top five combine for under 40% (CR3 ≈ 32.5%, CR5 ≈ 38.2%). That structural profile creates opportunities for both scale-driven incumbents and nimble specialists.
- Global integrated OEMs and EPCs (large conglomerates and heavy industries) retain advantages in multi‑code, large‑scale project delivery. Their strategic play is to reinforce end‑to‑end offerings — from design and procurement to installation and lifecycle services — and to leverage financing to secure long‑cycle projects.
- Regional fabricators and precision specialists (ASME-accredited manufacturers and PVMA members) compete on lead times, customization, and certification depth for niche applications. These firms can outperform by investing in shop automation, digital inspection, and specialty welding qualifications.
- Component and systems suppliers (engineered products, filtration-integrated vendors) are moving up the value chain by offering modular skids and integrated systems that reduce onsite erection time and warranty exposure.
Representative names featured in our competitive intelligence set include major heavy-equipment OEMs (household industrial conglomerates in Asia and Europe), established ASME fabricators across North America, and a set of specialised engineered-products suppliers. The full profiles in the report include capability maps, recent contract wins, certification portfolios, and inferred capacity utilization — essential inputs for any supplier selection or M&A screening process.
Technology and supply‑chain implications
Recent certification milestones for additively manufactured high-pressure components demonstrate that AM is transitioning from prototyping to niche production. For buyers, the near-term implication is a new sourcing axis: where AM offers reduced lead time and complexity, it should be evaluated against conventional fabrication for critical spares and small-batch specialty parts.
Coupled with digital twin and remote monitoring adoption, manufacturers can now sell “time to uptime” rather than just hardware, creating differentiated after-sales revenue streams. Those who integrate inspection data, life‑prediction analytics, and spare‑parts logistics stand to expand gross margins on installed bases.
Targeted recommendations for 2026 (prioritized)
- 0–6 months: Lock in strategic long‑lead material contracts with price adjustment clauses; commence gap analysis for ASME BPVC 2025 compliance and schedule engineering updates; map inspector availability against critical project milestones.
- 6–18 months: Pilot additive manufacturing for non‑primary pressure boundary components; negotiate service-level agreements with qualified regional fabricators to reduce lead-time exposure; deploy predictive maintenance pilots on high-value installations.
- 18–36 months: Consider bolt-on acquisitions to secure fill‑capacity in underserved regions or to add complementary engineered-product lines; standardize modular designs to shorten quotation-to-delivery cycles and reduce site erection costs.
How to use the full PW Consulting study
The full report is designed as an execution manual for 2026. It contains interactive forecast models you can re-run with your own assumptions, a market-entry checklist by region and application, supplier scorecards, and scenario analyses that quantify the ROI of certification upgrades, automation investments, and contract structures. We also offer tailored advisory workshops to convert the study’s outputs into a 100‑day action plan for procurement, engineering, and strategy teams.
Closing — why now
2026 will be a decisive year for pressure‑vessel players: mandatory code updates, constrained inspection capacity, material price volatility, and technology inflection points are converging. Executives who combine pragmatic risk‑management (material hedging, supplier diversification) with selective investment in certification, automation, and aftermarket services will capture disproportionate share in the coming cycle. For those ready to move from insight to implementation, the full PW Consulting Pressure Vessels Market study contains the models, playbooks, and supplier intelligence necessary to do just that.
Access the complete dataset, segmentation breakdowns, and interactive dashboards via the PW Consulting report portal — your next strategic moves for 2026 should be data-driven and time-sensitive.
For detailed analysis of this topic, please visit the official page: Pressure Vessels Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com