

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Automotive Labels Market to Reach USD 12.5M by 2032 at 5.37% CAGR

Automotive Labels Market — Strategic Preview for 2026 Decisions
Executive snapshot
The global automotive labels market is in a steady phase of expansion, shaped by automotive industry megatrends — electrification, lightweighting, circularity, and increasingly stringent regulatory regimes. Our market model (base year 2025) shows the recorded market size rising from the low single-digit millions in 2020 to an estimated USD 8.67 Million in 2025, with a compound annual growth rate (CAGR) of 5.37% projected across the 2026–2032 forecast window. Under our baseline scenario the market continues to grow through 2032, reflecting continued OEM demand for specialized constructions (underhood, battery, safety, branding) and incremental replacement/aftermarket activity as vehicle parc expands and vehicle systems become more complex.
Automotive Labels Market
Why this study matters for 2026 strategic decisions
- Procurement prioritization: Automotive OEMs and tier suppliers must update supplier qualification and dual-source strategies in 2026 to mitigate certification, material availability and compliance risks. The research identifies where supplier scale matters and where niche technology is decisive.
- Product development & validation: Labels that adhere across high-temperature, chemically aggressive, and EV-specific environments are table stakes. Our analysis highlights validated constructions and test protocols that materially shorten OEM approval timelines.
- Cost & margin planning: With raw-material and adhesive inputs under pressure in recent cycles, manufacturers and converters need defensible cost-to-serve models. The report provides sensitivity analysis and price-leverage playbooks tailored to the label value chain.
- Compliance & risk management: Regulatory compliance (quality system certification and emissions/engine labeling rules) is no longer operational detail — it is a strategic requirement. The report maps the regulatory endpoints that will influence procurement and engineering specifications in 2026.
- M&A and portfolio moves: Given the market’s concentration dynamics, acquisitive consolidation and bolt-on specialty plays are becoming the fastest route to scale and capability. We highlight which capability gaps matter most in near-term deals.
What the full PW Consulting report delivers — practical, actionable content
- Robust market sizing and a transparent forecasting model covering 2026–2032, including base-case and two alternate scenarios. The model is delivered in a downloadable format so teams can run their own sensitivity checks.
- Demand drivers and leading use-case narratives that explain where growth will outpace averages and why (without disclosing the project’s proprietary segment-level figures in this preview).
- Operational playbooks for converters and OEM suppliers: qualification checklists, recommended material specifications for underhood/engine/battery environments, and validated testing protocols to accelerate OEM approvals.
- Supplier benchmarking and scorecards built on financial strength, technical pedigree, global footprint, certification status and product breadth (note: full-scorecard metrics are accessible in the full report to preserve commercial sensitivity).
- Raw-material and adhesive cost-sensitivity analysis, with mitigation strategies including hedging approaches, local sourcing pathways, and formulation alternatives that preserve performance while lowering total landed cost.
- Commercial tools — pricing frameworks, bid templates, cost-to-serve calculators, and negotiation playbooks tailored to OEMs, converters and adhesive suppliers.
- Regulatory & standards compendium: practical guidance on supplier audit readiness (IATF 16949 implications), and jurisdictional label requirements that impact engineering and logistics decisions.
- Strategic M&A and partnership guidance: target profiles, valuation ranges, and integration checklists aimed at buyers seeking to accelerate capability or geographic coverage.
Competitive landscape — who matters and how
The market’s supplier structure is meaningfully concentrated, with the leading global players controlling a large share of commercial activity. That concentration creates both stability — through tested supply chains and validated constructions — and potential points of friction for entrants seeking scale. In 2026, competitive advantage will be defined not only by scale but by demonstrated capability across high-demand performance vectors: high-temperature polymers, battery-compatible constructions, recyclable adhesives, and documented OEM approvals.
Automotive Labels Market
- 3M Company: A scale leader with a full portfolio of durable polyolefin and polyester constructions. Strengths include deep OEM relationships, materials science capability and well-established validation processes. Strategic consideration: incumbency advantage, but premium cost profile requires value justification to price-sensitive tiers.
- Avery Dennison Corporation: A market innovator focused on lightweight and EV battery-compatible solutions; recent product launches and field validation in 2025 underline their go-to-market velocity. Strategic consideration: strong for OEMs prioritizing lightweight/EV programs; opportunity exists for converters to partner on co-development.
- Brady Corporation: Positioned on durable industrial-grade labeling with credentials for harsh environments. Strategic consideration: attractive ally for industrialized vehicle platforms and heavy-duty applications.
- UPM Adhesive Materials (Raflatac rebrand): Recent rebranding and launch of “Carbon Action” and ProCycle adhesives signal a clear strategic focus on circularity and recyclable constructions. Strategic consideration: high relevance for OEMs pursuing circularity mandates and for converters aiming to future-proof product lines.
- CCL Industries: Global converter with pressure-sensitive expertise and scalable manufacturing. Strategic consideration: strong execution capability for large-volume programs and cross-sector leverage.
- Resource Label Group & Whitlam Group: Regional specialists offering UL-recognized and OEM-compliant constructions with local service footprints. Strategic consideration: critical for just-in-time supply and localized certifications.
- UP-Labels, Adhesive Research, H.B. Fuller: Niche specialists — focusing on tire marking, specialty adhesives and engineering-grade adhesive systems. Strategic consideration: valuable partners for technical differentiation and problem-solving in demanding use cases.
Recent industry movements and what they signal
- Avery Dennison’s 2025 product launches and public validation studies show accelerated commercialization timelines for EV and lightweight label constructions — increasing pressure on other suppliers to either co-develop or consolidate.
- UPM’s rebranding and launch of circular adhesive portfolios underscore a structural shift: regulators and OEM sustainability targets are elevating recyclability from “nice to have” to procurement criteria.
- Across the supplier base, the emphasis on validated materials and documented OEM approvals is increasing the value of engineering services and lab capabilities within label providers.
Key market dynamics and strategic implications
Four dynamics will dictate competitive outcomes into and through 2026:
Automotive Labels Market
- Electrification and battery labeling: EV programs demand specific chemistries and adhesive behaviors. Suppliers that can certify battery-compatible labels gain privileged access to long-term OEM programs.
- Circularity and end-of-life requirements: Recyclable adhesives and mono-material constructions are moving from R&D to procurement specs. Suppliers that can demonstrate circular pathways will be favored in bids tied to sustainability KPIs.
- Regulatory and quality regimes: IATF 16949-aligned quality systems and jurisdictional labeling rules (e.g., heavy-duty emissions labeling examples) create non-negotiable supplier gates. Early compliance reduces time-to-production risks.
- Supply-chain resilience and localization: Lead times for specialty films, adhesives and coatings make regional manufacturing and dual-sourcing near-term necessities for demand certainty and cost control.
Strategic playbook for 2026 — concise recommendations
- For OEMs: Tighten supplier qualification to include circularity metrics and verified battery-label compatibility; adopt layered sourcing (global + local) to balance cost and resilience.
- For converters: Invest selectively in validation labs and IATF-aligned processes; prioritize partnerships with adhesive innovators to offer differentiated, compliant constructions.
- For adhesive/material manufacturers: Accelerate circular-adhesive roadmaps and co-development agreements with OEMs; demonstrate lifecycle benefits in commercial bids.
- For investors and M&A teams: Target scale assets with certified OEM footprints or niche tech plays (battery-validated constructions, recyclable labels); integration risk is minimized when target companies possess strong quality systems and documented approvals.
How PW Consulting’s Automotive Labels Market report supports your 2026 roadmap
This study is deliberately structured to be a decision-support toolkit for 2026 planning cycles. Beyond headline forecasts, the report provides:
- a transparent, editable market model;
- scenario-based demand pathways to stress-test capital and procurement runs;
- supplier scorecards and an M&A playbook tailored to label-specific capabilities;
- operational templates (validation protocols, cost-to-serve calculators, contractual language) that teams can deploy immediately to compress approval and negotiation timelines.
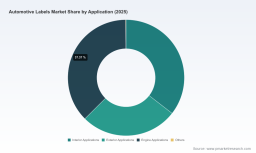
Importantly, this preview is constructed to illustrate depth without disclosing the granular segment-level datasets and company scorecard details that are embedded in the full deliverable. Those items — including application- and region-level breakdowns, detailed margin pools, and proprietary supplier ratings — are available through our report and enable executable decisions in 2026.
Next steps
For teams preparing 2026 budgets, supplier strategy reviews, or M&A pipelines, the full PW Consulting Automotive Labels Market report provides the data, models and playbooks to act with confidence. Access to the complete dataset includes the regional/application splits, supplier scorecards and downloadable financial models that underpin the insights summarized here.
Contact PW Consulting to schedule a briefing or to license the full report and model — so your 2026 strategy is built on market-tested evidence rather than inference.
For detailed analysis of this topic, please visit the official page: Automotive Labels Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com