

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Household Dehumidifiers Market to Reach USD 181.0M by 2032 at 4.25% CAGR

Household Dehumidifiers Market: Strategic Briefing for 2026 Decision-Makers
Executive teaser — why this research matters for 2026
As companies reset strategies for post‑pandemic supply chains, tighter refrigerant regulation, and accelerating consumer demand for indoor air quality (IAQ), the household dehumidifiers market is entering a phase of steady growth and structural change. PW Consulting’s latest study (base year 2025, historical window 2020–2025, forecast 2026–2032) provides the evidence base and decision frameworks that executives, product leaders, channel strategists, and M&A teams need to act in 2026 with more conviction and less risk.
Household Dehumidifiers Market
Market snapshot (what the numbers say, without giving away the secret sauce)
- Base year: 2025 (report currency: USD, revenue unit: Million).
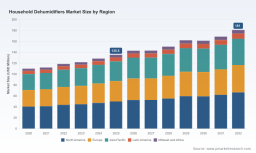
- Near‑term trajectory: the market grows at a compound annual growth rate (CAGR) of 4.25% through the forecast period 2026–2032.
- Benchmark sizing: PW Consulting’s modeled total market value rises from the mid‑three‑figure range in 2025 to the high‑three‑figure range by 2032 (2032 estimate cited in the full report).
- Concentration: the market shows moderate consolidation, with the top three players accounting for roughly the majority share of revenues — a structural feature that shapes pricing power, distribution dynamics, and innovation incentives.
We purposely avoid publishing line‑item regional or product splits here: the aim of this introduction is to demonstrate analytical depth and strategic direction while channeling readers to the full report for proprietary segmentation matrices, scenario tables, and downloadable model files.
Household Dehumidifiers Market
What the full PW Consulting report delivers (practical, transaction‑ready content)
- Transparent market sizing and a reconciled forecasting model (2026–2032) calibrated to macro drivers, appliance adoption curves, and regulatory milestones.
- Scenario analysis (three trajectories) that stress‑tests demand under regulatory acceleration, energy‑price shocks, and an IAQ surge after extreme weather events.
- Competitive landscaping with revenue and portfolio mapping, product roadmaps, and channel share overlays; an M&A heatmap prioritizing strategic targets by capability and valuation sensitivity.
- Go‑to‑market playbooks for OEMs and brand owners: SKU rationalization, after‑sales service models, retail vs. direct‑to‑consumer approaches, and retrofit/whole‑home bundling options.
- Technology and supply chain readiness assessment: refrigerant transition pathways, compressor and heat‑exchange sourcing strategies, and contract manufacturing risk scoring.
- Regulatory impact matrix including tariffs, refrigerant phase‑downs, and energy labeling implications with recommended compliance and advocacy measures.
- Price elasticity and margin benchmarking to inform incentive structures for retailers, rebates, and energy‑efficiency program participation.
Market dynamics reshaping strategy in 2026
- Regulatory inflection points — Global and regional rules enacted in 2024–2026 are a defining factor. Dehydrant players face phasedown schedules and explicit GWP ceilings that force product replatforming. These rules accelerate the obsolescence of legacy refrigerant‑dependent designs and raise the bar for energy and lifecycle compliance.
- Tariff and trade policy shifts — Recent tariff schedule revisions in key markets introduce duty complexity for small‑capacity units. Sourcing strategies and pricing models must be reviewed to avoid margin erosion or channel disruption.
- IAQ and climate risk demand drivers — A measurable uplift in consumer urgency around mold, dampness, and IAQ following extreme weather events is enlarging the addressable base for both portable and whole‑home solutions. Adoption is becoming a function not only of weather, but also of homeowners’ awareness and local incentive programs.
- Energy efficiency and carbon disclosure — Buyers (commercial and residential) increasingly evaluate dehumidifiers through energy‑cost and carbon perspectives. New product launches claim double‑digit energy gains; procurement teams will prioritize lifecycle operating cost over headline price.
Competitive landscape — who matters and why (high‑level intelligence)
The incumbent ecosystem mixes global appliance conglomerates, specialized HVAC/residential OEMs, and regionally strong consumer brands. Market concentration indicates meaningful scale advantages for a small group of leaders — but it also leaves white spaces for agile entrants with differentiated propositions.
Household Dehumidifiers Market
- Midea Group (Guangdong, China) — A volume and innovation leader in the portable segment, with a clear focus on smart, ENERGY STAR‑caliber Cube‑series units and integrated water‑management options. Strengths: manufacturing scale, cost engineering, and a broad consumer channel footprint. Strategic consideration: leverage R&D to migrate energy‑efficient platforms across price tiers while managing trade‑policy exposure.
- Resideo Technologies (Scottsdale, AZ, USA) — Known for the Honeywell Home whole‑home series, the company’s recent next‑generation launch emphasizes serviceability and flexible installation — attributes that resonate with contractors and property managers. Strengths: channel relationships in HVAC aftermarket and a service‑friendly value proposition. Strategic consideration: convert installation flexibility into subscription and recurring‑revenue services.
- LG Electronics Inc. (Seoul, South Korea) — Competes with inverter‑compressor and AI‑driven models that integrate into broader smart‑home ecosystems. Strengths: advanced HVAC controls, brand trust, and cross‑category integration. Strategic consideration: exploit smart‑home bundling and data‑driven maintenance services to command premium pricing.
- Danby Products Ltd (Ontario, Canada) — Focused on compact, consumer‑oriented portable units. Strengths: niche design appeal and price competitiveness in select retail channels. Strategic consideration: pursue co‑branded partnerships and targeted channel exclusives to deepen penetration.
- Frigidaire (Electrolux) (Virginia, USA) — Offers widely tested home‑use portable units under recognized series. Strengths: product reliability and retail presence. Strategic consideration: differentiate through energy‑efficiency labeling and enhanced after‑sales guarantees.
- GE Appliances (Haier) (Louisville, KY, USA) — Integrates smart controls across portable models and leverages strong North American brand equity. Strengths: distribution scale and service networks. Strategic consideration: accelerate digital‑service and warranty ecosystems to monetize data and increase retention.
- Whirlpool Corporation (Benton Harbor, MI, USA) — Produces efficient portable appliances as part of a broad consumer portfolio. Strengths: cross‑category retail leverage. Strategic consideration: test bundled offers (dehumidifier + HVAC products) in climate‑vulnerable regions.
- Honeywell International Inc. (Charlotte, NC, USA) — Supplies both residential and whole‑home dehumidifiers with an IAQ focus. Strengths: enterprise and institutional channels, brand recognition in indoor‑air solutions. Strategic consideration: pursue integrated IAQ systems including monitoring, filtration, and humidity control.
- De'Longhi S.p.A. (Treviso, Italy) — Serves European and premium global niches with compact and design‑led models. Strengths: premium positioning and design differentiation. Strategic consideration: capitalize on energy‑efficiency incentives and upscale channel partnerships.
- TCL Technology (Huizhou, China) — Rapidly expanding smart‑portable offerings through global consumer channels. Strengths: cost‑competitive smart devices and broad retail relationships. Strategic consideration: focus on emerging markets and value segments while enhancing compliance documentation for regulated geographies.
Recent product and regulatory signals to track in 2026
- Product launches that materially reduce energy consumption (example: a 15–20% energy reduction claim by a leading industrial dehumidifier firm) signal the pace at which efficiency will become a purchase differentiator across residential categories.
- Regulatory milestones in 2024–2026 — including refrigerant phase‑downs and GWP ceilings — will force platform redesigns and create short windows for product refresh cycles and inventory rationalization.
- Trade policy changes introducing duties on small‑capacity units in certain markets require near‑term SKU and sourcing reviews to avoid unexpected landed‑cost increases.
Strategic implications and recommended 2026 moves
- Replatform for refrigerant compliance and energy efficiency — Prioritize roadmap investments that address GWP ceilings and deliver measurable operating‑cost savings. Review BOM and supplier qualifications for low‑GWP alternatives now; certification and testing lead times will compress go‑to‑market windows.
- Channel deepening and service monetization — For whole‑home players, convert installation flexibility into service contracts and extended‑warranty programs. For portable brands, focus on retailer partnerships, data‑enabled care, and loyalty offers to defend margin.
- SKU rationalization with margin focus — Use our elasticity and margin benchmarking to prune low‑margin SKUs that are exposed to new tariffs or offer marginal differentiation.
- M&A and partnership playbook — Target acquisitions that deliver rapid compliance capability (refrigerant engineering, efficient compressors), retrofit kits for legacy products, or regional distribution that mitigates tariff exposure.
- Scenario planning and inventory discipline — Implement conditional inventory triggers tied to regulatory release timelines and announced product retirements to minimize stranded stock risk.
Why PW Consulting’s study is worth the 15‑minute read (and the deeper download)
Our report is built for executives who need transaction‑grade insight, not academic verbosity. We combine a reconciled bottom‑up market model with qualitative interviews across OEMs, retailers, HVAC contractors, and standards bodies. The result is a set of executable recommendations, a prioritized action matrix for 2026, and downloadable models you can plug into your planning process.
Final note — a preview that leads to the full intelligence
This article intentionally showcases the strategic contours of our research while withholding proprietary segmentation tables, regional and application breakdowns, and company revenue line items — the “trailer” that demonstrates capability and invites deeper engagement. For companies preparing budgets, product roadmaps, or transaction strategies in 2026, the full PW Consulting Household Dehumidifiers Market report provides the granular inputs and scenario workbooks needed to convert strategy into measurable outcomes.
To access the full dataset, detailed competitor scorecards, and the downloadable forecasting model, visit the PW Consulting report page or contact our Household Appliances practice lead for a briefing calibrated to your role and strategic horizon.
For detailed analysis of this topic, please visit the official page: Household Dehumidifiers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com