

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Shea Butter Market to Hit USD 1,687M by 2032 at 8.2% CAGR

Shea Butter Market 2026: Strategic Imperatives for Executives
As the global shea butter market moves from commodity to strategically differentiated ingredient, 2026 will be the year corporate agendas either lock in resilience or expose supply chains to sustained disruption. PW Consulting’s new Shea Butter Market study (base year 2025; forecast period 2026–2032) synthesizes historical dynamics (2020–2025) with forward-looking scenario modelling to give senior leaders the intelligence required to make decisive moves. Our headline findings: the market has expanded materially since 2020 and is projected to grow at a compound annual growth rate (CAGR) of 8.2% through 2032—creating both margin opportunities and structural risks for manufacturers, traders, and investors.
Shea Butter Market
Why 2026 Is Pivotal
-
Regulatory shifts in producing countries are changing the upstream economics. Recent policy interventions aimed at retaining value-add locally—most notably a wave of minimum-price and processing incentives in West Africa and temporary export restrictions on raw kernels—are already altering trade flows. These measures translate into shorter-term price volatility and longer-term incentives for downstream processing capacity to be located closer to origin.
Shea Butter Market -
Market access requirements in major destination markets have tightened. The EU’s food and consumer safety framework (labelling, hygiene and HACCP standards) and equivalent expectations in other jurisdictions are elevating compliance costs and creating entry barriers for suppliers lacking documented traceability and quality systems.
Shea Butter Market -
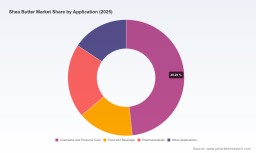
Demand-side evolution is accelerating. Cosmetics and personal care manufacturers continue to favour natural and sustainably sourced fats and butters, while food and pharmaceutical formulators are experimenting with functional and organoleptic applications. These layered demand drivers increase product complexity: raw unrefined, fractionated, refined, organic, and certified-traceable SKUs now coexist, each with different margin profiles and supply requirements.
-
The competitive structure remains moderately fragmented: the top three firms account for a meaningful but not dominant share of the market, and the top five consolidate a larger portion—an environment that supports both strategic partnerships and selective consolidation plays.
Report Scope: What Practitioners Will Find
This study is deliberately practical. Beyond headline market sizing and an 8.2% CAGR projection to 2032, the report equips commercial, procurement, regulatory, and corporate development teams with tools they can apply immediately:
- Transparent market-sizing and forecast methodology with scenario variants (base, downside, accelerated-adoption).
- Supply-chain stress tests that model the impact of export restrictions, minimum-pricing schemes, and quality-spec enforcement on availability and landed cost.
- Regulatory compliance matrix tailored to major destination markets—detailing documentation, hygiene, and labelling expectations and the operational steps to meet them.
- A competitive playbook that profiles incumbent processors, fractionators, and exporters and maps likely strategic responses to policy shifts.
- Commercial playbooks: pricing & contracting templates, offtake negotiation heuristics, and certification roadmaps (organic, fair trade, traceability proofing).
- Practical M&A and partnership readiness tools: acquisition target screening, integration checklists, and post-merger synergies calculator.
- Deliverables include interactive models and downloadable dashboards clients can adapt to their portfolios—while proprietary segment-level datasets are reserved for subscribers.
Competitive Landscape — Strategic Profiles
-
AAK (Denmark) — Strengths: vertically integrated sourcing networks in West Africa and established routes into European and North American manufacturers. Strategic implications: AAK’s integration gives it headroom to absorb upstream policy shocks, but it must protect margin through contractual hedges and investment in origin-based processing to keep costs predictable. For buyers, AAK is a natural partner for secured supply and large-scale co-development.
-
Loders Croklaan (Netherlands) — Strengths: technical refining and fractionation capabilities tailored for both food and cosmetic formulations. Strategic implications: processors with advanced fractionation technologies will capture premium applications where functional characteristics are worth a margin premium. Buyers needing consistent functional performance should evaluate supply partners on processing controls rather than price alone.
-
The Savannah Fruits Company (Ghana) — Strengths: village-level sourcing, organic positioning, and community-based processing models that support rural livelihoods. Strategic implications: firms seeking ESG-credible supply should engage with producers like Savannah, but be prepared to invest in capacity building and traceability systems to scale reliably. There is commercial upside for brand owners willing to co-invest in supplier development.
-
VedaOils (India) — Strengths: wholesale and bulk export expertise, particularly for organic and unrefined shea destined for cosmetic formulators. Strategic implications: traders play an important role in bridging origin quality differentials and buyer specification needs. However, exposure to policy shifts in origin countries creates counterparty risk—due diligence and flexible contracting are essential.
Recent Policy Events and Tactical Consequences
-
Producers instituting minimum-price mechanisms and quality specifications will improve farmer income predictability but compress margins for intermediaries that cannot pass on costs or that lack value-add capabilities. Buyers sourcing raw kernels should anticipate stricter quality verification at origin and build inspection and laboratory capacity into supplier agreements.
-
Export restrictions aimed at stimulating domestic processing alter the arbitrage that traders rely on. When raw nut exports are temporarily curtailed, downstream manufacturers face two choices: secure alternative origins or accelerate investment in local processing partnerships—both require lead times and capital.
-
Regulatory expectations in destination markets are non-negotiable. Firms that delay investment in documented HACCP and labelling compliance risk market access disruption and recall exposure. Early alignment with these standards is a prerequisite for premium positioning in food and nutraceutical channels.
Strategic Actions for 2026
Based on our modelling and stakeholder interviews, PW Consulting recommends the following prioritized actions for executives seeking to convert the projected market growth into defensible earnings:
-
Immediate (0–90 days): perform a supplier-risk heatmap and secure rolling offtake commitments for critical SKUs. Stress-test current contracts against policy-outcome scenarios and re-price or insert force majeure clauses where appropriate.
-
Short-term (3–12 months): accelerate selective vertical integration or joint-venture talks with vetted origin processors. Invest in traceability pilots to meet destination-market compliance and premium-segment requirements.
-
Medium-term (12–36 months): deploy product-differentiation strategies (e.g., certified organic, single-origin, fractionated functional grades) and align marketing to capture higher ASPs that the trend to natural ingredients supports.
-
Portfolio & M&A: consider bolt-on acquisitions in origin countries that provide capacity and quality control, or strategic alliances with processors that can de-risk supply. With market concentration moderate, well-timed acquisitions can yield outsized returns as consolidation accelerates.
-
Risk Management: build a commodity-pricing and quality hedging strategy that accounts for the new regime of origin price floors and episodic export restrictions. Maintain working capital flexibility to weather interim price dislocations.
How to Use This Intelligence
PW Consulting’s Shea Butter Market study is designed as both an executive briefing and an operational toolkit. Use the high-level findings to inform board-level strategic decisions and the embedded models and checklists to update procurement, quality assurance, and regulatory compliance processes. For teams executing M&A or strategic partnerships, our target-screening and integration playbooks reduce due-diligence time and highlight critical earnout and escrow design features specific to the shea value chain.
Conclusion — From Insight to Advantage
The market’s projected expansion through 2032 offers a clear incentive to act: raw-material volatility and shifting policy environments reward firms that combine supply-chain intelligence, regulatory readiness, and selective vertical positioning. PW Consulting’s report provides both the directional market view—anchored to a robust 8.2% CAGR projection—and the operational instruments you need to convert opportunity into a defensible competitive position.
To preserve the commercial value of these insights we intentionally reserve granular, segment-level datasets and region-by-application breakdowns for report subscribers. Contact PW Consulting for a tailored briefing and to access the full dataset, interactive models, and supplier due-diligence templates that will make your 2026 decisions both confident and actionable.
For detailed analysis of this topic, please visit the official page: Shea Butter Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com