

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Cling Film Market to Hit USD 2,610M by 2032 at 5.2% CAGR

Cling Film Market — Strategic Preview for 2026 Decisions
As PW Consulting’s Senior Strategic Advisor and Chief Industry Analyst, I present an executive preview of our latest Cling Film Market study. This briefing synthesizes the research’s strategic value for corporate decision‑makers entering 2026: where to allocate capital, how to defend or expand share, and which capability gaps will determine success. The analysis demonstrates our methodological rigor and commercial relevance while deliberately withholding the report’s granular segment-level tables to guide readers to the full report for the complete dataset and models.
Cling Film Market
Market at a glance — macro trajectory and what it means
-
Market base year and horizon: base year 2025, historical window 2020–2025, forecast 2026–2032.
Cling Film Market -
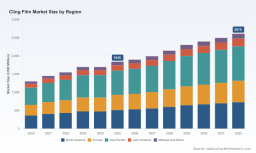
Compound annual growth: the market is projected to grow at a steady 5.2% CAGR across the forecast period, reflecting resilient end‑market demand and ongoing product substitution dynamics.
Cling Film Market -
Macro sizing context: the global market expanded from approximately USD 1.30 billion (2020) to USD 1.84 billion (2025) and is forecast to reach roughly USD 2.61 billion by 2032 (values reported in USD Million).
-
Market structure: concentration metrics indicate a fragmented supplier base (CR3 ~20%, CR5 ~25%), pointing to meaningful opportunities for consolidation, niche premium positioning, and differentiated commercial strategies.
Why this preview matters for 2026 corporate choices
2026 is a pivot year: companies that act now will lock in scale advantages, supply relationships, and innovation roadmaps that compound over the forecast window. Our study frames the market through three decision lenses that executives face this year:
- Investment allocation — where to place capital between capacity expansion, product R&D (e.g., barrier coatings, compostable blends), and automation for cost competitiveness.
- Commercial strategy — how to price, segment customers, and manage private‑label vs branded mixes in a market where scale and service matter as much as formulation.
- Risk management — how to build raw‑material hedges, contingency suppliers, and regulatory compliance programs to minimize margin erosion from feedstock volatility and evolving single‑use plastic policies.
Report contents — operational modules that power decisions
The full report is designed as an operational playbook for business leaders. Highlights of what it delivers (without revealing the proprietary segment tables):
- Robust market sizing & forecasting engine — granular bottom‑up and top‑down models reconciled across demand drivers, producing year‑by‑year revenue projections for 2026–2032 and sensitivity scenarios tied to feedstock price swings and regulatory shocks.
- Demand driver decomposition — consumption drivers by end‑use, channel behavior, and purchasing economics; elasticities calibrated to observed historical adoption and recent disruption patterns.
- Cost & margin analytics — standardized bill‑of‑materials and converting cost models, allowing users to simulate margin outcomes under alternate raw material, energy, and labor cost paths.
- Regulatory and sustainability framework — mapping of material‑specific regulatory headwinds and opportunities (e.g., extended producer responsibility, compostability standards) with recommended compliance roadmaps and labeling strategies.
- Competitive benchmarking toolkit — supplier scorecards and capability matrices (manufacturing footprint, product portfolio, distribution strength, sustainability credentials) that support M&A screening and sourcing decisions.
- Commercial playbooks — go‑to‑market blueprints for premium segmentation, foodservice channel penetration, co‑pack partnerships, and private label optimization, complete with win‑loss commercial templates and negotiation levers.
- M&A & partnership map — identification of strategic targets and partnership archetypes, with synergies quantified under conservative, base, and aggressive integration scenarios.
- Executive dashboards and scenario simulators — interactive templates (Excel/PowerBI) that allow CFOs and business unit leaders to stress‑test plans against price, demand, and compliance scenarios.
Competitive landscape — key players and strategic positions
The cling film market blends consumer and industrial dynamics: household brands must balance shelf presence and price, while industrial and foodservice suppliers compete on performance, safety, and service. Below we outline strategic profiles of the principal firms covered in the report and the implications for competitors and buyers.
- Berry Global Inc. (Evansville, IN) — global reach, broad portfolio spanning foodservice and healthcare. Strengths: scale manufacturing, trusted brand names, and channel access. Strategic imperative: accelerate high‑value differentiated offerings and deepen B2B service models to offset commoditization.
- Amcor plc (Zurich, Switzerland) — positions cling film variants as a performance/value benchmark for foodservice. Strengths: global engineering capabilities and R&D in packaging performance. Strategic imperative: monetize barrier and convenience features through tiered SKUs and licensing with foodservice distributors.
- The Glad Products Company (Oakland, CA) — household brand equity and strong retail distribution. Strengths: consumer loyalty and marketing capability. Strategic imperative: protect retail margins via private‑label defense and premium convenience innovations (dispenser systems, upgrades in cling performance).
- Polyvinyl Films, Inc. (Sutton, MA) — specialty polyvinyl offerings with premium performance claims. Strengths: niche technical differentiation in cling and stretch. Strategic imperative: scale B2B institutional channels (e.g., processors, commercial kitchens) and secure proprietary supply chains for specialty resins.
- Anchor Packaging Inc. (St. Louis, MO) — emphasis on cutterbox safety and professional systems. Strengths: integrated solutions for food processors and service operators. Strategic imperative: expand systems sales and aftermarket consumables to lock in recurring revenue.
- Wrapex Limited (UK) — product innovation in dispenser systems and eco variants for catering. Strengths: product ergonomics and catering channel expertise. Strategic imperative: leverage service contracts and sustainability credentials to win long‑term catering agreements.
Collectively, the competitive picture reveals a market where brand equity, distribution control, and technical differentiation coexist with persistent fragmentation—creating fertile ground for consolidation, vertical integration, and value capture through adjacent services.
Strategic imperatives and recommended actions for 2026
Based on our scenario work and competitive benchmarking, we recommend executives prioritize the following actions in 2026:
- Secure feedstock flexibility — build multi‑sourcing protocols and hedging strategies now; short‑term raw material volatility is the single biggest risk to margins.
- Differentiate through performance & systems — focus R&D on measurable convenience and safety attributes (cutters, dispensers, barrier life) that justify premium pricing and increase switching costs.
- Deploy sustainability roadmaps with financial rigor — quantify cost‑to‑benefit for bio‑based or compostable options and target pilot customers willing to pay for certified claims.
- Targeted M&A and partnership plays — pursue tuck‑ins that add manufacturing density, technical IP, or channel control in prioritized markets; use our M&A scoring template to rank targets against synergy thresholds.
- Commercial optimization — segment customers by value, implement value‑based pricing where performance matters, and automate trade promotion and inventory policies to defend margins.
- Operational resilience — accelerate digital monitoring of conversion yields and energy use; small efficiency gains compound across high‑volume converting operations.
How to use the full report in boardroom decision cycles
Our deliverables are structured to plug into typical corporate planning cadences:
- 90‑day playbook — supplier risk assessment, quick wins in pricing, and pilot sustainability projects.
- 6–12 month plan — capacity investments, product launches, and targeted M&A diligence guided by our financial models.
- 3‑year blueprint — integrated portfolio strategy tying R&D, manufacturing footprint, and channel execution to financial targets derived from our base and upside scenarios.
Final note — why executives should read the full report
This preview highlights the analytical approach and the strategic orientation of our Cling Film Market study. The full report contains the proprietary segment‑level datasets, interactive forecasting models, and supplier scorecards required to convert insight into action. For teams planning investments, commercial restructures, or M&A activity in 2026, the report provides the tactical templates, financial simulations, and negotiation tools to move from hypothesis to executed strategy.
PW Consulting’s study is intentionally crafted as an operational toolkit: deep enough to inform boardroom decisions, executable enough to guide first‑mile implementation, and structured to reveal where competitive advantage can be captured. Access the full report to obtain the segmental breakdowns, downloadable models, and supplier dossiers that underpin the recommendations summarized here.
For detailed analysis of this topic, please visit the official page: Cling Film Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com