

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Management Consulting Market to Reach USD 572.38B by 2032 at 5.63% CAGR

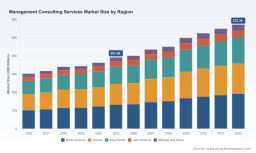
Management Consulting Services Market — Strategic Outlook for 2026 Decision‑Makers
As PW Consulting’s Chief Industry Analyst, I present a concise, action‑oriented introduction to our Management Consulting Services Market study — a field guide for executive teams preparing strategic choices in 2026. The market has demonstrated steady expansion through the last half‑decade and is forecast to sustain moderate growth in the coming cycle. Our base year analysis (2025) captures the sector at roughly USD 392 billion, with a compound annual growth rate (CAGR) of 5.63% projected across the 2026–2032 forecast window, reaching the mid‑hundreds of billions by the end of the period. These headline dynamics matter: they frame investment pacing, talent strategies, and M&A calculus for organisations depending on consulting expertise to accelerate transformation.
Management Consulting Services Market
Why this research matters for 2026
-
Decision timing: 2026 is a pivot year for firms balancing cost containment with accelerated digital and AI investments. The report translates market momentum into executable timing recommendations for pilots, scale‑ups, and exit windows.
Management Consulting Services Market -
Risk‑informed prioritisation: rising compliance and platform risk reshape which projects are safe to outsource, insource, or partner. Our analysis aligns regulatory trajectories with program design to reduce implementation friction.
Management Consulting Services Market -
Supplier selection and negotiation: as leading firms reconfigure delivery models (human + agentic AI blends, productized offerings), buyers need updated criteria to evaluate value versus price — the study provides comparative frameworks and negotiation levers.
-
Talent and cost planning: market‑level labour dynamics and wage inflation for specialised AI/digital skills force a re‑think of operating models; the report gives practical staffing mixes and contingency options to maintain program ROI.
What the report delivers — practical, transactionable outputs
Our study is built for executives who must convert insight into decisions. The full deliverable suite includes:
-
Market sizing, trend narratives, and method transparency — full data tables (historical and forecast), assumptions, and scenario logic so CFOs can model budget impacts.
-
Segment‑level playbooks (go‑to‑market, pricing constructs, productization templates) and buyer persona maps for enterprise procurement leads.
-
Vendor capability matrices and a dynamic decision rubric for choosing between global integrators, Big Four firms, and specialised boutiques.
-
AI adoption framework tailored to consulting engagements — from scoped pilots to enterprise rollouts — with governance checklists and success metrics.
-
M&A and partnership scorecards, including integration roadmaps for bolt‑on targets and joint‑venture structures designed to capture platform‑driven value.
-
Operational playbooks (resource models, blended delivery templates, vendor management scripts) and an Implementation Risk Register that maps common escalation triggers to mitigations.
-
Interactive tools and dashboards — downloadable files that let teams re‑run scenarios using their own cost or revenue assumptions.
Key themes shaping the market in 2026
The research surfaces five interlocking themes that will determine winners and losers in the next cycle:
-
AI as a delivery multiplier — not a replacement: Major firms are operationalising agentic AI at scale. Recent public initiatives show incumbents embedding thousands of AI agents alongside large consultant headcounts to amplify productivity and reach. That shift redefines margins, speed‑to‑value, and the architecture of delivery teams.
-
Rising specialised labour costs: The market is experiencing acute wage pressure for AI, cloud, and transformation skill sets. Independent industry studies point to double‑digit upward pressure on specialist labour costs in the 2025–2026 window, forcing buyers and suppliers to redesign staffing mixes and to accelerate automation of repeatable tasks.
-
Regulatory and privacy complexity: Data privacy and compliance are no longer corner cases. Regulatory guidance and procurement standards — particularly in advanced economies — raise the bar for secure, auditable engagements and slow down some forms of cross‑border delivery unless governance is hardened up front.
-
Concentration and competitive dynamics: The market exhibits a meaningful degree of consolidation at the top. The top three global firms capture a majority share of client wallet in many enterprise categories, and the top five extend control over a substantial portion of commercial engagements — a structural fact that shapes pricing discipline and scale advantages.
-
Productisation and outcome pricing: Buyers increasingly demand outcome‑oriented contracts and modular, productized solutions rather than time‑and‑materials. This trend accelerates the rise of platform offers and embedded software in consulting deliverables.
Competitive landscape — what to watch in 2026
The competitive set remains diverse, with distinct strategic archetypes:
-
Global strategy leaders: Firms with deep strategy heritage continue to win high‑stakes transformation mandates. Their recent moves — including large‑scale AI deployments — indicate a deliberate strategy to combine human capital with machine speed to protect advisory premium.
-
Integrated technology consultancies: Players that pair consulting depth with strong technology delivery capabilities are converting transformation programs into longer, higher‑value relationships across implementation and managed services.
-
Big Four advisory arms: These firms leverage audit and tax relationships to extend into advisory and managed transformation, providing breadth and client intimacy, especially in regulated sectors.
-
Boutiques and specialists: Smaller firms and sector specialists are winning via domain expertise, risk‑focused services, and partnership models with larger integrators; strategic alliances remain a primary route to scale.
-
Sector specialists and government firms: Organisations with deep public sector and defence experience continue to capture regulated, mission‑critical mandates where vendor security and domain trust matter more than price alone.
Recent market developments crystallise these dynamics: announcements of large internal AI deployments, the launch of agentic AI frameworks designed for human–AI collaboration, and strategic partnerships to blend actuarial/risk capabilities with consulting strategy all point to an industry rapidly re‑wiring delivery models and client engagement frameworks.
Strategic implications and an executive decision playbook for 2026
For executives who must convert market signals into corporate action, the following playbook provides immediate priorities:
-
Re‑allocate transformation budgets: Shift a proportion of transformation spend from broad pilots to a set of rapid, measurable pilots that combine AI assistants with skilled human oversight. Prioritise initiatives with clear cash or risk reduction outcomes in the first 12–18 months.
-
Lock in talent scarcity mitigations: Create hybrid staffing models that pair on‑shore senior advisory oversight with near‑shore/automated delivery for repeatable tasks. Invest in in‑house upskilling for AI governance to reduce supplier lock‑in and to preserve negotiating leverage.
-
Redesign supplier contracting: Move towards outcome‑based clauses, performance milestones tied to measurable KPIs, and explicit governance for data privacy and model validations. Include clear exit and knowledge transfer terms to protect institutional capability.
-
Pursue partnership and M&A selectively: Look for bolt‑on capabilities that accelerate platform offers (e.g., specialised AI toolsets or industry compliance capabilities) rather than broadheadcount acquisitions that dilute margins.
-
Embed regulatory readiness: Treat data privacy and compliance as a leading investment area. Early alignment with regulatory expectations reduces rework and procurement friction in regulated sectors.
-
Measure value differently: Adopt a benefits realisation cadence that includes leading indicators (adoption rates, time‑to‑insight) and trailing financial outcomes; align internal scorecards to supplier KPIs to reduce delivery disputes.
How to use the full PW Consulting study
This introduction intentionally foregrounds the strategic implications and hide the granular segmentation tables that procurement, corporate strategy, and M&A teams use to validate specific deals and geographic bets. The full PW Consulting report contains:
-
Complete historical and forecast data tables (2020–2032) by segment and region, plus interactive dashboards for scenario re‑runs.
-
Vendor scorecards and a downloadable negotiation playbook that maps supplier capabilities to business objectives and includes sample contract language.
-
Industry‑specific appendices with tailored go‑to‑market playbooks for BFSI, Healthcare, Manufacturing, and TMT, and a dedicated annex on public sector procurement constraints and opportunities.
-
Access to our analyst team for bespoke modelling and a one‑hour briefing for executive sponsors.
If you are preparing 2026 budgets, sourcing decisions, or attempting to prioritise a transformation backlog, the full study supplies the granular, verifiable data and executable templates required to move from boardroom debate to a disciplined delivery plan. For readers seeking immediate benchmarking, note that the market is materially concentrated at the top: the three largest global firms capture a dominant share of enterprise engagements, and the five largest account for a substantial majority of market value — a structural factor to consider when assessing supplier negotiating leverage and the availability of scale‑driven capabilities.
PW Consulting’s Management Consulting Services Market study is designed as both a strategic compass and a practitioner’s toolkit — to protect downside, accelerate value capture, and give leaders the clarity they need to decide with confidence in 2026. For access to the complete dataset, segmentation breakdowns, and downloadable playbooks, please consult the full report available through our web portal or reach out directly to our analyst team for a tailored briefing.
For detailed analysis of this topic, please visit the official page: Management Consulting Services Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com