

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Residential Elevators Market to Reach USD 330.37M by 2032 at 5.45% CAGR

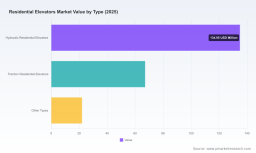
Residential Elevators Market — Strategic Brief for 2026 Decision-Making
As PW Consulting’s lead industry analyst, I present a focused, actionable introduction to our full Residential Elevators Market study — designed to inform executive strategy and capital allocation decisions in 2026. This brief synthesizes the structural forces, regulatory inflection points, supplier dynamics, and demand vectors that will shape winners and losers across the residential elevator ecosystem through our forecast horizon (2026–2032).
Residential Elevators Market
Executive snapshot
-
Market trajectory: The global residential elevators market is on a steady growth path, expanding from a mid-single-hundred million dollar base in 2020 to an estimated USD 224.17 million in 2025 (base year). Our forecast projects a compound annual growth rate (CAGR) of approximately 5.45% over 2026–2032, reaching roughly USD 330.37 million by 2032.
Residential Elevators Market -
Competitive structure: The market exhibits moderate concentration — the top three players account for under half of market share while the top five capture just over half — a structure that supports both consolidation opportunities and regional/local specialization plays.
Residential Elevators Market -
Strategic inflection points: New international safety standards, persistent material-cost pressure (notably steel), and accelerating demand for retrofit and accessibility solutions collectively create timing-sensitive opportunities for manufacturers, distributors, and integrators.
Why this study matters for 2026 decisions
-
Tactical timing: 2026 is a decision-rich year. Firms that act now to align product roadmaps, compliance investments, and supply-chain hedges will capture disproportionate share as standards and cost inputs evolve.
-
Regulatory alignment: The transition to ISO 8100 (rolling out March 2026 with an established transition window) and existing regional mandates (e.g., ASME A17.1 in the U.S., CSA B355 in Canada) make compliance design and certification planning a multi-year, resource-intensive process. Early alignment de-risks market entry and tender competitiveness.
-
Capital allocation: The modest but reliable CAGR across the forecast period supports disciplined growth investment — targeted facility expansions, modularization R&D, and dealer network buildup — rather than broad-brush capex bets.
Market trajectory and what the numbers mean
-
Historical momentum: The market grew consistently from 2020 through 2025, with resilience against episodic headwinds. That baseline momentum supports a predictable base demand for new builds and an expanding retrofit opportunity set driven by aging housing stock and accessibility trends.
-
Forecast posture: At a roughly 5.45% CAGR for 2026–2032, growth is solid but not hyperbolic. This pace favors execution excellence — scalable production, repeatable installation processes, and strengthened channel economics — over reliance on singular disruptive product launches.
-
Concentration implications: With top-three and top-five shares indicating moderate concentration, there is room for regional champions and differentiated specialists (e.g., pitless vacuum systems, shaft-free modulars, luxury traction systems) to thrive alongside established incumbents.
Key market dynamics and catalysts
-
Standards and certification: The imminent ISO 8100 rollout (March 2026) represents the most consequential near-term change. Although a transition period reduces immediate enforcement risk, companies must pre-certify product variants and update technical documentation to avoid go-to-market friction. In parallel, adherence to ASME A17.1 in the U.S. and CSA B355 in Canada remains non-negotiable for installed-base servicing and project wins.
-
Cost inputs and supply chain: Steel tariffs and supply-chain bottlenecks have elevated production costs and extended lead times. Firms that optimize sourcing (regional suppliers, forward contracts) and redesign for material efficiency will protect margins and delivery credibility.
-
Product innovation vectors: Modular, pitless, and vacuum-driven architectures are unlocking retrofit installations and improving time-to-install in constrained residential footprints. At the same time, traction-based systems and luxury packages sustain demand in high-end new builds.
-
Channel economics: Dealer networks, installer training, and service capability are the primary barriers to scale. Firms that invest in certifying installers, digitizing order-to-install workflows, and offering predictable installation windows secure higher conversion and aftermarket revenue.
-
Policy and accessibility tailwinds: Aging populations and inclusive design programs in several mature markets continue to support retrofit volume — a recurring revenue stream that magnifies lifetime customer value when paired with maintenance contracts.
Competitive landscape — capability map of core players
-
Savaria (Canada): A North American production and assembly leader that recently scaled capacity in the U.S. Southeast. Savaria’s investments enhance speed-to-market for traditional and panoramic residential product lines and strengthen fulfillment for major dealer partners.
-
Inclinator (USA): Known for highly customizable residential solutions. Their strength is in engineering-led differentiation and bespoke project capabilities, making them a preferred partner for bespoke homes and architect-driven specifications.
-
Garaventa Lift (Canada): A recognized name in custom home elevators, with product families geared toward both traditional and contemporary applications. Recent trade-show recognition reinforces brand positioning for designer and builder channels.
-
Stiltz Lifts (USA): Specializes in modular, shaft-free elevators that reduce structural work and installation time. Their approach is particularly effective in tight retrofit contexts where minimal disruption is a selling point.
-
PVE (Pneumatic Vacuum Elevators, USA): Developer of pitless vacuum systems that offer distinctive value propositions (speed of installation, reduced civil scope). These systems appeal to a niche of customers prioritizing non-invasive installs and showrooms seeking visual spectacle.
-
Residential Elevators (USA): A full-service manufacturer and catalog-driven supplier whose updated product catalog (2025) reflects a catalog-to-install pathway that supports trade partners and architects.
-
Cambridge Elevating (USA): Recognized for design-led models and an emphasis on installation quality. Their product lineup and service capabilities make them competitive in both accessibility and premium segments.
-
AmeriGlide (USA): Focused on hydraulic and drum-mechanism solutions, AmeriGlide addresses accessibility-first buyers and retrofit cases where straightforward mechanics reduce maintenance complexity.
-
Nibav Lifts (USA): Offers air-driven, pitless solutions for small homes and retrofit applications, positioning around low-cost installation and minimal structural impact.
-
Otis (USA): Brings global engineering rigor and premium product architecture to residential contexts, leveraging its high-end Gen2 systems for luxury homes and developer projects that demand elevated brand assurance.
Recent market signals to watch (selection)
-
Facility expansions by established manufacturers point to a focus on lead-time reduction and serviceable inventory for key markets.
-
Trade-show recognition for design-oriented models is amplifying demand through builder and architect channels.
-
Updated product catalogs and configurator tools reflect a shift to digital sales support — enabling dealers and specifiers to accelerate decision cycles.
What the full PW Consulting report delivers (high-action components)
-
Validated market sizing and demand-model (base year 2025) with scenario-driven forecasts through 2032 that quantify upside/downside risk by macro-scenario.
-
Regulatory playbook: a step-by-step compliance matrix for ISO 8100 adoption and region-specific certification requirements, plus recommended timelines and cost buckets to mitigate certification lag risk.
-
Supply-chain stress tests and procurement levers tied to material-price volatility, including hedging options, regional supplier strategies, and BOM redesign opportunities.
-
Competitive benchmarking: capability maps, go-to-market profiles, and service-network overlays for the leading manufacturers and specialist providers.
-
Commercial toolkit: pricing sensitivity models, channel margin templates, retrofit economics calculators, and ROI models for dealer network investments.
-
Acquisition and partnership targets: prioritized list and rationale for M&A/partnering opportunities by capability gap and geographic ambition.
-
Implementation playbooks for product modularization, certification sequencing, and installer enablement programs.
Strategic actions we recommend in 2026
-
Prioritize compliance-first product roadmapping: sequence product certification workstreams to align with ISO 8100 milestones — secure pre-certification where feasible to preserve sales cadence.
-
Hedge material risk: implement a layered procurement strategy combining local supplier qualification, forward contracts for critical inputs, and design-for-material-efficiency initiatives.
-
Scale retrofit enablement: invest in modular, low-civil-installation solutions, and bundle maintenance contracts to grow lifetime value from aging-housing stock demand.
-
Strengthen channel economics: develop certified-installer programs, digital configurators, and lead-generation partnerships with builders and accessibility specifiers.
-
Assess targeted M&A: prioritize acquisitions that fill capability gaps (e.g., vacuum systems, modular shaft-free platforms, rapid-install specialists) or expand service footprint in high-concentration regional markets.
How to use this brief and next steps
-
This document is a gateway: it highlights where to focus management attention in 2026 but intentionally leaves the detailed segmentation analytics and proprietary model outputs for the full report to preserve commercial value and context.
-
For boards, M&A teams, and product leaders: use this brief to frame scenario workshops and prioritize short-lists for certification and supply-chain investments.
-
To access the complete dataset, segmentation breakdowns, and executable implementation templates (including dealer-margin schedules, retrofit ROI calculators, and procurement playbooks), consult the full PW Consulting Residential Elevators Market report.
PW Consulting stands ready to translate these insights into a tailored action plan — from rapid compliance audits to M&A diligence and channel redesign — enabling your team to convert 2026’s regulatory and market shifts into sustained competitive advantage.
For detailed analysis of this topic, please visit the official page: Residential Elevators Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com