

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Electric Submeter Market Poised for 6.98% CAGR to 2032

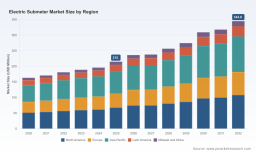
Electric Submeter Market — 2026 Strategic Preview (PW Consulting)
As organizations shift from energy conservation rhetoric to measurable accountability, electric submetering has become a strategic instrument for landlords, facility managers, utilities, and energy service providers. PW Consulting’s latest market study (base year 2025; forecast 2026–2032) synthesizes proprietary modeling, regulatory scanning, and vendor due diligence into a decision-grade briefing for executives preparing 2026 plans. The market that was approximately USD 163.2 million in 2020 expanded to roughly USD 215.0 million by 2025 and is projected to grow to about USD 344.8 million by 2032, reflecting a compound annual growth rate of 6.98% over the forecast horizon. This preview highlights the research’s strategic value while intentionally withholding granular segment-level figures to invite readers to access the full study.
Electric Submeter Market
Why this research matters to 2026 decision-makers
- Capital allocation: Quantifies the addressable opportunity across retrofit and new-build pathways so CFOs can prioritize CapEx vs. OpEx commitments.
- Regulatory readiness: Distills emerging compliance vectors—municipal mandates, state-level rule changes, and updated national metering standards—into action checklists for legal and operations teams.
- Vendor selection: Converts vendor claims into procurement criteria and a repeatable vendor-scorecard methodology to reduce selection risk.
- Commercial models: Evaluates service-led offerings (SaaS + billing) vs. hardware-centric models and shows where margin pools and recurring revenue are most likely to open up.
- Technical integration: Aligns meter accuracy choices, communications stacks, and integration patterns with business outcomes (tenant billing, demand management, ESG reporting).
Trailer-style takeaways — what we can reveal here
- Market trajectory: The submeter market is a steady-growth, mid-single-digit CAGR market underpinned by regulatory enforcement, tenant billing economics, and portfolio-level energy analytics adoption. The overall market expansion provides a sizeable runway for both product players and service providers through 2032.
- Regulation is the accelerant: Recent moves—ranging from municipal building mandates to state utility commission protocol updates and a refreshed national metering standard—are creating discrete adoption triggers. These regulatory vectors shorten procurement cycles for many building owners and create compliance-driven demand for revenue-grade options and documented interoperability.
- Cost and labor dynamics compress near-term margins: Low-cost meter alternatives and an increased supply of wireless, preconfigured devices are lowering entry barriers for adopters, while skilled install labor and retrofit complexity remain primary constraints to rapid scale.
- Product + Service convergence: The most resilient supplier models bundle accurate metering hardware with cloud-based analytics, billing platforms, and a services layer (installation, maintenance, and dispute resolution). Pure hardware plays face near-term pricing pressure; pure software plays must demonstrate integration economics to capture billing revenue streams.
- Data quality drives value: Organizations that insist on actionable, normalized metering datasets unlock value across tenant billing, energy procurement, load-shaping, and decarbonization reporting. The margin between an observational meter and one that supports revenue-grade settlement and programmatic control is a primary strategic inflection.
Competitive landscape — how to read the supplier field
The supplier ecosystem is diverse: nimble wireless innovators, established electrical equipment manufacturers, specialist integrators, and billing-service providers each occupy distinct positions. Below is a concise positioning of the core players examined in our study and what each archetype signals for buyers and investors.
Electric Submeter Market
- Enertiv (New York): Specializes in real-time submetering for tenant billing and portfolio analytics with an emphasis on multifamily and commercial portfolios. Strengths: data analytics, tenant-billing workflows, and portfolio-level monitoring. Considerations: ideal where analytics-driven asset optimization is the priority.
- Meazon (Patras, Greece): Focused on low-cost wireless submeters and distributed sensing. Strengths: low-cost point solutions and wireless deployments that reduce upfront hardware installation complexity. Considerations: attractive in large-scale, cost-sensitive rollouts but requires careful validation for revenue-grade applications.
- Emergent Metering (West Chester, PA): Emphasizes circuit-level electric submetering and multi-utility (water, gas, BTU) solutions with wireless communications. Strengths: breadth of metering modalities and suitability for institutional and industrial facilities. Considerations: strong fit for campuses and facilities needing consolidated utility views.
- nanoGrid : Offers real-time hardware and SaaS for granular electricity, gas, and water monitoring with automated reporting. Strengths: tight hardware-software integration and automated reporting workflows. Considerations: positioning favors organizations that require end-to-end operational reporting without deep internal integration.
- Leviton (Melville, NY): An incumbent with commercial utility submetering solutions and established product lines focused on accuracy and compliance. Strengths: distribution reach and product reliability. Considerations: incumbency advantages in regulated and large commercial procurements.
- H2O Degree , FlowRite Metering , Synergy Utility Billing , and EKM Metering Inc. : These players represent installation specialists, billing-service vendors, and smart-meter product specialists. Strengths: service depth and customer-facing billing operations. Considerations: customers often contract these suppliers when outsourcing meter-to-bill responsibilities.
Competitive implications: vendors that can package accurate metering with simplified install procedures, robust communications stacks, and a billing-compliant service layer will capture disproportionate share of recurring revenue pools. Buyers should prioritize vendors whose field performance has been externally validated under the new national metering performance regimes and in federal or state pilots.
Electric Submeter Market
Recent regulatory and standards signals to factor into 2026 plans
- Municipal mandates that require submeters in defined building classes are accelerating retrofit decision timing for many property owners.
- Federal and state agencies are actively evaluating low-cost submeter options for facility management programs, which is increasing procurement scrutiny and third-party validation needs.
- The revised national metering performance code introduces updated test criteria and performance thresholds that affect device selection, testing regimes, and warranty obligations.
- State-level rule amendments are formalizing procedures for submetered-party inquiries and billing disputes, which raises the bar for vendor-provided dispute-resolution workflows.
What’s inside the full PW Consulting report (operational highlights)
The full report is designed as a playbook for 2026 execution. Practical deliverables include:
- Market sizing and top-line forecasts (2020–2032) with scenario modeling to stress-test outcomes under conservative, baseline, and accelerated regulatory adoption curves.
- TCO and payback templates that account for hardware, communications, installation complexity, ongoing maintenance, billing operations, and avoided energy costs.
- Vendor scorecards with evaluation criteria across accuracy, communications, scaleability, service coverage, cybersecurity posture, and total cost of ownership.
- Procurement and contract playbook including sample SLA language, acceptance test protocols, and escrow provisions for data portability.
- Pilot design blueprints and success metrics to accelerate meaningful scale after a proof-of-concept.
- Integration checklists for common building management systems, energy platforms, and enterprise analytics stacks.
Strategic recommendations for 2026
- Adopt a modular rollout approach: prioritize pilots in assets with the highest measurability value (billing disputes, high energy intensity, or ESG materiality) before portfolio-wide rollouts.
- Lock in interoperability: require open APIs, standardized data schemas, and clear handoff procedures to avoid vendor lock-in at the data layer.
- Drive procurement toward performance outcomes: write contracts that align payment milestones with verified meter accuracy, data quality, and billing reconciliation outcomes.
- Plan for O&M: include installation, calibration, and dispute-resolution costs in lifecycle models rather than assuming post-install passive operation.
- Engage regulators early: pursue pre-approval or pilot exemptions where possible and use federal/state testing results as independent validation during vendor selection.
- Consider partnership models: software providers should pursue installation partners; hardware vendors should partner with billing-service firms to capture recurring revenue streams.
Next steps — how to use this preview
Use this preview to align leadership around the market opportunity and to prioritize the internal stakeholders (procurement, legal, facilities, IT) that must be engaged for 2026 initiatives. The full PW Consulting report contains the detailed segment-level forecasts, vendor performance matrices, and downloadable templates that directly support procurement and pilot execution. For teams planning capital deployment or vendor consolidation in 2026, the contained scenario models and vendor scorecards will materially shorten vendor selection cycles and reduce implementation risk.
To access the full analysis, segmented forecasts, and operational toolkits referenced here, please download the complete Electric Submeter Market report from PW Consulting’s publication page. The full report contains the empirical detail required to convert this strategic preview into an executable program for 2026.
For detailed analysis of this topic, please visit the official page: Electric Submeter Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com