

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Sugar Centrifugal Screens Market to Reach USD 275M by 2032 at 6.5% CAGR

Strategic Outlook: Sugar Centrifugal Screens Market — A 2026 Decision-Making Playbook
Executive summary
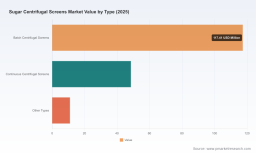
As sugar producers pursue higher yields, tighter crystal retention and lower operating costs, centrifugal screening solutions are moving from commodity components to strategic enablers. PW Consulting’s latest market study—benchmarked to base year 2025—shows a resilient industry trajectory with the global market expanding from the low hundreds of USD Million in 2020 to USD 177 Million in 2025, and a projected continuation at a compound annual growth rate (CAGR) of 6.5% through our 2026–2032 forecast window. By 2032 the market is expected to be materially larger than in 2025, reflecting a multi-year modernization cycle across refineries and beet/sugar milling operations.
Sugar Centrifugal Screens Market
Why this matters for 2026 strategic choices
-
Timing of spends: Supply-chain constraints, replacement cycles and wear-driven retrofits create discrete windows in 2026 where capital allocation decisions will disproportionately affect plant throughput and TCO over the next five years.
Sugar Centrifugal Screens Market -
Supplier selection: With moderate market concentration (our analysis shows leading three vendors control a significant share and the top five a clear majority), OEM partnerships and procurement frameworks will determine access to high-durability alloys, certified test documentation and aftermarket service levels.
Sugar Centrifugal Screens Market -
Technology differentiation: Materials and manufacturing techniques—electroformed nickel, laser-drilled geometries, mirror-smooth finishes—are no longer niche choices but central determinants of crystal damage rates, screen life and downtime risk.
Market trajectory: What the topline tells us
Between 2020 and 2025 the market experienced steady growth driven by equipment replacement, capacity upgrades and geographic investment in refining infrastructure. Our model—anchored on base year 2025—projects continued growth at a 6.5% CAGR through 2032, reflecting both organic replacement demand and incremental adoption of premium screening technologies. For executives planning 2026 budgets, the implication is clear: investing in screen reliability and supplier integration now generates outsized operational returns during the forecast period.
Key strategic implications
-
Cost-to-serve versus unit price: Buyers must shift procurement metrics from upfront unit price to a lifecycle cost basis. Durable materials such as electroformed nickel—recognized for wide chemical resistance ranges—can significantly reduce unexpected failures and lower TCO through extended service life and reduced downtime.
-
Certification and compliance posture: Export-oriented operations need screens with complete test certificates aligned with ASTM, ANSI and ISO parameters. Lack of compliant documentation is a non-tariff trade friction that can delay shipments and increase inventory holding costs.
-
Aftermarket and service as value levers: Given the market’s concentration dynamics, manufacturers and suppliers who bundle installation, predictive wear analytics and fast-replacement logistics are likely to capture higher-margin aftermarket revenue and stickier customer relationships.
-
Operational resilience: For sugar processors, marginal improvements in screen surface finish and hole geometry translate to measurable uplifts in crystal yield and a reduction in fines. These process improvements compound across seasons and must be reflected in capital planning models for 2026.
Competitive landscape: who matters and why
Our competitive review synthesizes primary-profiled vendors, OEMs and specialized fabricators. The market shows a mix of material specialists, centrifuge OEMs and precision-perforation houses—each occupying differentiated roles along the value chain.
-
Fine Perforators (India) — Specialist in electroformed, near-pure nickel screens engineered for continuous centrifugal machines. Their product positioning emphasizes chemical resilience and export compatibility with major centrifuge brands. For buyers seeking cost-effective electroformed solutions, Fine represents a high-volume supplier with export credentials.
-
Ferguson Perforating (United States) — Focused on batch centrifugal screens and backing screens, supplying a broad range of hole patterns and materials (stainless and brass options). Ferguson’s strength is customization for legacy batch installations and rapid-response support for retrofit programs.
-
Veco Precision (Belgium) — Provider of electroformed pure-nickel screens with mirror-smooth surfaces designed to minimize crystal breakage. Veco’s technology premium is attractive to processors prioritizing product quality and low crystal breakage rates.
-
RMIG (Belgium) — Supplies working and backing screens for batch and related sugar processing equipment. Their portfolio supports manufacturers looking for integrated screen and basket assemblies.
-
Western States Machine Company (United States) — A centrifuge OEM that also supplies ringed/ringless baskets and screens; offers operational guidance on expected service intervals and best-practice installation—an important advisor role whether you buy from them or another vendor.
-
Fives Cail & Fletcher (France) — OEM designer of batch and continuous centrifuges with integrated screening solutions. Their advantage is system-level compatibility and global project execution capabilities.
-
Action Laser (United Kingdom) — Emerging as a tactical solution provider with laser-drilled screens designed to solve high-wear issues; recent field deployments demonstrate practical gains in screen longevity under high-abrasion conditions.
-
BMA & Hein Lehmann (Germany) — Established centrifuge manufacturers offering precision screen integrations and global service networks—relevant for plants seeking turnkey upgrades or coordinated retrofit programs.
Recent developments that influence 2026 plans
Case studies and product deployments in 2024–2025 indicate an acceleration in adoption of higher-durability manufacturing techniques. For example, a notable deployment of laser-drilled centrifugal screens successfully addressed high-wear screen life problems at a major sugar processor in the UK—underscoring that targeted technology swaps can materially extend service intervals and reduce unplanned downtime. Additionally, industry guidance increasingly requires full test certification and material traceability for electroformed nickel solutions—factors that can materially influence supplier selection and lead times.
Regulatory and material dynamics
-
Standards compliance: Electroformed nickel screens are expected to meet ASTM, ANSI and ISO specifications for corrosion resistance and dimensional stability—requirements that influence export eligibility and acceptance testing at refineries.
-
Material trade-offs: Electroformed nickel offers superior chemical resistance across a wide pH range and surfaces that reduce crystal attrition relative to stainless alternatives. The productivity benefits need to be weighed against procurement lead-times and alloy cost volatility.
-
Maintenance guidance: Equipment OEMs provide expected lifecycle ranges for standard screens under recommended maintenance regimes; aligning maintenance protocols with material choices reduces variability in operating results.
What our full PW Consulting report delivers (practical contents)
This study is intentionally pragmatic for 2026 decision-makers. Highlights include:
-
Actionable procurement frameworks—how to translate lifecycle cost models into RFQ/RFP templates and SLA clauses;
-
Replacement timing playbooks—detailed decision trees to sequence screen swaps, retrofit campaigns and inventory buffers so that capital and operating expenses are optimally phased;
-
Supplier scorecards—an assessment matrix covering material technology, lead-time resilience, certification completeness and aftermarket response times;
-
Wear and lifecycle analytics—benchmarks for expected service life under different chemistries and operational regimes, plus guidance on how to instrument condition-based replacement;
-
Case study pack—real-world implementations, including laser-drilled and electroformed nickel deployments, with measured outcomes on screen life, downtime hours and process yield impacts;
-
Risk register and mitigation playbook—covering material supply volatility, export compliance and regulatory inspection readiness.
How to use this research in 2026
-
For procurement leaders: prioritize suppliers who can provide certified material traceability, predictable lead times and bundled aftermarket coverage; shift KPIs toward lifecycle cost and unplanned downtime reduction.
-
For operations managers: adopt mission-critical monitoring of screen condition and institute pilot retrofits of high-durability technologies where wear histories show the greatest ROI.
-
For OEMs and component makers: invest in demonstrable proof-points—field trials, certificates and third-party validations—that convert technical superiority into procurement acceptance.
-
For investors and M&A teams: the market’s concentration and mid-single-digit CAGR create opportunities for bolt-on consolidation among precision screen specialists and aftermarket service platforms.
Conclusion & next steps
By 2026, the decisions you make about centrifugal screening—material selection, supplier partnerships, and maintenance strategy—will have multi-year consequences for throughput, product quality and operating cost. PW Consulting’s study frames these choices against a clear market trajectory and provides operationally grounded tools to shape procurement and engineering programs. For executives seeking the full dataset, segment-level dynamics and supplier-by-supplier performance metrics, our comprehensive report contains the granular intelligence necessary to execute with confidence.
To access the complete study, including in-depth segment analysis, regional demand drivers and the supplier benchmarking dataset, please refer to the PW Consulting publication hub—this preview intentionally omits the granular segmentation figures to protect the strategic value of the full report.
For detailed analysis of this topic, please visit the official page: Sugar Centrifugal Screens Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com