

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Histidine Market to Reach USD 338.85M by 2032 at 6.8% CAGR

Histidine Market 2026: Strategic Briefing for Executive Decision-Making
As PW Consulting’s Chief Industry Analyst, I present a focused, strategic primer on the global L‑Histidine market — an essential amino acid whose demand dynamics are increasingly dictated by biopharma manufacturing, advanced feed formulations, and higher‑grade food and clinical nutrition markets. This briefing synthesizes our 2025 base‑year analysis and our 2026–2032 forecast to highlight the decisions that will matter most for corporate leaders in 2026. We intentionally present high‑value insights and directional intelligence while reserving granular segmentation tables and proprietary scenarios for the full report.
Histidine Market
Market Trajectory at a Glance
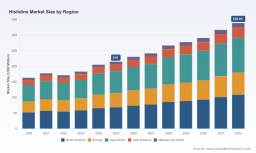
The histidine market has shown resilient expansion through the early 2020s. Our base‑year analysis places global market size at roughly USD 215 million in 2025, up from about USD 163 million in 2020. Over the forecast horizon (2026–2032), we expect continued, steady growth — a compound annual growth rate (CAGR) of 6.8% — taking the market toward the high‑hundreds of millions by 2032. This trajectory reflects a confluence of structural drivers rather than a short‑cycle commodity surge: increasing demand for high‑purity, GMP‑grade amino acids for cell culture and parenteral nutrition; incremental adoption in precision animal nutrition; and broader formulation innovation in food and specialty applications.
Histidine Market
Why the 2026 Inflection Matters
- Strategic timing: 2026 is the first full planning year after the most recent base‑year benchmarking and incorporates supply‑side shifts observed through 2025. Decisions made in 2026 — capacity investments, supply‑chain realignment, partner selection, and regulatory positioning — will determine market share capture throughout the next cycle.
- Quality premium: Buyers are increasingly differentiating suppliers on purity, endotoxin control, traceability, and regulatory compliance. Commoditization risk persists at lower‑grade segments, but a clearer bifurcation is emerging between commodity and specialty histidine markets.
- Fragmented supply base: Market concentration metrics indicate a fragmented competitive landscape, which creates both volatility risks (spot shortages/pricing) and opportunistic M&A corridors for well‑capitalized buyers.
Key Strategic Themes for 2026
Our analysis identifies five strategic themes that should guide executive action in 2026:
Histidine Market
- Supply resilience as a competitive moat: Securing reliable, certified sources of high‑purity histidine is a precondition for biopharma and clinical nutrition customers. Executives should prioritize multi‑tier sourcing, qualify fermentation‑based supplies where applicable, and consider inventory strategies commensurate with product criticality.
- Product and process differentiation: The premium end of the market rewards investment in GMP processes, low‑endotoxin production, and validated impurity profiles. Technical differentiation is more durable than cost‑only competition.
- Regulatory surveillance and trade policy agility: Recent policy moves in supplier jurisdictions can create abrupt routing and availability changes. Active monitoring and contingency playbooks are essential.
- Value chain partnerships over spot procurement: Strategic partnerships (co‑development, tolling, long‑term supply agreements) are the fastest path to embedded commercial advantage and to mitigate quality and capacity risk.
- Selective vertical integration and regional footprint optimization: For companies exposed to end‑market value at scale, acquiring or co‑investing in upstream fermentation and purification capabilities can protect margins and ensure product spec control.
Competitive Landscape: Who Sets the Bar?
The market presents a mix of global specialty chemical and life‑science suppliers, regional fermentation producers, and active chemical manufacturers. The landscape is characterized by a few globally recognized suppliers with high‑purity, GMP‑grade offerings alongside regional players that serve food, feed, and lower‑grade industrial demand. This fragmentation opens strategic options: partner with global leaders to access premium markets, or consolidate regional capabilities to capture local scale advantages.
- Global fermentation and life‑science leaders: Several established firms supply pharmaceutical‑grade L‑Histidine geared to cell culture, parenteral nutrition, and regulated bioprocess applications. Their strengths lie in validated GMP processes, regulatory dossiers, and long‑standing customer relationships in biopharma.
- Specialty chemical suppliers: These players provide flexible product formats across industrial, feed, and food channels and can be a rapid source for scale but may require additional qualification for parenteral or high‑purity use cases.
- Regional manufacturers: Local producers are important for cost competitiveness and shorter lead times. Their strategic value increases where logistics complexity or trade policy creates friction for imports.
Notable corporate moves in recent years underscore these themes. For example, a strategic partnership announced in 2025 between a major global amino‑acid firm and a Chinese chemical partner aimed to expand fermentation‑derived histidine output and secure global supply — a blueprint that other players may replicate. Such alliances reflect the tension between securing proprietary high‑purity supply and leveraging regional capacity for scale.
Regulatory and Trade Dynamics: New Risks and Windows of Opportunity
Trade policy developments in supplier countries can materially affect raw‑material flows for amino‑acid production. A recent regulatory shift — the suspension of certain export controls in a major supply jurisdiction through late‑2026 — has created temporary relief in chemical intermediate availability but also increased uncertainty for medium‑term sourcing. Executives must factor two operating realities into 2026 plans:
- Policy reversals are possible and can be abrupt; contingency sourcing and inventory buffers should be stress‑tested to realistic disruption scenarios.
- Shifts in trade controls can also open near‑term arbitrage or partnership windows; agile companies can secure advantaged supply arrangements during such windows.
What the Full PW Consulting Report Delivers
Our comprehensive study (base year 2025; forecast 2026–2032) combines quantitative forecasting with executable intelligence for commercial strategy. Key practical deliverables include:
- High‑fidelity demand modeling aligned to biopharma, feed, food, and other end‑use vectors, with scenario outputs tailored to different ramp‑up situations.
- A supplier capability matrix that benchmarks global and regional producers on GMP readiness, endotoxin profile, impurity control, regulatory filings, and capacity flexibility.
- Risk maps and contingency playbooks covering trade policy, feedstock availability, and production bottlenecks — including supplier‑specific exposure analyses.
- Transaction and partnership playbooks for M&A, joint ventures, tolling agreements, and off‑take contracts, with indicative valuation ranges and negotiation levers.
- Commercial go‑to‑market templates for premium product positioning (parenteral/feed/food), including pricing frameworks and channel strategies.
To respect the “trailer” approach of this briefing, we have intentionally withheld granular regional and application split tables and certain proprietary scenario matrices. These details are included in the full report to subscribers and clients who require transaction‑grade intelligence.
Actionable 90‑Day Playbook for 2026
Companies that move decisively in Q1–Q2 2026 will improve their optionality for the remainder of the cycle. Our recommended near‑term actions:
- Initiate rapid supplier qualification audits for any single‑source histidine supply used in GMP processes; prioritize endotoxin and trace‑metal testing and secure validated COAs.
- Run a scenario stress test across at least three supply‑disruption cases (policy reversal, logistics blockade, feedstock shortage) and quantify margin and time‑to‑recover impacts.
- Pursue at least one strategic partnership or long‑term off‑take negotiation if your business depends on consistent high‑purity supply; structure deals with option clauses for capacity expansion.
- Identify cost‑to‑serve inefficiencies in your histidine supply chain (packaging, QC hold times, duty regimes) and implement two quick wins to reduce working capital tied to inventory.
- If you are a potential acquirer, shortlist regional producers with complementary GMP upgrades for bolt‑on consolidation; prioritize cultural fit and regulatory compliance records.
How to Use This Intelligence in Board and Investment Committees
Board discussions in 2026 should rebase long‑term forecasts to include the market’s steady CAGR and the strategic premium assigned to GMP‑grade supply. Use the following governance prompts:
- Approve a supply‑security capital allocation: clear thresholds for when to invest in inventory, tolling capacity, or equity stakes in upstream fermentation partners.
- Mandate a quarterly regulatory scan focused on supplier jurisdictions and raw‑material intermediates to detect policy risk early.
- Set commercial KPIs that differentiate performance on high‑purity product delivery (on‑spec rate, qualification lead time, customer complaint incidence) rather than purely price KPIs.
Final Note and Next Steps
The histidine market in 2026 is neither a simple commodity story nor a narrow life‑science niche; it is a hybrid market where process quality, regulatory compliance, and supply assurance create durable competitive advantages. Growth is predictable at a market level, but value capture will be uneven — favoring firms that translate technical differentiation and supply resilience into commercial contracts.
PW Consulting’s full Histidine Market Report contains the complete quantitative models, supplier scorecards, scenario analyses, and negotiation playbooks needed to operationalize the strategic directions outlined above. For clients preparing procurement, R&D, or M&A decisions in 2026, the full dataset and executable annexes are available via our research portal and advisory desk.
Contact PW Consulting to arrange a tailored executive briefing, obtain the full report, or commission a customized scenario analysis aligned to your portfolio and risk appetite.
For detailed analysis of this topic, please visit the official page: Histidine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com