

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Anatomical Models Market to Reach USD 1,363.52M by 2032 at 5.88% CAGR | PW Consulting

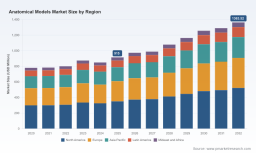
Anatomical Models Market — 2026 Strategic Primer (PW Consulting)
As PW Consulting’s Senior Strategy Advisor and Head Industry Analyst, I present a focused, decision-oriented introduction to our full Anatomical Models Market study. This piece is crafted as a “trailer”: it demonstrates the analytical depth and strategic framing that underpins the complete report while intentionally withholding the granular segment tables and proprietary scoring that corporate buyers need to act. Use this primer to align leadership priorities for 2026, then access the full study to execute with precision.
Anatomical Models Market
Concise market snapshot (what the numbers mean for strategy)
The anatomical models market has shown steady expansion over the last half-decade and continues its trajectory into the coming decade. On an aggregate basis (USD Million), the market rose from approximately 780.5 in 2020 to 915.0 in our base year of 2025. Under our central forecast (2026–2032), the market grows at a compound annual growth rate (CAGR) of 5.88%, reaching roughly 1,363.5 by 2032. The path between those points is instructive: the market has absorbed episodic shocks and supply-chain friction while being propelled by two structural forces—accelerating adoption of digital and additive manufacturing technologies, and a widening set of clinical and educational use-cases that monetize model sophistication.
Anatomical Models Market
For executives considering allocations in 2026, the headline numbers imply a market that is large enough to support multiple profitable plays, yet sufficiently fragmented to reward focused capability and channel strategies. The mid-single-digit CAGR both limits “get-rich-quick” expectations and creates durable upside for players that capture premium pricing via clinical validation, reimbursement capture, or platform-enabled services.
Anatomical Models Market
Why the study matters for 2026 decision cycles
- Capital allocation: The report translates market growth into investment horizons—identifying which product classes and business models return acceptable IRR within a 3–5 year window under conservative adoption scenarios.
- Portfolio prioritization: It grades product types and go-to-market routes by clinical value, procurement friction, and regulatory complexity, enabling portfolio rationalization without abandoning long-term adjacencies.
- Regulatory and reimbursement roadmap: With recent regulatory shifts and evolving CPT coverage, the study identifies the timing and activities required to unlock clinical reimbursement and payer-negotiated pricing.
- Partnership vs build decisioning: We quantify when to partner with digital/3D-printing specialists or to internalize manufacturing—linking unit economics with certification costs and time-to-market.
What the full report delivers (practical, action-oriented modules)
- Market sizing and scenario engine — top-line and demand drivers across 2020–2032 with interactive sensitivity levers (price, adoption, policy) tailored for financial modeling.
- Go-to-market playbooks — step-by-step route maps for educational distributors, hospital procurement, and device companies seeking to commercialize patient-specific models.
- Regulatory & reimbursement playbook — pathway templates for 510(k) and ISO 13485 alignment, CPT capture strategies, and payer engagement sequencing.
- Technology adoption matrix — assessment of additive manufacturing, digital-native virtual anatomy, and hybrid physical-digital propositions with cost curves and time-to-scale benchmarks.
- Competitive positioning and M&A screening — profiles, capability-synergy scoring, and acquisition heat maps aligned to three strategic archetypes: platform owners, clinical validation specialists, and commoditized suppliers.
- Supply-chain risk & cost analysis — material cost-band analysis, capacity risk heatmaps, and recommended nearshoring vs centralized production strategies.
- Commercial playbooks — pricing architecture, channel economics, and pilot KPIs designed to accelerate hospital adoption and institutional curricula procurement.
Competitive landscape — reading between the logos
The market’s concentration metrics point to a moderately consolidated field: the top three players capture below half of global revenue (CR3 ≈ 48.5%), and the top five near 60% (CR5 ≈ 59.2%). This structure creates clear strategic implications: there is room for differentiation through clinical validation and vertical integration, but scale matters for institutional tenders and global distribution.
- 3B Scientific (Hamburg) — A legacy leader in durable educational models. Strengths: breadth of catalog, brand recognition in academia, and high-quality plastic and 3D-printed offerings. Strategic priority: move beyond catalog sales into subscription educational platforms and clinical simulation bundles.
- ERLER-ZIMMER (Germany) — Known for life-like, bone-mimetic products. Strength: material authenticity and specialist prosthetic/orthopedic interfaces. Strategic priority: translate product realism into surgical training partnerships and certification-linked curricula.
- GPI Anatomicals (US) — Strong US classroom and clinical presence through realistic synthetic models. Strength: channel relationships with medical schools. Strategic priority: develop service add-ons (customization, repair) to increase lifetime customer value.
- Nasco Healthcare & Anatomy Warehouse (US) — Broad retail and institutional distribution. Strength: assortment and fulfillment. Strategic priority: capture data from institutional purchases to build recurring-service offerings and targeted bundles.
- Sawbones & Simulaids (US) — Surgical training and simulation specialists. Strength: clinical fidelity and simulation integration. Strategic priority: leverage partnerships with device OEMs for co-developed procedural trainers.
- Laerdal (Norway) — Simulation leader with deep clinical-training relationships. Strength: integration into professional resuscitation and simulation programs. Strategic priority: embed anatomical models as part of comprehensive simulation curricula and managed training services.
- 3D Systems & Stratasys (additive leaders) — Pioneers in 3D-printed anatomical models and surgical planning. Strength: printing technology and clinical use-cases for patient-specific models. Strategic priority: commercialize end-to-end surgical planning services and validate economic impact through clinical studies.
- Anatomage (digital) — Virtual dissection and digital anatomy platforms. Strength: digital-first educational models and strong institutional uptake. Strategic priority: hybridize with physical models to offer multi-modal learning pathways.
Across the competitive set, successful players are converging on three differentiators: clinical validation (peer-reviewed outcomes), regulatory-compliant manufacturing capability, and channel control (direct ties to hospitals and curricula). The immediate battleground in 2026 is therefore hybridization—bundling physical models with digital planning, simulation, or managed-service delivery.
Regulatory, reimbursement and technology dynamics that change the math in 2026
- Regulatory easing: The FDA’s April 2025 update reduced barriers for patient-specific 3D-printed anatomical models and surgical guides. This materially shortens time-to-clinical rollout for companies that can operationalize quality systems (ISO 13485) quickly.
- Reimbursement windows: Patient-specific models are being reimbursed through Category III CPT mechanisms; reimbursement levels and payer uptake vary. Strategy: prioritize pilot evidence packages that map model use to measurable OR efficiencies to justify payer negotiations.
- Material economics: Low-cost 3D printing commonly uses PLA, ABS, and Nylon with production cost bands between roughly $0.05–$0.33 per unit depending on method and scale. Strategy: realize margin through post-processing, certification, and bundled clinical services rather than competing solely on raw print cost.
- Certification regimes: Models intended for diagnostic or procedure-planning use require 510(k) clearance and ongoing Class II compliance in many markets—this is non-negotiable for clinical adoption and payer reimbursement.
Notable industry moves underscore these dynamics: several vendors launched new training modules in mid‑2026, while dominant 3D printing vendors initiated clinical studies and secured 510(k) clearances. These actions both validate the clinical pathway and raise the bar for new entrants.
Strategic playbook — prioritized actions for leadership teams in 2026
- Accelerate clinical evidence generation. Fund a small number of high‑ROI, multicenter pilots that measure OR time-savings, complication reduction, or training proficiency—this data is the fastest route to reimbursement and premium pricing.
- Lock in regulatory readiness. Invest in ISO 13485 and prepare 510(k) dossiers for any model positioned for diagnostic or procedural guidance use. Time to certification is now a gating factor for scale.
- Choose the right manufacturing posture. Use a hybrid model: outsource commodity production while internalizing post-processing and validation for clinical-grade models to protect margins and speed-up regulatory workflows.
- Forge channel and OEM partnerships. Partner with simulation centers, device OEMs, and digital anatomy platforms to create integrated offerings that buyers prefer and that competitors cannot easily replicate.
- Price for outcomes. Shift from unit pricing to value-anchored pricing where possible—subscription-based curricular access, pay-per-case surgical planning, and training-as-a-service models yield higher lifetime value and stickiness.
- Screen M&A opportunistically. Target capabilities that close gaps—clinical validation partners, digital platforms, and certified additive production facilities that can be integrated quickly.
Next steps — how to use the full PW Consulting study
This primer is a directional resource designed to align strategy conversations for 2026. The full PW Consulting Anatomical Models Market report contains detailed segmentation, proprietary scoring of subsegments and geographies, supplier scorecards, model-level profitability simulations, and an interactive scenario engine. Because this preview intentionally omits those granular tables and commercial scorecards, senior leaders and strategy teams should consult the full report to obtain:
- Segment-level growth curves and elasticity assumptions needed for investment approval packages;
- Go-to-market blueprints with channel economics by buyer type;
- M&A target lists ranked by integration complexity and synergies;
- Regulatory timeline templates mapped to product classes and market launch milestones.
PW Consulting’s complete study is the tactical tool for turning the market’s favorable macro trajectory into executable, revenue-producing plans in 2026. If your team is allocating capital, reshaping product portfolios, or preparing to compete for clinical adoption, this report is built to be the operating manual for the next 18–36 months.
For access to the full data tables, segment-level analysis, and the interactive scenario engine referenced here, please follow the link provided in the PW Consulting distribution or contact our research desk to schedule a briefing.
For detailed analysis of this topic, please visit the official page: Anatomical Models Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com