

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Methyl Mercaptan Market to Reach USD 225 Million by 2032 at 6.5% CAGR

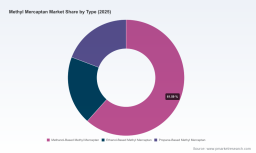
Methyl Mercaptan Market — Strategic Briefing for 2026 Decision‑Makers
As companies calibrate portfolios and supply chains for the next strategic planning cycle, the Methyl Mercaptan market presents a compact but consequential opportunity set. PW Consulting’s latest study — anchored on a 2025 base year and projecting across 2026–2032 — synthesizes historical performance (2020–2025) with scenario-based forecasts. The market is expected to expand at a steady compound annual growth rate (CAGR) of approximately 6.5%, rising from a mid‑triple‑digit million USD base in 2025 toward materially higher levels by 2032. For executives evaluating investments, procurement strategies, or M&A in 2026, the analysis delivers actionable context on demand drivers, supply dynamics, price tailwinds and regulatory constraints that will shape near‑term returns and operational risks.
Methyl Mercaptan Market
Why this market matters in 2026
-
Strategic intermediation role: Methyl Mercaptan functions as a critical intermediate in animal nutrition (notably methionine synthesis) and selected petrochemical routes. Its modest market size belies outsized importance to downstream margin profiles for feed additive and specialty chemical players.
Methyl Mercaptan Market -
Supply sensitivity: Production chemistry ties the molecule closely to methanol and hydrogen sulfide feedstock availability and pricing, creating a direct channel through which methanol market volatility transmits to producers and buyers.
Methyl Mercaptan Market -
Regulatory and safety overlay: Stringent hazard classification and reporting thresholds create operational barriers and capital obligations for storage, handling and transport. Compliance costs and permitting timelines become strategic determinants for new capacity and sourcing decisions.
Key macro takeaways from the forecast
-
Resilient growth at scale: The report’s base‑year calibration (2025) and projection window show an unequivocal growth trajectory through 2032, supporting investment cases that hinge on steady, not speculative, demand expansion.
-
Cost and margin sensitivity: Because Methyl Mercaptan is commonly produced by the reaction of hydrogen sulfide with methanol, methanol price movements are a first‑order input risk. For example, methanol spot prices in China reached 3,108 CNY/T on June 3, 2026, underscoring the potential for input cost shocks to compress margins or re‑route trade flows.
-
Compliance as capital: The chemical is captured under multiple U.S. regulatory frameworks — including the CAA 112(r) Risk Management Program (threshold quantity 500 lb) and OSHA’s toxic substance standards (permissible exposure limit 0.5 ppm) — while RCRA lists it as hazardous waste with a reportable quantity threshold (100 lb). These constraints translate into predictable compliance spend and can create localized supply tightness where enforcement or permitting is intensified.
What the PW Consulting report delivers (practical, boardroom‑ready outputs)
-
Transparent market sizing and growth scenarios — including baseline, upside and downside pathways calibrated to feedstock price, downstream methionine demand and regulatory shock scenarios.
-
Supply chain heatmaps — supplier concentration, choke‑point analysis, and contingency sourcing routes for short‑term outages.
-
Price‑pass‑through and margin modeling — plant‑level economics that stress methanol, utilities and environmental compliance costs to produce buyer/seller breakevens.
-
Regulatory playbook — a compliance checklist, permitting timelines and CAPEX guidance tied to storage, monitoring and emergency response requirements.
-
Commercial templates — contract clauses for volatility pass‑through, force majeure formulations tailored to hazardous chemical logistics, and benchmarking tables for long‑term offtake vs spot procurement.
-
Scenario planning and decision trees — for market entry, expansion, or exit choices, including NPV sensitivity to feedstock and regulatory variables.
-
Supplier scorecards and M&A vantage points — capability matrices that assess production scale, product purity grades, geographic coverage and counterparty risk.
Competitive landscape — implications for 2026 strategies
-
Chevron Phillips Chemical Company (The Woodlands, TX) — As the largest‑volume producer in the market, Chevron Phillips commands advantages in scale, integrated feedstock access and global distribution capability. For buyers, contracting with a scale player can secure volume and reliability but may be priced at premium for integrated supply. For investors, market leadership brings potential to monetize by expanding specialty grades or entering tolling arrangements.
-
Arkema S.A. (Colombes, France) — Arkema’s Thiochemicals platform offers high‑purity grades and alternative product forms (e.g., sodium methyl mercaptide) that serve methionine producers. Arkema’s strengths are in product differentiation, regulatory compliance and close integration with specialty downstream customers — attractive traits for strategic partners seeking quality and traceability.
-
Evonik Industries AG (Essen, Germany) — Evonik’s specialty portfolio positions it to focus on high‑value applications in animal nutrition and chemical synthesis. Its value proposition is predicated on technical service, consistent quality and the ability to navigate regulatory regimes — a competitive moat for customers who prioritize performance over commodity pricing.
-
Vizag Chemical International (Visakhapatnam, India) and Triveni Interchem Private Limited (Valsad, Gujarat, India) — These Indian producers serve both domestic and export markets and underline the geographic diversification of supply. Their presence signals a pool of competitively priced supply, albeit accompanied by considerations on logistics, product specification compatibility and evolving compliance standards in destination markets.
Strategic implications and recommended actions for 2026
-
Procurement & commercial strategy — Move from spot‑only to hybrid procurement: combine shorter‑cycle spot buys with indexed long‑term contracts that include methanol‑linked price formulas and defined pass‑through triggers. Ensure contracts include environmental compliance warranties and clear liability allocation for regulatory events.
-
Feedstock hedging — For producers or integrated downstream firms, establish methanol hedging programs or secured feedstock agreements to protect margins against price spikes. Evaluate tolling arrangements where feedstock risk is borne by counterparties with hedging capability.
-
CapEx and site strategy — Given the regulatory thresholds and permitting timelines, prioritize retrofits and capacity expansions at sites with pre‑approved land use and mature emergency response infrastructure. New greenfield projects should factor compliance CAPEX and extended lead times into investment models.
-
Partnerships and vertical plays — Consider strategic alliances with methionine producers or forward integration to capture downstream value, particularly where quality or supply security creates a competitive advantage for buyers.
-
Risk management — Build an incident‑ready operating model (monitoring, reporting, emergency response) to reduce RMP risk and limit business interruption. Documented compliance and rapid response capabilities can materially affect insurance costs and permit approvals.
-
M&A and portfolio optimization — Use the market’s modest scale and supplier diversity to pursue bolt‑on acquisitions that add product grades, fill geographic gaps or bring regulatory‑compliant capacity. Prioritize targets with established QA/QC, logistics capability and contractual anchors.
Regulatory and operational noise to watch
-
Production chemistry remains central: commercial manufacturing commonly proceeds by reacting hydrogen sulfide with methanol (NOAA CAMEO Chemicals, 2026). This linkage means that shifts in methanol supply, policy‑driven feedstock availability or sulfur management programs will ripple through the market.
-
Regulatory trigger points are tight: the substance is regulated under multiple frameworks — CAA 112(r) RMP threshold 500 lb, OSHA exposure limits at 0.5 ppm, and RCRA reportable quantities — making compliance a non‑negotiable element of any operational plan.
-
Price volatility is tangible: as illustrated by recent methanol spot levels in China (3,108 CNY/T, June 3, 2026), volatile upstream markets can rapidly alter competitiveness between suppliers and geographies.
How PW Consulting’s study supports boardroom action in 2026
-
It converts macro forecasts into executable options: balancing growth scenarios against feedstock and regulatory sensitivities to produce prioritized, costed strategic options.
-
It shortens decision cycles: ready‑to‑use commercial templates, supplier scorecards and CAPEX checklists let procurement and BD teams execute pilots and negotiations within months, not quarters.
-
It protects downside: by integrating regulatory, environmental and price risk into valuation models, the study helps avoid underestimating compliance costs or overpaying for exposed capacity.
PW Consulting’s full report contains the granular segmentation, supplier profiles, pricing matrices and scenario worksheets that underpin the insights summarized here. This briefing is intended to orient 2026 strategic priorities and surface the high‑impact levers; to access the comprehensive datasets, proprietary modeling and tactical annexes that support transaction‑level decisions, review the complete report on our site or contact our advisory team for a tailored briefing.
For detailed analysis of this topic, please visit the official page: Methyl Mercaptan Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com