

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Baby Diaper Rash Cream Market to Reach USD 280.95M by 2032 (CAGR 5.75%)

Baby Diaper Rash Cream Market — Strategic Preview for 2026 Decisions
This briefing is crafted by PW Consulting’s senior strategy team as an executive “trailer” for our full Baby Diaper Rash Cream Market study. It synthesizes the report’s highest‑value, decision‑relevant insights for corporate leaders preparing strategic moves in 2026 — while intentionally withholding detailed segment tables and proprietary splits to encourage access to the full research. The summary below demonstrates our analytical depth and the kinds of actionable recommendations embedded in the complete report.
Baby Diaper Rash Cream Market
Market Snapshot and Growth Trajectory
The baby diaper rash cream market has shown consistent expansion through the first half of the decade. Measured on a comparable basis (USD, revenue unit: Million), the market grew from a mid‑hundreds base in 2020 to approximately USD 190.5 Million in 2025, reflecting steady demand across mature and emerging channels. Our forecast assumes a compound annual growth rate (CAGR) of 5.75% over the 2026–2032 horizon, with the total addressable market expected to exceed USD 280 Million by the end of the forecast period under baseline assumptions.
Baby Diaper Rash Cream Market
That pace of growth signals a market large enough to support both multinational scale plays and nimble specialist brands. Key structural drivers are persistent: population and birth‑rate patterns where relevant, premiumization (parents trading up to clinically backed and “clean” formulas), channel diversification (omni‑channel mix including digital direct‑to‑consumer), and regulatory evolution that reshapes formulation economics.
Baby Diaper Rash Cream Market
Why This Study Matters for 2026 Strategy
- Regulatory inflection points: Compliance developments are about to alter formulation and supplier qualification costs; firms that proactively adapt formulations and supply chains will avoid disruption and can capture first‑mover trust advantages.
- Input cost concentration: Zinc oxide and specialty emollients remain the primary raw material cost drivers. Strategic procurement, dual‑sourcing and formulation engineering are core levers to protect margins.
- Product differentiation: Innovations in barrier technology, incorporation of ceramides, and the “clean/organic” positioning create premium pricing windows. Understanding which formulations win in which channels is essential to portfolio prioritization.
- Channel economics and customer acquisition: Online channels and pharmacy channels exhibit distinct unit economics and regulatory/marketing constraints; your 2026 channel playbook must be calibrated to these differences.
- Moderate market concentration: The market exhibits a mid‑level concentration — sufficient room for challengers to scale, but large incumbents can defend share via distribution and R&D investment. Our CR3 and CR5 measures (provided in the full report) quantify these dynamics and inform M&A thresholds.
Regulatory and Supply‑Chain Dynamics to Watch in 2026
The sector is shaped by both legacy and emerging regulation. Two items are particularly critical for 2026 planning:
- Regulatory limits and format bans create formulation constraints across jurisdictions. For example, maximum allowable zinc oxide concentrations and format restrictions vary by jurisdiction and directly affect product claims and manufacturing recipes.
- Pharmacopeial harmonization actions that take effect in 2026 introduce new testing obligations for petroleum‑based inputs, elevating compliance costs and supplier qualification timelines. Firms must map supplier certification pipelines and factor additional QA testing lead time into launch schedules.
From a procurement perspective, these developments shift risk from “commodity supply” to “qualified supply” — suppliers who can demonstrate compliant low‑PAH profiles and consistent zinc oxide quality will command a premium. Our full study offers a supplier risk heat map and a staged remediation playbook for procurement teams.
Competitive Landscape — What the Leading Players Are Doing
The competitive field combines global consumer goods leaders, regional specialty players, and fast‑growing natural/organic niche brands. The full report provides company‑level benchmarking; below are high‑level positioning observations on the most strategically relevant names:
- Johnson & Johnson (New Brunswick, NJ — https://www.jnj.com/) : Leverages deep pediatric credibility and broad distribution reach. Their play emphasizes clinically validated barrier creams and heavy investment in caregiver education programs. Watch for SKU rationalization toward clinically differentiated SKUs.
- The Procter & Gamble Company (Cincinnati, OH — https://www.pg.com/) : Uses scale in supply chain and retailer relationships to optimize cost structures and promotional cycles. Innovation focus is on multi‑benefit formulations that simplify parenting routines.
- Beiersdorf AG (Hamburg, Germany — https://www.beiersdorf.com/) : Known for dermocosmetic expertise and measured premiumization. The firm blends consumer trust with clinically framed claims and a pathway into pharmacy channels in key markets.
- Unilever (London, UK — https://www.unilever.com/) : Applies brand marketing muscle and reformulation capacity to pursue sustainability and “clean” product trends, with an eye to scale economics across adjacent baby care categories.
- The Honest Company (El Segundo, CA — https://www.honest.com/) and other clean‑beauty specialists (e.g., Babo Botanicals, Earth Mama, Weleda, Burt’s Bees): These brands capitalize on ingredient transparency and e‑commerce-first distribution to win premium shoppers, especially in markets sensitive to “organic” claims.
- Specialist formulators (e.g., Sebapharma, Himalaya, Desitin): Often differentiated by clinical rituals or heritage formulations. Notably, Desitin introduced a triple‑action cream in January 2025 combining zinc oxide and ceramide technology — a strong signal that incumbents are layering barrier science onto legacy ingredients to regain product lifecycle momentum.
Collectively, the market dynamics signal opportunity for both offensive moves (product differentiation, targeted channel expansion) and defensive plays (supply continuity, regulatory readiness). Our competitive profiles include go‑to‑market matrices, R&D intensity scores, and retailer promotion elasticity estimates.
What the Full Report Contains — Practical Deliverables
- Detailed market size history (2020–2025) and scenario‑based forecasts to 2032 with sensitivity to raw material and regulatory shocks.
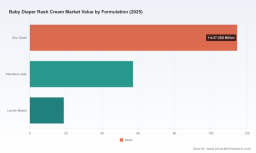
- Segmentation analysis across formulation, distribution channels and end‑uses with actionable decision rules for SKU prioritization (note: detailed segment tables withheld in this public preview).
- Supplier and input cost heat maps, including a zinc oxide & emollient supplier directory and sample long‑term purchase contracts for different exposure levels.
- Regulatory compliance checklist and implementation timelines aligned with pharmacopeial changes effective in 2026 and beyond.
- Competitive benchmark dashboards, innovation pipelines, and a prioritized M&A target list based on capability gaps and channel access.
- Go‑to‑market playbooks and three investor-ready case studies (premiumization, cost‑leadership, DTC scale‑up) with P&L models and payback mechanics.
How Executives Should Use This Research in 2026
- Portfolio decisions: Use our formulation demand matrix to retire underperforming SKUs and redirect R&D to barrier technologies that command higher margin and lower regulatory friction.
- Supply‑chain redesign: Reassess supplier qualification programs now to meet pharmacopeial testing requirements and secure long‑lead zinc oxide contracts where appropriate; consider co‑investing in supplier testing capacity to shorten lead times.
- Commercial targeting: Apply the channel economics model to optimize promotional spend between pharmacy, mass retail and e‑commerce, and to tailor packaging/claims per channel risk tolerances.
- M&A and partnerships: Use the industry concentration metrics and our M&A scorecard to identify bolt‑on targets that either accelerate entry into premium segments or shore up pharmacy channel penetration.
- Regulatory hedging: Prepare contingency plans for market‑specific ingredient constraints and format restrictions; early adaptation will provide a competitive advantage in markets where limits are tighter.
Closing — The Strategic Window in 2026
By 2026 the baby diaper rash cream market will reward firms that combine formulation science, regulatory foresight, and channel discipline. The growth runway is meaningful — our baseline forecast shows mid‑single‑digit CAGR expansion through 2032 — but the path to profitable scale requires proactive navigation of raw material economics and compliance requirements. PW Consulting’s full report equips decision‑makers with the granular metrics, risk maps, and implementation playbooks necessary to convert market momentum into durable advantage.
Access to the complete dataset, proprietary segment splits, and the tactical playbooks referenced here is available through PW Consulting’s report portal. For tailored briefings or to license the dataset for corporate planning, contact our industry team.
For detailed analysis of this topic, please visit the official page: Baby Diaper Rash Cream Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com