

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Soy Sauce Market to Hit USD 59.3B by 2032, Growing at 5.4% CAGR

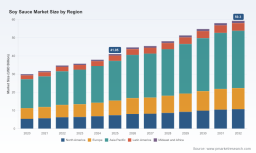
Soy Sauce Market 2026: Strategic Signals for Decision-Makers
As food companies, ingredient buyers, private equity sponsors, and strategic planners finalize roadmaps for 2026, the soy sauce category is moving from incremental growth to structurally new opportunity sets. PW Consulting’s latest Soy Sauce Market study (base year 2025) synthesizes macro trajectory, supply-chain stress tests, regulatory inflection points, and competitor positioning into an actionable intelligence package designed to shape commercial and capital-allocation choices through the next planning cycle.
Soy Sauce Market
Why this report matters for 2026 decision cycles
Many executives treat soy sauce as a stable, low-margin ingredient—yet the market’s evolution over the 2020–2025 period and the outlook into 2026–2032 reveal a more nuanced picture. The category has expanded meaningfully in aggregate and is projected to continue a steady compound annual growth path (CAGR ~5.4%) over the forecast window. That growth is not uniform: premiumization, regional demand shifts, and channel dynamics (retail, industrial food processors, and foodservice) are creating pockets of outsized margin and strategic leverage.
Soy Sauce Market
For boards and business-unit leaders preparing budgets, supply contracts, or M&A pipelines in 2026, the report translates aggregate market direction into practical options: where to invest in capacity, how to protect margin against raw-material volatility, which go-to-market models unlock scale in adjacent condiments, and which regulatory regimes create hidden friction or arbitrage. Crucially, the study demonstrates how modest changes in input cost, labeling rules, or distribution partnerships can amplify into material P&L outcomes across typical time horizons used in corporate planning.
Soy Sauce Market
Market trajectory and what the headline numbers imply
The soy sauce category has grown from a stable base in the early 2020s to a substantially larger global market by 2025, with our base-year assessment reflecting that uplift and supporting a confident forecast into 2032. At the core, the mid-single-digit CAGR formalizes a market where organic consumer trends—premium naturally-brewed offers, ethnic cuisine penetration, and convenience-led formats—intersect with industrial demand from processed foods. From a strategic perspective, the headline growth smooths short-term variability but does not eliminate strategic inflection points; rather, it raises the value of timing investments to capture premiumization and channel migration.
For executives, the practical takeaway is twofold: preserve optionality to capitalize on the premium and foodservice upcycles, and embed cost-mitigation playbooks within sourcing and pricing strategies so margin is protected across commodity cycles.
Competitive landscape — how incumbents are shaping the next phase
The market architecture blends large, tradition-rooted manufacturers, regional champions, and specialty micro-producers. Each group is pursuing differentiated routes to growth and risk mitigation:
- Kikkoman Corporation : A global leader in traditionally brewed soy sauce, Kikkoman continues to de-risk supply-chain exposure to trans-Pacific logistics with expanded U.S. production. The commissioning of a new U.S. facility and the planned initial shipments in late 2026 materially shift its North American footprint and shorten time-to-market for multiple channels. Expect Kikkoman to exploit that capacity for both retail scale and customized industrial blends.
- Foshan Haitian and Pearl River Bridge : Large Chinese producers maintain broad distribution in domestic and export markets, using manufacturing scale to optimize cost and to supply food processors at volume. Their playbook centers on price competitiveness and route-to-market density in Asia and select export corridors.
- Lee Kum Kee and Yamasa : These producers emphasize premium positioning—naturally brewed profiles, heritage branding, and global retail placements. Their investments focus on brand equity, certification, and incremental innovation (e.g., flavor-variant extensions) to sustain price premiums.
- Shibanuma and regional specialists : Traditional Japanese manufacturers leverage provenance and quality narratives to support export niches and high-margin foodservice partnerships.
- Bourbon Barrel Foods and niche microbrewers : Specialist producers are carving premium micro-segments by using novel maturation techniques and limited-batch runs—strategies that command high unit prices and strong margin but limited scale.
For investors and corporate strategists, the competitive implication is clear: scale players preserve cost advantage and channel access, while premium and specialty players drive margin expansion and brand differentiation. The optimal corporate response depends on whether the objective is share-weighted growth, margin capture, or a hybrid roll-up model.
Supply chain, raw-materials, and margin resilience
Soybeans remain the primary cost driver in the ingredient chain. Commodity-price movements and regional crop outcomes create episodic elevating pressure on manufacturers’ cost base. Our analysis models multiple scenarios where soybean-price trajectories and freight dynamics produce divergent margin outcomes across private-label, branded-retail, and industrial contracts.
Key operational levers in those scenarios are: forward commodity procurement (including multi-year fixed-price contracts), ingredient substitution and blend optimization where formulation allows, and targeted automation in fermentation and packaging to reduce unit conversion costs. Companies that centralize procurement intelligence and use hedging selectively tend to maintain pricing discipline without ceding category share.
Regulatory and trade dynamics that will alter 2026 choices
Regulatory nuance is a persistent source of operational complexity and commercial opportunity. Several salient points in the study that require board-level attention:
- Labeling regimes vary materially across markets. Some jurisdictions require GMO disclosure for deeply processed products, while others do not treat soy sauce as subject to mandatory GMO labeling—creating asymmetry that affects packaging strategies and cross-border SKU rationalization.
- Nutritional labeling requirements can differ for condiments; in certain export markets, soy sauce benefits from exemptions that simplify compliance, while in others additional nutrition or ingredient declarations are required.
- Trade policy, tariff schedules, and sanitary standards influence the economics of exporting bulk soy sauce versus establishing local production. Recent capacity investments by major players reflect a strategic preference for onshore production to mitigate these frictions.
From a strategic standpoint, companies should integrate regulatory scenarios into SKU design and packaging decisions now—waiting until late 2026 to react will widen compliance costs and slow market response.
What the PW Consulting report delivers — practical, transaction-ready content
We designed the full research product to be a toolset, not just a narrative. Highlights include:
- Demand modeling calibrated to recent historicals and forward scenarios (2026–2032) with sensitivity to commodity and channel variables.
- Supply-side heat maps identifying logistics pinch points, capital intensity of fermentation capacity, and brownfield vs greenfield economics.
- A regulatory matrix comparing labeling, food-safety, and tariff regimes for priority markets, together with recommended compliance workflows.
- Commercial playbooks for premiumization, private-label optimization, and co-manufacturing partnerships—complete with margin waterfall templates and pricing cadence recommendations.
- M&A and J‑curve guidance for roll-up strategies in premium and regional niches, including integration checklists and a prioritization framework for targets.
- Early-warning indicators and a quarterly “watchlist” of eight leading signals to track during 2026 so management can re-calibrate tactically.
Each deliverable is accompanied by executable templates—term-sheet language, sourcing-RFP structures, and pilot-design experiments—so teams can move from insight to implementation on a 90–180 day cadence.
Five strategic actions to consider for 2026
- Secure optionality in sourcing: Combine short-duration hedges with multi-supplier frameworks and conditional forward contracts so procurement can flex with market swings without locking out upside.
- Prioritize route-to-market segmentation: Separate product lines and commercial teams for premium, industrial, and value private-label to prevent margin dilution and to tailor commercial terms appropriately.
- De-risk logistics with near-market capacity: Evaluate brownfield investments or tolling partnerships in priority import markets to mitigate freight and tariff exposure; monitor competitor facility rollouts for second-order capacity impacts.
- Explore value-added formats and services: Invest in differentiated SKUs, co-branded ingredient solutions, and technical support for food processors—these moves convert a commodity into a service proposition and justify premium pricing.
- Embed regulatory scenario planning: Establish cross-functional playbooks for labeling and trade policy shifts so product changes can be executed in weeks, not months.
How to use the intelligence in 2026 planning cycles
Executives should treat this report as an operational annex to their 2026 planning. Use the demand scenarios to stress-test sales targets, the procurement guidance to size working capital buffers, and the M&A framework to prioritize targets that close capability gaps (e.g., premium fermentation know-how or regional distribution). The report’s tactical templates empower commercial teams to convert insights into executable pilots within a single quarter.
Final note — the strategic confidence gap
Our clients often ask: “If the market is growing at a steady clip, why does it feel risky?” The answer is that steady aggregate growth masks structural divergence: rising premium demand, evolving regulatory regimes, and supply-side realignment driven by near-market capacity decisions. That divergence creates both upside opportunity for those who act early and execution risk for those who assume “more of the same.”
PW Consulting’s Soy Sauce Market study is intentionally structured as a decision-support engine: it reveals the strategic levers, quantifies upside and downside scenarios at an aggregate level, and supplies operational templates to convert insights into measurable outcomes. To preserve the competitive integrity of the most actionable segment-level intelligence and detailed scenario matrices, the full dataset and playbooks are available on the report portal.
For executives preparing budgets, negotiating supply agreements, or evaluating M&A in 2026, the time to act is now. Access the complete study to see the granular segment analytics, regional forecasts, and detailed competitor dossiers that will underpin decisive moves in the coming planning cycle.
For detailed analysis of this topic, please visit the official page: Soy Sauce Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com