

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Plasma Sterilizers Market Outlook — 6.1% CAGR to 2032

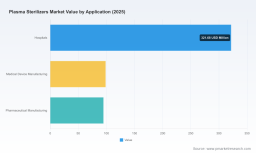
Plasma Sterilizers Market: Strategic Outlook and Decision Framework for 2026
As hospitals, device manufacturers and pharmaceutical producers accelerate plans to modernize sterilization workflows for heat- and moisture-sensitive instruments, plasma sterilization has moved from niche application to procurement priority. PW Consulting’s latest market study, anchored on a 2025 base year and projecting through 2032, quantifies this transition and translates it into practical decision levers for executives planning their 2026 strategies.
Plasma Sterilizers Market
Market snapshot: growth trajectory you can bank on
The global plasma sterilizers market has demonstrated steady expansion over the past half-decade, rising from an estimated USD 350.0 Million in 2020 to USD 515.0 Million in 2025. Our forecast projects continued growth across the 2026–2032 horizon, with the market expected to reach approximately USD 775.4 Million by 2032 at a compound annual growth rate (CAGR) of 6.1% (base year 2025). Notably, available figures for 2026 show the market climbing to roughly USD 563.2 Million — a practical anchor for budget planning and capacity decisions in the coming fiscal year.
Plasma Sterilizers Market
Why this matters for corporate decision-making in 2026
- Timing of investment: Mid-single-digit CAGR with accelerating absolute value means 2026 is a pivotal year to commit to capital and R&D investments if market share gains are a strategic objective. Early movers who align product cycles and service rollouts with 2026 procurement budgets will capture disproportionate share as hospital CAPEX resumes.
- Regulatory alignment as a commercial moat: Recognition of ISO 22441:2022 for low-temperature vaporized hydrogen peroxide validation by the FDA, together with CDC/FDA classification of hydrogen peroxide gas plasma as an Established Category A method, has raised the bar for validated systems. Companies that embed regulatory compliance into product development and documentation gain real-world time-to-contract advantages with large health systems and device OEM partners.
- Validation-driven purchasing: Recent device-specific clearances (notably FDA 510(k) actions in 2024–2025) are reshaping buyer requirements. Procurement teams increasingly demand sterilizers validated for specialized reprocessing tasks (e.g., duodenoscope workflows), which affects specification sheets, service bundles, and training obligations.
Dynamics shaping the near-term competitive landscape
- Standards and regulatory momentum: Formal convergence around ISO 22441:2022 as the reference for vaporized hydrogen peroxide sterilization validation reduces ambiguity for clinical engineering teams and accelerates adoption in regulated environments. Expect validation packages and routine control documentation to become de facto commercial differentiators.
- Clinical and device OEM partnerships: Collaborations between sterilizer vendors and device manufacturers (notably in endoscope reprocessing) are becoming transaction multipliers. Compatibility clearances and co-developed cycles shorten purchasing cycles for health systems and create locked-in service revenues for the sterilizer supplier.
- Service and consumables economics: As the installed base grows, the lifetime value of each sterilizer increasingly depends on service contracts, consumable sales, and software-enabled uptime guarantees. Strategic pricing models moving beyond one-time equipment sales toward outcome-based uptime or sterilization-per-procedure arrangements will reshape margins.
- Market concentration and implications: The market exhibits measurable concentration among a handful of established players (our analysis finds that the top three and five providers account for a meaningful portion of revenue). This concentration creates both entry barriers for newcomers and M&A opportunities for firms seeking scale effects in distribution, service, and regulatory know-how.
Competitive landscape — profiles and strategic posture
PW Consulting’s review focuses on several incumbent and specialist players whose strategies set the tempo for the sector. Below we synthesize their strategic positioning and near-term implications for partners, competitors and buyers.
Plasma Sterilizers Market
- Advanced Sterilization Products (ASP) — Irvine, CA: ASP’s STERRAD platform has recently expanded its regulatory footprint through a 510(k) clearance in April 2025 for the STERRAD 100NX with ALLClear Technology, and earlier collaborations have validated specialized cycles for endoscope reprocessing. ASP’s strengths are product breadth, strong clinical relationships, and a track record of securing device-specific clearances — all of which support premium positioning in hospital procurement.
- Tuttnauer — Breda, Netherlands: Known for the PlazMax line, Tuttnauer targets sterilization of heat- and moisture-sensitive instruments. Its European heritage and established global distribution network give it advantages in cross-border tenders and multi-site rollouts. For partners evaluating distribution or service agreements, Tuttnauer’s installed base and product validation approach are key considerations.
- Steris Corporation — Warrendale, PA: With the V-PRO family, Steris competes on enterprise-grade service, global support infrastructure, and integration into hospital sterilization ecosystems. Steris’ strength lies in enterprise contracts and the ability to bundle sterilizers with comprehensive validation and training programs.
- Plasmapp — Seoul, South Korea: Plasmapp’s STERLINK line, including FDA-cleared configurations, positions it as an agile supplier with an emphasis on compact, validated sterilizers. Its geographic origin and innovation cadence make it a candidate for OEM partnerships and targeted expansion in high-growth markets.
- VetOvation — United States: Specializing in veterinary applications, VetOvation highlights a profitable adjacent market. Veterinary clinics represent an under-penetrated segment that can serve as a rapid-access testbed for new service models and consumable pricing strategies.
Strategic moves that will define winners in 2026
- Regulatory-first product roadmaps: Prioritize product cycles that incorporate ISO 22441:2022 validation from the design stage. This reduces time-to-contract, minimizes rework during audits, and supports premium pricing.
- Endoscope OEM alliances: Secure compatibility and co-validation agreements with major endoscope manufacturers. These partnerships materially shorten procurement cycles for hospitals and create sticky service ecosystems.
- Service-led monetization: Transition go-to-market models from transactional equipment sales toward bundled service, consumables, and outcome guarantees. Scenario modeling in our report shows service revenue materially increases lifetime gross margin.
- M&A and distribution consolidation: Use targeted acquisitions to gain validation expertise, regional distribution, or service capability — especially in geographies where establishing a full service network would otherwise be capital- and time-intensive.
- Clinical evidence and case studies: Invest in procedure-specific lifecycle studies (e.g., duodenoscope reprocessing outcomes, instrument turnaround times). Clinical evidence expedites purchasing approvals and reduces resistance during procurement negotiations.
What the PW Consulting report delivers — practical tools for 2026 planning
This report is constructed as a decision support toolkit for executives and program leads. It includes:
- Market sizing and forward-looking revenue models (2020–2032) with scenario and sensitivity analysis calibrated to procurement cycles in hospitals and device manufacturers.
- Demand drivers and dynamics mapped to regulatory milestones (including treatment of ISO 22441:2022 and FDA developments) and practical implications for validation packages.
- Competitive intelligence dossiers on the leading suppliers, with SWOT-style strategic implications and playbooks for partnership, pricing and service strategies.
- Commercial templates: RFP language, total cost of ownership models, service contract structures and procurement negotiation levers that can be used immediately in 2026 bidding rounds.
- M&A screening matrix and financial thresholds that identify accretive acquisition types in a market exhibiting moderate concentration among top vendors.
- Implementation checklists — from clinical validation protocols to sterile processing department (SPD) workflow changes — designed to minimize downtime during equipment rollouts.
How to use these insights in your 2026 planning cycle
- Procurement leaders: Use our validation and TCO templates to accelerate capital approval cycles; anchor bids on documented compatibility with ISO 22441:2022 and recent FDA-cleared cycles.
- Product and R&D executives: Prioritize regulatory-compliant design and secure co-validation partnerships early in the 2026 product calendar to reduce go-to-market lag.
- Investors and corporate development teams: Use our concentration and scenario analysis to identify targets that provide manufacturing scale, regulatory know-how or service infrastructure — each a lever for margin expansion.
- Service providers and distributors: Build playbooks around consumable economics and outcome-based service contracts to capture recurring revenue as the installed base grows.
Final perspective: 2026 is the hinge year
With the market crossing a meaningful threshold in 2026 and regulatory clarity increasing buyer confidence, the next 12–18 months will disproportionately determine market share distribution for the rest of the decade. Firms that synchronize product validation with clinical partnerships, embed compliance into their value proposition, and transition to service-centric commercial models will convert the sector’s predictable growth — a projected CAGR of 6.1% to 2032 — into durable competitive advantage.
PW Consulting’s full Plasma Sterilizers Market report contains the granular models, validated buyer use-cases and vendor scorecards that power tactical 2026 decisions. This introduction highlights the strategic contours; the detailed segmentation, vendor financial estimates and downloadable modeling templates are available in the complete study.
Methodological notes
Base year: 2025. Historical period: 2020–2025. Forecast period: 2026–2032. Revenue figures reported in USD Million. Market concentration metrics and regulatory milestones are synthesized from public filings, FDA databases and vendor disclosures; methodology details and confidence intervals are provided in the full report documentation.
For detailed analysis of this topic, please visit the official page: Plasma Sterilizers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com