

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Biogas Market to Hit USD 90.8B by 2032 at 5.27% CAGR

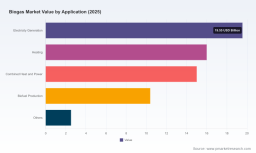
Biogas Market 2026: Strategic Intelligence for Executive Decision-Making
As PW Consulting’s Senior Strategic Advisor and Chief Industry Analyst, I present a distilled yet forward-looking view of the global biogas market to inform executive choices in 2026. Our latest market study — grounded in historical tracking (2020–2025) and a forward forecast to 2032 — shows a market that matured rapidly after 2020, expanding from USD 47.65 Billion in 2020 to USD 63.48 Billion in 2025 (base year). Under the scenarios modeled in this research, the sector is expected to grow at a compound annual growth rate (CAGR) of 5.27% from 2026 through 2032, reaching roughly USD 90.82 Billion by 2032. These headline dynamics are deceptively simple: beneath them lie asymmetric risks and concentrated pockets of opportunity that will determine winners and losers in the coming 18–48 months.
Biogas Market
Why this research matters for 2026 corporate decisions
-
Calibrated investment timing. With a steady mid-single-digit CAGR and near-term volatility in feedstock and policy, project economics are now as much about timing and contract design as they are about technology selection. Our report identifies where capital deployment should be accelerated versus deferred for value preservation.
Biogas Market -
Policy and regulatory navigation. The regulatory landscape has become more fragmented: new methane-detection obligations in some jurisdictions, tightening sustainability limits on energy crops, and evolving tariff frameworks in networked gas systems. Strategic positioning — from compliance programs to advocacy — must be a board-level priority in 2026.
Biogas Market -
Partner and supplier selection. Technology suppliers and operators differ sharply on scalability, integration risk, and O&M profiles. The report synthesizes supplier capabilities and recent project evidence to de‑risk procurement and alliance choices.
-
M&A and portfolio strategy. Market concentration metrics indicate a fragmented supplier base. That opens the door for targeted M&A to consolidate capabilities (e.g., upgrading tech, feedstock logistics, waste-offtake contracts) in high-value corridors.
Market dynamics shaping near-term strategy
The macro trajectory is robust but nuanced. After a pronounced rebound and expansion during 2020–2025, the sector moves into a phase where input cost pressures, policy shifts, and commercialisation of unsubsidised biomethane projects will re-shape returns.
-
Feedstock volatility and operational stress. Feedstock price swings are now a day‑to‑day reality — examples include rising manure-related costs due to fertilizer market volatility and dramatic increases in cow-dung prices in certain markets that have already led to plant shutdowns. Executives must bake feedstock hedging, long-term supply contracts, and co-digestion strategies into project models.
-
Regulatory asymmetries. New methane-detection-and-repair rules in some jurisdictions have raised the compliance bar for emissions management, while equivalent mandatory standards for biogas/biomethane installations remain uneven. Separately, sustainability constraints (notably tightened limits on the use of dedicated energy crops) change feedstock eligibility and revenue modeling. These regulatory nuances affect both capex sizing and permissible revenue streams.
-
Incentive and tariff redesign. Shifts in tariff policies — including proposals to alter distribution tariffs and feed-in economics in networked gas systems — alter the arbitrage between grid injection, direct offtake, and localised utilisation. Our clients tell us these redistributions matter as much as headline subsidy schedules.
-
Commercialisation of unsubsidised projects. The market is transitioning: the first generation of unsubsidised biomethane plants shows procurement and contract structures that can be replicated at scale in certain geographies. These cases create replicable blueprints for companies seeking to exit subsidy-dependence.
Competitive landscape — what leaders and innovators are doing
The industry is characterized by a broad mix of developers, technology vendors, operators, and trade associations. Market concentration indicators show a low-to-moderate level of aggregation — the top three and top five firms account for modest shares, implying significant room for consolidation and entry by specialised players.
-
Technology and equipment providers. Companies supplying upgrading systems and membrane-based separation are central to the margin profile of biomethane projects. Recent field deployments demonstrate how technology choice affects uptime, purity, and downstream value capture.
-
Plant operators and project developers. A number of established operators combine development and long-term offtake expertise, delivering both feedstock management and commercialisation capabilities. These operators are increasingly structuring projects around long-term corporate offtake agreements and industrial partnerships.
-
Industry associations and data bodies. National and regional associations have become primary sources of deployment intelligence; investment flows and project counts reported by these organisations should inform market-entry feasibility studies and policymaker engagement plans.
To ground this at the operational level: recent developments include the commissioning of membrane-based upgraders in emerging markets, high-profile unsubsidised biomethane projects supplying industrial offtake contracts, and significant investment rounds and project pipelines in major markets. These events validate technology pathways and capital appetite but also highlight a widening performance differential between mature project sponsors and smaller operators.
Strategic implications and a 2026 playbook for executives
Based on scenario modelling and field-level diligence, we recommend a pragmatic, stage-gated approach to strategy formulation. Below is a high-level playbook you can adopt for 2026 execution planning.
-
Immediate (0–12 months): tighten project underwriting and procurement
-
Introduce feedstock‑price stress tests and renegotiable supply clauses into new contracts.
-
Prioritise technologies with demonstrated O&M track records in comparable climates; insist on performance guarantees and spare-parts supply clauses for upgraders and membrane systems.
-
Launch methane-detection pilots and integrate repair capability into O&M contracts to proactively address regulatory gaps.
-
-
Near-term (12–24 months): secure commercial optionality
-
Negotiate flexible offtake arrangements (grid injection, direct industrial offtake, RNG for transport) to capture arbitrage as tariff frameworks shift.
-
Form strategic alliances with logistics and waste‑management partners to stabilise feedstock supply and reduce feedstock price risk.
-
Run pilot projects for alternative feedstocks and co‑digestion recipes to diversify input baskets and improve resilience.
-
-
Medium term (24–48 months): scale and consolidate
-
Pursue targeted M&A to acquire upgrading capabilities, gas-grid interconnection expertise, or regional plant portfolios at attractive multiples.
-
Invest in digital twins and predictive maintenance to lower life‑cycle costs and improve plant availability — differentiators when subsidy support is limited.
-
Engage proactively in policy fora and association working groups to shape practical, implementable regulations that preserve project economics while meeting emissions objectives.
-
What our report delivers (practical, actionable content)
This study is intentionally structured to be a practitioner’s toolset for 2026 decision cycles. Highlights include:
-
Top-line market sizing and forecast to 2032 with scenario-adjusted revenue projections and sensitivity analyses tied to feedstock prices, tariff regimes, and technology performance.
-
Risk matrices covering regulatory exposures, feedstock supply chains, and technology integration risks — each mapped to mitigations and contract clauses you can deploy immediately.
-
Vendor and operator scorecards synthesising capability, field-verified performance, and partnership suitability — built from a combination of public disclosures, site-level interviews, and our proprietary diligence.
-
Commercial templates for offtake, feedstock supply, and O&M agreements that reflect 2025–2026 market realities.
-
Execution roadmaps for pilots, scaling, and M&A due diligence — prioritised by risk-adjusted returns and time-to-value.
Note: in keeping with the “trailer” principle, this public summary intentionally highlights insights while withholding detailed segment-level tables and region/application shares. The full report contains the granular split analysis, conservative/base/upside scenario tables, and downloadable contracting templates that are essential for transaction execution.
Concluding perspective
The biogas sector in 2026 sits at an inflection: a solid macro growth path (USD 63.48 Billion in 2025 projecting to USD 90.82 Billion by 2032 at a 5.27% CAGR) coexists with material execution risk from feedstock volatility, regulatory shifts, and tariff redesign. For executives, the answer is neither blind acceleration nor wholesale retreat. Instead, the optimal approach is disciplined, data-driven expansion: lock in feedstock and offtake optionality, select proven upgrading technologies, and use targeted M&A and partnerships to buy capability and scale.
PW Consulting’s full biogas market report equips leaders to operationalise that approach. If your organisation is considering capital allocation, market entry, technology procurement, or M&A in 2026, the detailed datasets, scenario models, and transaction tools in the report will materially shorten your path to investment-grade decisions.
For access to the complete analysis, granular segment tables, and our executable contracting templates, request the full report through the PW Consulting client portal.
For detailed analysis of this topic, please visit the official page: Biogas Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com