

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Offshore ROV Market to Grow at 6.89% CAGR (2026–2032)

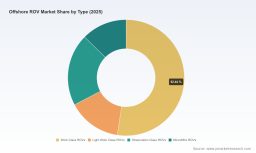
Offshore ROV Market 2026: Strategic Preview for Executive Decision-Making
As offshore energy strategies evolve, remotely operated vehicles (ROVs) are no longer a tactical accessory — they are a strategic asset. PW Consulting’s new Offshore ROV Market study (base year 2025) synthesizes five years of historical dynamics (2020–2025) and the 2026–2032 forecast horizon into a decision-grade intelligence package. This preview outlines the study’s strategic value for corporate leaders planning capital allocation, procurement, and partnerships in 2026 — and explains why the timing for decisive action has arrived.
Offshore ROV Market
Why this report matters for 2026 decisions
2026 will be the year many operators move from experimentation to scaled deployment on two fronts simultaneously: electrified work-class interventions and software-enabled operational models (autonomy, remote piloting, and predictive maintenance). Our market model — built on a base year of 2025 and a 2026–2032 forecast horizon — projects steady expansion at a compound annual growth rate (CAGR) of 6.89%. The market moved from roughly USD 623 million in 2020 to about USD 915 million in 2025 and is forecast to breach the USD 1 billion threshold in 2026, continuing to expand toward the low‑to‑mid billions by 2032. These macro dynamics create three practical imperatives for 2026 decision-makers: (1) lock in supplier and service partnerships before the next procurement cycle tightens capacity; (2) accelerate pilots that materially reduce operating expenditure (OPEX); and (3) embed regulatory and safety readiness in procurement specifications.
Offshore ROV Market
Market trajectory and what the numbers mean
-
Growth profile: A 6.89% CAGR over the forecast period reflects a mix of steady incumbent spending and incremental new demand from renewables and decommissioning work. For CFOs and investment committees, the trajectory implies predictable capital cycles and an expanding aftermarket for spares, training and IRM services.
Offshore ROV Market -
Scale inflection: The market’s transition around 2025–2026 marks an inflection from recovery-driven replacement to technology-driven expansion (electrification, autonomy, sensor fusion). This changes supplier evaluation criteria: performance and integration capability now rank close to price.
-
Market structure: Despite pockets of specialization by leading global suppliers, the competitive landscape remains relatively fragmented. Market concentration metrics indicate that the top-tier incumbents together do not dominate the market, leaving room for specialist OEMs and system integrators to win mandates on differentiated performance, service models or regional presence.
Strategic themes shaping 2026 choices
-
Electrification and lifecycle economics. Conversations that began as proof-of-concept in 2024–25 have shifted to commercial implementation. Electrified ROV platforms and fully electrical launch-and-recovery systems are being positioned as levers to reduce fuel consumption, simplify logistics and lower long-term maintenance costs. Procurement teams must expand evaluation criteria from CAPEX-only comparisons to full life-cycle cost modeling that captures vessel fuel, maintenance, and integration savings.
-
Autonomy and remote operations. Remote piloting, automation of routine inspection tasks, and remote operations centres are maturing. Early adopters report step-changes in crew efficiency and utilisation. The 2026 decision matrix should therefore incorporate software upgrade pathways, cyber-security posture and operator training plans alongside hardware selection.
-
Sector diversification. Demand drivers are increasingly heterogeneous — conventional oil & gas IRM remains a base revenue stream while offshore wind, scientific programmes and decommissioning create adjacent opportunities. Strategic buyers will want suppliers who can demonstrate cross-sector experience and modular tooling sets to avoid lock-in.
-
Regulatory and competency risk. Standards such as NORSOK U-102 and IMO guidance on mixed dive/ROV operations are shaping operator obligations for safety, documented maintenance, and certified operator competencies. In 2026, compliance capability will be a de‑facto procurement criterion in many geographies.
-
Cost to deploy — practical ranges. ROV systems span a wide cost spectrum — from highly affordable inspection-class units to multi‑million dollar work-class systems — while navigation packages (DVL, USBL) represent a non-trivial incremental investment. Buyers must align class selection with mission profiles and TCO scenarios rather than headline price alone.
Competitive landscape — who to watch
The market is populated by a mix of global systems houses, specialized OEMs and regional service providers. PW Consulting’s deep vendor maps focus on strategic capability rather than headline market shares — we examine product architecture, service footprint, electrification roadmaps, aftermarket support and integration ecosystems. Examples of companies covered in our competitive analysis include:
-
Oceaneering International, Inc. (Houston). A dominant provider of work-class ROV systems and integrated services; emphasis on deepwater work-class platforms, advanced tooling and visualization solutions for complex subsea interventions.
-
Soil Machine Dynamics (SMD) (Chester, UK). Specialised in next-generation electric work-class designs tailored to cable and pipeline operations, with a visible focus on subsea power-grid and offshore wind applications.
-
TechnipFMC plc (Houston). Builds on Schilling Robotics heritage with advanced intervention tools and moves to demonstrate ROV electrification and integration proof-points for heavy-duty subsea work.
-
Saab Seaeye , Forum Energy Technologies , IKM Group , Saipem , ECA Group , L3Harris , Deep Ocean Engineering , TMT , and Argus Remote Systems . Each brings differentiated strengths — electric and hybrid platforms, system integration, communications and control systems, or regional deployment scalability. Our profiles assess where each supplier is positioned on electrification, autonomy, and aftermarket delivery.
Recent industry signals that matter in 2026
-
Product innovation. The SPECTRA ROV launch in early 2026 illustrates how specialist OEMs are targeting high-current, high-precision tasks with new mechanical designs and sensor suites — a sign that mission-specific differentiation is accelerating.
-
Electrification narratives gaining traction. Public statements from leading service providers in 2026 confirm electrification is moving from optional to strategic — making supplier roadmaps on electrical architectures and eLARS systems a commercial differentiator.
-
Commercialisation of fully electrical systems. Contract awards for fully electrical launch-and-recovery systems in 2026 validate the commercial feasibility of all‑electric subsea deployment chains and create procurement demand for compatible ROV platforms and vessel retrofits.
What PW Consulting’s full study contains (practical, actionable elements)
We designed this report to be a toolkit for 2026 action — not an academic exercise. Highlights include:
-
Proprietary market model (2020–2032) with scenario runs (base, accelerated electrification, and slowed hydrocarbon spend) and downloadable spreadsheets to test procurement timing and CAPEX/OPEX trade-offs.
-
Supplier scorecards that compare technical readiness, integration risk, aftermarket footprint and commercial pricing frameworks — built to support shortlist workshops and RFP design.
-
Decision frameworks for system selection (inspection vs intervention vs heavy‑duty intervention), TCO calculators, and a build-vs-buy matrix for operators evaluating in-house fleet expansion or outsourced service agreements.
-
A regulatory and competency matrix mapping key standards (e.g., NORSOK U-102, IMO guidance) to procurement clauses and operator training plans so contracts are compliant by design.
-
Case studies and playbooks from recent deployments (electrified eLARS, autonomy pilots, and cross-sector deployments) with lessons learned and procurement templates.
How to use these insights in 2026 — five tactical moves
-
Run a short TCO stress-test on any planned ROV purchase that includes electrification and autonomy upgrade paths — procurement decisions should be defensible on lifecycle cost and operational risk.
-
Prioritise supplier capability proofs: require physical interoperability demonstrations for eLARS and electrical interfaces before long-lead purchases.
-
Lock in training and maintenance windows in contracts: regulatory compliance and certified operator readiness are increasingly non‑negotiable drivers of schedule and cost.
-
Explore modular contracting: separate hardware purchase, software licensing and long‑term service agreements to preserve flexibility as sensor and autonomy stacks evolve.
-
Build a three-year runway for data and cyber readiness: remote operations deliver value only if data flows reliably and securely between vessels, shore operations centres and OEM support.
Limitations of this preview and next steps
This preview surfaces the strategic contours and practical levers that will shape 2026 decisions. To respect the “preview” purpose and to direct operational teams to the full intelligence package, we have intentionally withheld detailed subsegment tables, regional splits and proprietary supplier revenue estimates in this summary. The full Offshore ROV Market report contains all segmentation, supplier benchmarking spreadsheets, downloadable scenario models and procurement templates your teams will need to act immediately.
Concluding recommendation
2026 is a pivotal year to convert technology pilots into durable commercial advantage. The Offshore ROV market’s mid-single-digit CAGR and the projected move beyond USD 1 billion in market size create a predictable environment to capture value — but only for organisations that update procurement criteria, align incentives across CapEx/Opex and secure supplier and compliance capacity now. PW Consulting’s full study provides the data, models and vendor comparators required to make those choices with confidence.
For access to the full dataset, supplier scorecards, and decision tools, consult PW Consulting’s Offshore ROV Market report. Your procurement, asset management and strategy teams will find immediately actionable materials to structure 2026 tenders, capex approvals and partnership roadmaps.
For detailed analysis of this topic, please visit the official page: Offshore ROV Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com