

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Erythritol Market Poised for 6.5% CAGR

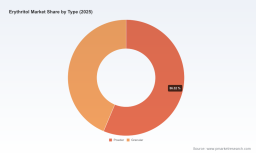
Erythritol Market — Strategic Imperatives for 2026 Decision-Making
As sugar-reduction agendas, clean-label demands, and regulatory turbulence continue to reshape ingredient markets, erythritol stands at a strategic inflection point. PW Consulting’s newest Erythritol Market study (base year 2025) synthesizes market-scale trajectories, supply-chain levers, competitive positioning, and policy shocks into an actionable playbook for commercial, procurement, and M&A leaders preparing decisions in 2026.
Erythritol Market
Market snapshot: scale, trajectory, and concentration
Our top-line model values the global erythritol market at approximately USD 271.5 Million in 2025. Under the study’s central scenario (CAGR 6.5% for the forecast window), the market is projected to exceed USD 297.9 Million in 2026 and to expand toward roughly USD 418.7 Million by 2032. These dynamics reflect a confluence of continued demand for low-calorie bulk sweeteners across beverages, bakery, confectionery and adjacent sectors, tempered by episodic trade and raw-material volatility.
Erythritol Market
Market structure is neither atomized nor tightly monopolistic: the three largest groups capture a meaningful majority, with CR3 at ~56% and CR5 at ~67%. That middle-ground concentration creates persistent pricing and capacity tensions — enough scale for leading producers to influence flows and policy, but sufficient fragmentation for supply disruptions and margin arbitrage to occur.
Erythritol Market
What the report delivers — practical assets for 2026 execution
- Validated market sizing and growth scenarios (2020–2032) calibrated to observed demand and supply events through 2025 and early 2026.
- Forward-looking supply-side mapping: plant-by-plant capacity overlays, fermentation versus crystallization footprints, and export routing considerations.
- Procurement playbook: cost-to-serve models that tie corn-starch feedstock pricing, fermentation yields, and freight regimes to landed cost by buyer archetype.
- Competition compendium: strategic profiles and capability matrices for the leading producers, trading houses, and distributors—assessing technology ownership, non-GMO positioning, and western-hemisphere fermentation capacity.
- Regulatory risk scenarios and customs-duty stress-tests useful for short-term hedging and long-term sourcing reallocation.
- M&A and JV candidacy framework identifying when to (a) partner for offtake and technical know-how, (b) acquire brownfield capacity, or (c) pursue distribution exclusives in priority channels.
Every element is delivered with an emphasis on execution: spreadsheets you can wire into procurement systems, decision matrices for product portfolio trade-offs, and sample term sheets for supplier collaboration. To respect confidentiality imperatives and our "trailer" approach, granular regional and application-level split tables and transaction-level valuations are reserved for the full report and client portal.
Competitive landscape — what matters for 2026 strategies
The competitive field is diverse but patternable. A subset of multinational agribusiness and ingredient specialists control branded, quality-differentiated capacity, while numerous China-based fermentation players supply high-volume, cost-competitive material. Leading traders and distributors knit these supply sources into customer-ready offerings and channel access.
- Cargill and ADM: Represent strategic scale in western fermentation and integrated corn-glucose feedstock chains. Their capacity and distribution reach make them pivotal partners for manufacturers seeking supply security in the Americas and for private-label programs.
- European specialty manufacturers (e.g., Jungbunzlauer and Tate & Lyle): Focus on non-GMO inputs, branded product positioning, and application-specific technical support for food and oral-care formulators.
- Large Chinese fermentation producers: Deliver the market’s marginal tonnage at aggressive unit costs. Their cost position underpins global price competitiveness but also elevates trade friction risk.
- Traders and distributors: Mitsubishi, ProAgro, Buxtrade and others perform the arbitrage and commercial optimization that smooths intermittent supply imbalances for regional buyers.
For buyers, the strategic question in 2026 is not merely "who is cheapest," but “who can guarantee specification, sustainability credentials, and continuity against a backdrop of trade actions and feedstock swings.” Our company profiles score suppliers across these axes so decision-makers can construct tiered sourcing strategies that balance cost and resilience.
Trade measures and regulatory shocks — preparing for policy-driven disruption
Recent policy actions have reshaped how commercial teams should approach contracts and market entry. The European Commission’s definitive anti-dumping duties on imports from China (announced in January 2025 and applied retroactively) and subsequent US preliminary and final measures have created short-term protection for local producers while accelerating de-risking behaviors across buyers and suppliers.
These measures have three practical effects for 2026 strategies:
- Price dispersion widens between protected and unprotected routes — driving some buyers toward higher-cost, regionalized suppliers or toward technological substitution.
- Counterparty risk rises for entities dependent on cross-border arbitrage; buyers must embed customs-duty contingencies in contracts and recalculate landed costs frequently.
- Commercial leverage shifts to manufacturers with local or regional fermentation assets; conversely, high-volume exporters outside the protected markets face pressure to diversify end-markets or climb the value chain with branded formulations.
Our study includes stress-tested scenarios that quantify the P&L impact on buyers and on exporters under varying duty bands and retroactivity assumptions; these tools are particularly valuable when negotiating multi-year offtake or hedging arrangements in 2026.
Raw material and cost-side dynamics — feedstock is the fulcrum
Fermentation economics tie directly to corn-starch and refined glucose pricing. Observed mid-2026 FOB/CIF quotations show material regional dispersion in corn-starch costs. For procurement leaders, small percentage shifts in feedstock translate into meaningful margin swings for commodity-grade erythritol, and comparable movement for contract pricing in private-label engagements.
Practical implications:
- Locking feedstock-linked pricing mechanisms into supplier contracts can transfer cost volatility away from manufacturers; however, these clauses necessitate transparent input pass-through models and audit rights.
- Forward-purchase programs and corridor pricing with logistics partners reduce exposure to freight surges that compound feedstock movements.
- Product innovation (e.g., blends that reduce erythritol loading) can be an effective margin-protection lever but requires upfront application engineering and shelf-life validation.
Actionable strategic options for 2026
We recommend that senior leaders frame 2026 choices around four parallel tracks: protect, optimize, diversify, and capture. Each track contains concrete actions calibrated to company scale and risk appetite.
- Protect — Short-term continuity and compliance:
- Re-run all supplier contracts with duty and retroactivity clauses; negotiate back-to-back indemnities where feasible.
- Prioritize dual-sourcing from geographically differentiated producers and secure minimum-viable inventory corridors for critical SKUs.
- Optimize — Margin and cost engineering:
- Adopt feedstock-linked indexing and pooled freight contracts; implement cost-to-serve analytics at SKU level to identify candidates for price negotiation or delisting.
- Invest in application optimization to reduce erythritol loading or substitute with complementary sweeteners.
- Diversify — Structural resilience:
- Pursue strategic JVs with regional producers to secure contracted capacity and capture margin closer to source.
- Explore tolling or captive fermentation for high-volume portfolios where scale economics justify capital deployment within 18–36 months.
- Capture — Growth and premiumization:
- Develop branded ERY-systems for oral-care, sports nutrition, and adult nutrition where value capture and label claims (non-GMO, natural) command premia.
- Leverage distribution exclusives in underpenetrated markets and bundle erythritol with formulation services to win share from generic suppliers.
Scenario-based decision triggers
Leaders should translate scenarios into binary decision triggers for 2026. Examples we model in the report include:
- If regional duty protection persists beyond 24 months, accelerate brownfield integration or exclusive offtake for tier-1 SKUs.
- If corn-starch CIF prices breach the defined threshold (our model indicates cost pass-through beyond certain levels materially depresses supplier willingness to contract fixed-price deals), shift to indexed pricing and renegotiate margins.
- If CR3 dynamics accelerate due to consolidation, deploy defensive M&A to protect channel share or pursue strategic alliances to maintain competitive parity.
Each trigger is supported by a probabilistic timeline and financial sensitivity analysis in the full report to guide threshold-based commitments versus staged optionality.
Why this research matters for 2026
Decisions made in 2026 will disproportionately determine competitive positioning through 2030. Near-term regulatory outcomes (duties and tariffs) and feedstock price cycles create a corridor of uncertainty where the cost of inaction is high: procurement disruptions, margin erosion, and forgone premiumization opportunities. Our study converts macro signals into executable playbooks: from renegotiating supplier agreements to designing capex tests that preserve optionality while capturing upside as demand grows toward 2032.
We intentionally preserve certain granular regional and application-level splits and detailed supplier capacity schedules for subscribers. That level of disaggregation is essential for transaction diligence, tender strategy, and precise landed-cost calculations — and it is accessible via the full report and interactive dashboards on our platform.
Next steps — how to use the PW Consulting Erythritol study
- Procurement teams: Use the supplied landed-cost templates and duty-stress scenarios to reprice supplier panels and renegotiate terms in Q1–Q2 2026.
- R&D and product teams: Prioritize two pilot programs (one cost-optimization, one premium formulation) to be executed within six months using our application-ready formulation playbooks.
- Corporate development: Request the M&A heat-map and candidate list from our annex to evaluate defensive acquisition or JV options aligned with your risk tolerance.
- Executive leadership: Adopt the report’s trigger framework to convert policy and price movements into disciplined activation thresholds for capital allocation.
For access to the full dataset, regional and application-level breakdowns, supplier capacity maps, and scenario spreadsheets that underpin the analyses summarized here, please visit our report page and download the executive data pack. The proprietary models and contractual templates included are designed to reduce execution latency and give teams an immediate capability uplift for 2026.
Closing note
Erythritol’s trajectory over the next decade will be shaped as much by geopolitics and feedstock economics as by innovation in formulations. Companies that treat 2026 as a year to institutionalize resilience—while selectively capturing premium pathways—will emerge advantaged as the market scales. PW Consulting’s Erythritol Market study provides the analytical scaffolding and the operational tools to act decisively; the full materials unlock the granular inputs you need to make the high-stakes choices ahead.
For detailed analysis of this topic, please visit the official page: Erythritol Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com