

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Cotton Yarn Market to Grow at 3.97% CAGR Through 2032 — PW Consulting

Cotton Yarn Market 2026: Strategic Imperatives for Decision‑Makers
As global supply chains recalibrate and textile value chains re‑price in response to post‑pandemic demand, tariff shifts, and input‑cost volatility, cotton yarn stands at an inflection point. PW Consulting’s latest Cotton Yarn Market study — anchored on a 2025 base year and projecting through 2032 — synthesizes historical performance (2020–2025), near‑term shocks, and structural trends into a concise decisioning framework for 2026 executives. This preview outlines the strategic value of the full report for procurement heads, plant managers, corporate strategists, and investors, while reserving the granular segment tables and regional splits for the full study.
Cotton Yarn Market
Market trajectory at a glance
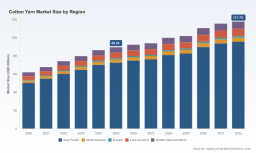
- Recovery and scale: The market has expanded materially from the early‑decade troughs (2020) to a robust 2025 base, reflecting a rebound in consumer apparel and industrial textile demand across major producing hubs.
- Measured growth forward: Under our base forecasting methodology the market is projected to grow through 2032 at a compound annual growth rate (CAGR) of approximately 3.97% for the forecast window, delivering meaningful but not explosive incremental demand that favors disciplined capacity additions and higher‑margin product strategies.
- Size context: The global market exhibits sustained scale and is expected to be materially larger by the terminal year of our forecast; this represents both opportunity for value capture and exposure to cyclical price pressure if capacity additions are mistimed.
Why this study matters for 2026 decisions
- Actionable forecasting: Our scenario‑based projections translate macro drivers into plant‑level demand curves and inventory pressure points for the 2026 planning cycle—crucial for capital expenditure and order book commitments.
- Price and margin sensitivity: With recent movement in producer price indices and commodity feedstocks, the report quantifies pass‑through dynamics and break‑even thresholds for contract renegotiations and hedging.
- Regulatory and tariff playbooks: Rapidly changing trade rules are re‑routing trade flows. The study maps tariff and tax impacts to landed cost across alternative sourcing corridors so procurement teams can quickly reroute and reprice contracts.
- Competitive and M&A intelligence: We benchmark leading producers on capacity posture, product mix, and expansion plans—highlighting acquisition targets and partner profiles optimized for 2026 value creation.
Key macro inputs shaping 2026 strategy
- Cost signals: The raw cotton Producer Price Index (PPI) climbed to 118.299 in April 2026 from 101.319 in December 2025, while the spun cotton yarn PPI moderated to 149.159 (down from 153.620 in January 2026). These indices are embedded in our pricing scenarios and stress tests.
- Domestic price shocks: India’s cotton spot market reached a four‑year high in May 2026, with cotton and yarn price points tightening supply margins; these dynamics are modeled to show knock‑on effects to export competitiveness and stocking decisions.
- Policy and tariffs: New trade measures materially alter cost calculus—examples include the Buying American Act’s per‑pound tariffs on U.S. cotton fiber and manufactured yarn, and localized tariff/VAT regimes in key manufacturing markets. The study provides route‑level landed cost matrices reflecting these measures.
- Export incentive shifts: Changes in export support programs—such as reductions in export incentive rates—are stress‑tested for profit and cash‑flow impact on mid‑sized exporters.
Competition and capacity: What to watch in 2026
The industry structure remains moderately fragmented: our concentration analysis indicates that the top three producers capture roughly one‑third of global market share, and the top five capture just over two‑fifths. That concentration profile informs both consolidation opportunities and the competitive response to capacity moves.
Cotton Yarn Market
- India incumbents and scale plays: Established spinning groups continue to invest selectively in specialty yarns and backward integration. Several large Indian manufacturers have either confirmed expansion plans or reported enhanced export bookings—moves that will strengthen their negotiating position with global apparel houses.
- South and Southeast Asia dynamics: Vietnam and Pakistan producers are increasingly competitive for export‑oriented textiles, helped by modern spindle counts and targeted product mixes aimed at fast‑fashion and home‑textile buyers.
- China’s automation edge: Large, automated spinning complexes in China continue to stabilize volumes and exert pricing discipline on commodity yarn grades, while incremental capacity is directed at higher‑value blends and automated quality control.
- Specialty differentiation: Select producers are capturing premium channels via compact, Siro‑spun, core‑spun and other specialty yarns—segments where margin resilience is greater even in soft demand cycles.
Recent corporate developments reinforce these themes: several firms have announced capacity ramp‑ups with high utilization rates, while others are formalizing product launches in value‑added yarn categories. These are indicative of two parallel strategic responses—scale consolidation for cost leadership, and product premiumization for margin protection.
Cotton Yarn Market
Risk matrix and operational alarms for 2026
- Input volatility: Rising raw cotton PPIs and local price spikes increase feedstock exposure; working capital and inventory strategies must be rebalanced to avoid margin erosion.
- Tariff and policy drift: Per‑unit tariff rules and export incentive cuts can quickly flip sourcing advantages—scenario planning must be embedded into procurement and pricing cycles.
- Overcapacity risk: Synchronized capacity additions in certain hubs risk short‑term price competition; firms without differentiated products or flexible cost structures face the biggest downside.
- Customer concentration: Apparel buyers are consolidating suppliers and emphasizing traceability—suppliers unable to meet compliance or sustainability criteria may be displaced despite competitive pricing.
Practical tools delivered in the full report
PW Consulting’s study is designed for immediate operationalization in 2026 planning cycles. The full report includes:
- Demand and supply dashboards with plant‑level demand curves and utilization scenarios (interactive models provided).
- Price scenario matrices built on observed PPI movements and exchange‑rate sensitivities.
- Tariff and tax impact playbooks for alternative sourcing corridors, including per‑unit landed‑cost comparisons and profitable contract terms.
- Vendor benchmarking and a stepwise M&A playbook that ranks targets by strategic fit, integration complexity and near‑term value capture potential.
- CapEx decision framework tying payback periods to realistic utilization ramps and price realizations.
- A mitigation and transition checklist for procurement, operations, and finance leaders to implement within the next two quarters.
Seven tactical moves for 2026
- Hedge selectively: Use our price‑scenario outputs to size hedges and stagger procurement to mitigate realized PPI spikes.
- Prioritize specialty yarns: Shift a portion of planned capacity additions to higher‑value yarns with defensible technical barriers to entry.
- Trade route optimization: Recalculate FOB and DDP sourcing using the report’s tariff matrices to capture near‑term arbitrage from shifting trade rules.
- Flex capacity: Invest in modular lines and faster changeovers to serve both large apparel contracts and premium small‑lot orders.
- Assess M&A selectively: Target bolt‑ons that add capability (e.g., compact spinning, Siro, core‑spun) rather than just incremental commodity volume.
- Strengthen working capital: Re‑negotiate payment cycles and build supplier financing options tied to PO visibility to reduce cash stress during price swings.
- Embed compliance: Align sourcing and production with major buyers’ traceability and sustainability requests to avoid displacement risk.
Where this preview stops — and why the full report matters
This introduction communicates the strategic contours and operational levers our 2026 clients must consider. To preserve the competitive value of the quantitative segment tables, detailed regional and application splits, and the full vendor benchmarking matrix are intentionally omitted from this summary. Those datasets — including route‑level landed costs, plant‑specific utilization scenarios, and the full sensitivity outputs — are available in the complete Cotton Yarn Market report and interactive model package.
For procurement directors, CFOs, and corporate strategists preparing capital and sourcing decisions for 2026, the full study supplies the granular inputs and playbooks required to move from insight to execution. PW Consulting’s advisory team is available to walk through tailored scenarios, run bespoke sensitivity analyses, and support rapid implementation over the next quarter.
Next steps
- Request the full report and interactive model to access the detailed segment tables, regional splits, and the vendor benchmark matrix.
- Schedule a bespoke briefing with our industry leads to translate findings into a 90‑day action plan aligned to your operating model.
In a market where modest aggregate growth masks significant redistributions of value across geographies, product types, and buyer segments, disciplined scenario planning and tactical flexibility will determine winners. The full PW Consulting Cotton Yarn Market study provides the empirical foundations and pragmatic playbooks to make those decisions with confidence in 2026.
For detailed analysis of this topic, please visit the official page: Cotton Yarn Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com