

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Pelvic Organ Prolapse Repair Market to Reach USD 1.57B by 2032 (8.32% CAGR)

Pelvic Organ Prolapse Repair Device Market: Strategic Imperatives for 2026
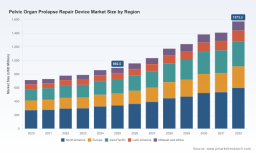
PW Consulting’s Pelvic Organ Prolapse (POP) Repair Device Market study (base year 2025; historical 2020–2025; forecast 2026–2032) is designed as a decision-grade resource for executives planning investment, portfolio, and go-to-market moves in 2026. The market has shown steady expansion — rising from approximately USD 712.5 Million in 2020 to USD 892.5 Million in 2025 — and our forecast models project continued acceleration under an 8.32% CAGR through the 2026–2032 horizon, with the market exceeding USD 1.57 Billion by 2032. This trajectory frames a window of strategic opportunity driven by regulatory, clinical, and commercial shifts that leaders must navigate deliberately.
Pelvic Organ Prolapse Repair Device Market
Why this study matters for 2026 decisions
-
Timing: 2026 represents an inflection point. The interplay of regulatory guidance, reimbursement stability for key procedural codes, and new product classes (notably bioresorbables and biologic grafts) creates discrete windows for market entry, line extensions, and consolidation plays. Our report converts macro momentum into prioritized actions calibrated to the 2026 operating year.
Pelvic Organ Prolapse Repair Device Market -
Risk-reward clarity: With market concentration at meaningful levels (CR3 ≈ 58%, CR5 ≈ 62%), incumbents retain leverage but face pressure from nimble innovators. The analysis in this study quantifies where incumbents can defend margin pools and where challengers can capture disproportionate share through differentiated clinical value, lower total cost-of-care, or ambulatory-enabled distribution models.
Pelvic Organ Prolapse Repair Device Market -
Decision frameworks not just data: The study translates growth projections into investment thresholds, go/no-go trigger points for product development, and M&A screening criteria — so that teams can move from “what if” to “what next” in 2026.
Market trajectory and structural drivers
The historical growth documented through 2025 reflects a combination of demographic demand, heightened clinical awareness, and evolving procedural pathways. Forecasting through 2032, the model incorporates an 8.32% CAGR that captures three structural dynamics: (1) a shift away from legacy synthetic transvaginal mesh modalities toward biologics and bioresorbable platforms, (2) the migration of eligible cases into lower-acuity ambulatory settings supported by single-use procedural kits and simplified instrumentation, and (3) incremental reimbursement clarity for established procedural codes that stabilizes the commercial environment for device sponsors.
These drivers are uneven across product archetypes and channels — a fact that underpins our recommendation that companies adopt a portfolio view that blends near-term cash-generating offerings with medium-term innovation bets. The summary growth figures (2020–2025 historical and 2026–2032 forecast) should be used as a directional compass; our full report provides the underlying sensitivity matrices and scenario outputs that convert that compass into tactical plans.
Regulatory and clinical context — what keeps payors and procurement teams awake
-
Regulatory posture: Recent regulatory statements have reinforced scrutiny of transvaginal surgical mesh devices for POP, emphasizing unfavorable benefit-risk assessments relative to native tissue repair in certain use cases. For 2026 planning, this means regulatory strategy must be proactive: robust post-market surveillance, clear articulation of patient selection criteria, and clinical pathways demonstrating comparative outcomes will be table stakes for broader adoption.
-
Material innovation as a response: Major manufacturers are prioritizing bioresorbable materials and biologic grafts that promote faster tissue integration and aim to reduce long-term device-related complications. Investment decisions in 2026 should weigh the clinical differentiation and reimbursement trajectory of these materials against development timelines and regulatory pathways.
-
Reimbursement stability: Established billing pathways — including codes commonly used for reconstructive procedures — create a baseline for economic modeling. However, as case mix shifts to outpatient and ambulatory surgical centers, device economics will increasingly be judged on total cost-of-care and ease-of-use rather than device price alone.
-
Operational implications: Single-use procedural instrument configurations diminish institutional costs related to sterilization and cross-contamination risk, supporting adoption in ambulatory settings and enabling new direct-to-clinic commercial approaches.
Competitive landscape — positioning for 2026
The competitive field combines global medtech incumbents, specialized device innovators, and a small but active group of early-stage challengers. Below are high-level strategic positions of principal players, framed to help executives assess competitive response options.
-
Escala Medical (Israel) — Escala is a niche innovator with a minimally invasive Mendit anchor system that addresses surgical access and anchoring without large incisions. Their successful funding round in June 2025 to accelerate commercialization highlights investor conviction in targeted, less-invasive approaches. For partners or acquirers, Escala represents an asset to scale in markets seeking incision-free alternatives.
-
Boston Scientific Corporation (US) — Offers procedural devices and mesh solutions oriented toward pelvic floor reconstruction. Their product breadth and channel scale mean they can execute bundled clinical evidence-generation and broad distribution — a structural advantage in defending share where scale and integrated solutions matter.
-
Coloplast Group (Denmark) — Established in biologic mesh and procedural kits, Coloplast’s clinical relationships and portfolio depth position it well in centers that favor biologics over synthetic options. Their playbook focuses on clinician training and consumables-based revenue streams.
-
Johnson & Johnson MedTech (Ethicon, US) — With investments in bioresorbable materials and minimally invasive kits, Ethicon’s capabilities in materials science and global regulatory experience make it a logical leader in bringing next-generation platforms to scale, particularly where clinical evidence and surgeon preference drive adoption.
-
Cook Medical, Integra LifeSciences, CooperSurgical, Utah Medical Products — These vendors operate across instrument, graft, and customized-solution segments. Their strategies vary from niche product excellence to broad surgical supply relationships, and they are attractive partners for distribution scale or complementary technology acquisitions.
-
Notable regulatory and market moves : Outside the headline players, regulatory clearances such as a 510(k) for a collapsible pessary device (approved in 2024) demonstrate ongoing innovation in non-surgical management options. These developments matter strategically because they expand conservative management pathways and can affect surgical case volumes over time.
What the report contains — practical, actionable modules
PW Consulting’s study is intentionally operational. It includes:
-
Market sizing and high-resolution forecasting (historical 2020–2025 and forecast 2026–2032) with built-in sensitivity tests and scenario outputs for conservative, base, and aggressive uptake paths.
-
Competitive benchmarking that maps product portfolios, clinical evidence levels, regulatory positions, manufacturing scale, and channel strength across leading players, plus a playbook for defensive and offensive moves tailored to 2026 windows.
-
Regulatory and reimbursement playbooks — including procedural coding implications and payer negotiation approaches — built to de-risk launch sequencing and pricing decisions.
-
Commercial models and go-to-market templates for different channel strategies (hospital OEM partnerships, ambulatory surgical center direct models, and physician office-based disposables), including margin waterfalls and break-even timelines.
-
M&A and partnership screening matrices that translate clinical, regulatory, and commercial criteria into defensible acquisition targets and joint-venture constructs for 2026.
How to use this intelligence in 2026 — prioritized next steps
-
For R&D leaders: Prioritize investments in bioresorbable and biologic graft platforms with clear clinical end-points and reduced complication profiles. Use scenario outputs to size R&D spend and time-to-value under different regulatory routes.
-
For commercial leaders: Calibrate channel mix to capture ambulatory migration — deploy single-use kits and targeted training programs to reduce barriers to adoption and shorten the sales cycle.
-
For corporate development: Use the report’s M&A screening to identify tuck-in targets that fill material or instrumentation gaps — and to size deals against projected share gains and margin accretion under conservative uptake scenarios.
-
For clinical affairs: Build post-market evidence plans and registries that directly address regulatory concerns about long-term device outcomes; early investment here materially affects labeling, clinician confidence, and payer coverage decisions.
Concluding strategic perspective
The POP repair device market is at once mature in core demand drivers and nascent in material and delivery innovation. With a projected 8.32% CAGR in the 2026–2032 forecast window and market size growth that doubles the strategic canvas for many players, the next 18–24 months will determine who shapes the clinical standard-of-care. Success in 2026 will come to those who combine disciplined capital allocation, surgical and material innovation, and a regulatory-first evidence strategy — all supported by pragmatic commercial models that reflect the ambulatory migration of care.
PW Consulting’s full study converts these strategic imperatives into executable plans, granular models, and transaction-ready analyses. To obtain the detailed subsegment breakouts, product-level forecasts, and competitor scorecards that we intentionally reserve for the full publication, please visit our report landing page.
For detailed analysis of this topic, please visit the official page: Pelvic Organ Prolapse Repair Device Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com