

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Bio-Pharma Buffer Market Set for 7.85% CAGR Through 2032

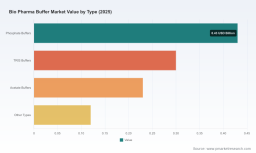
Bio Pharma Buffer Market — 2026 Strategic Preview
As biopharmaceutical pipelines continue to mature and manufacturing footprints expand, buffers have quietly become a strategic raw material rather than a commoditized consumable. PW Consulting’s upcoming Bio Pharma Buffer Market study (base year 2025) synthesizes seven years of historical trends (2020–2025) and delivers a seven‑year forecast (2026–2032) to equip commercial, supply‑chain and R&D leaders with the intelligence they need to make defensible 2026 decisions. At an aggregate level the market has grown from roughly USD 0.68 Billion in 2020 to about USD 1.08 Billion in 2025, and is projected to reach approximately USD 1.86 Billion by 2032 at a compound annual growth rate (CAGR) of 7.85%. This preview outlines why that trajectory matters — and what to focus on when you read the full report.
Bio Pharma Buffer Market
Why buffers now matter strategically (and what 2026 decision‑makers risk if they ignore them)
-
Buffers are a gating item across the biologics value chain. From cell culture media conditioning and upstream process stability to robust downstream purification and diagnostic reagent consistency, buffer systems impact yield, product quality attributes and regulatory compliance. Small shifts in buffer quality or availability ripple into batch success rates and cost of goods sold (COGS).
Bio Pharma Buffer Market -
Market growth is being driven by an expanding biologics pipeline (biologics, cell and gene therapies, and advanced therapeutics), increased downstream processing complexity, and the rising emphasis on reproducibility in diagnostics and molecular biology workflows. These structural drivers are embedded in the 7.85% CAGR we model through 2032.
Bio Pharma Buffer Market -
Operational and supply risks are real. Our analysis documents instances of raw‑material price volatility and supply shocks that have propagated to buffer costs and lead times; regulatory expectations around buffer quality have also intensified. Procurement approaches that worked in a cheaper, lower‑complexity era—single‑source purchasing, minimal spec governance—now create outsized risk.
What this PW Consulting report delivers — practical, decision‑grade assets
This study was designed to be executable by commercial teams, procurement organizations, and corporate strategy functions. Key deliverables in the full report include:
-
Validated market sizing and topline forecast (2020–2032) with scenario modelling to stress‑test assumptions around demand shock, raw‑material price spikes, and accelerated biologics adoption.
-
A supply‑chain heat map that traces sources of raw materials, critical intermediates, and the concentration of manufacturing capacity — with a focus on points of failure and mitigation options.
-
Regulatory and quality matrix outlining how major regulators view buffer control strategies, risk controls that matter to auditors, and practical quality thresholds for cGMP use.
-
Actionable procurement playbooks: sourcing strategies (including dual‑sourcing and contractual levers), unit‑cost models, and hedging templates for volatile raw inputs.
-
A vendor‑level competitive landscape with strategic profiles, capability assessments, and a short list of target partners for outsourcing, co‑development, or acquisition.
-
Implementation toolkits — from buffer‑preparation automation ROI calculators to standard operating procedure (SOP) blueprints for switching between pre‑formulated solutions, dry powders and in‑house preparations.
To preserve the strategic value of the report and to drive direct engagement, this preview intentionally refrains from publishing the full segment‑level splits and granular regional allocations — those are available in the full report.
Market dynamics: supply shocks, regulatory pressure and labor intensity
-
Raw‑material volatility: The market has experienced material price spikes tied to key intermediates in 2024 and 2025. These events increased buffer input costs and forced buyers to reassess inventory policies and supplier exposure. The full study models the sensitivity of buffer pricing to these upstream disruptions and proposes practical hedging strategies.
-
Regulatory tightening: Regulatory authorities are increasingly explicit about the role of buffer quality in product safety and effectiveness. In practice this means higher documentation, more rigorous supplier qualification and, for many manufacturers, a shift toward cGMP‑grade buffer solutions. The report decodes recent guidance and translates it into procurement and compliance checklists.
-
Labor and operational cost drivers: Buffer preparation at scale remains labor‑intensive. Holding tanks, manual preparation steps and complex quality release workflows create cost and risk. Automation and pre‑formulated product formats are therefore not just efficiency plays — they are risk reduction strategies.
Competitive landscape — positioning the major players
The market exhibits a mixed structure of global diversified suppliers, specialized life‑science players, automation vendors and regional low‑cost producers. Top‑of‑market concentration is moderate: the three largest firms account for roughly one‑third of the market while the five largest approach just under half. That competitive geometry creates opportunities for specialization, partnership and consolidation.
-
Thermo Fisher Scientific (Waltham, MA) — large platform advantage in cGMP buffer supply and process liquid preparation services. Their scale and integrated services make them a natural partner for large‑scale biologics manufacturers seeking turnkey buffer supply and validation support.
-
Avantor (Center Valley, PA) — known for J.T.Baker® and dry powder buffer lines focused on reproducibility and shelf stability. Their portfolio suits customers seeking lower logistic overhead and predictable on‑demand reconstitution.
-
Merck KGaA (Darmstadt, Germany) — strong life‑science solutions offering high‑purity buffer systems tailored to regulated production processes; attractive for organizations that prioritize regulatory alignment and global supply continuity.
-
Sartorius AG (Göttingen, Germany) — productized solutions (e.g., pre‑formulated systems) designed to integrate with process monitoring and control workflows; their emphasis on optimization resonates with customers pursuing process intensification.
-
Lonza (Basel, Switzerland) — CDMO and contract‑manufacturing capabilities position Lonza to offer custom buffer supply and co‑manufacturing options, valuable for companies outsourcing drug substance production.
-
Cytiva (GE Healthcare) (Chicago, IL) — strong downstream positioning, supplying buffer components and systems commonly embedded in purification train strategies.
-
Bio‑Rad, BD, Promega — these firms serve research and early‑stage production customers with pre‑formulated solutions and reagents critical to assay and small‑batch workflows.
-
Hamilton Company — drives automation in buffer preparation, enabling leaner operations and reduced human error at commercial scale.
-
Regional producers (e.g., Shandong Xingzhilian, SRL) — competitive on cost and increasingly present in global supply chains; they introduce arbitrage opportunities but also require robust qualification and risk management.
Strategic moves to prioritize in 2026
Our modelling and client work suggest a set of high‑impact actions for different stakeholders heading into 2026. These are practical and immediately implementable:
-
For biopharma manufacturers: move from ad‑hoc buffer procurement to a portfolio approach: define criticality matrices, segregate buffers into strategic vs tactical categories, and adopt multi‑tier sourcing strategies that pair global strategic suppliers with qualified regional producers.
-
For buffer suppliers and CDMOs: invest in productization — pre‑formulated and dry‑powder formats reduce on‑site complexity for customers and create stickiness. Combine that with services (validation support, on‑site buffer preparation, automation) to defend margins.
-
For procurement leaders: implement unit‑cost modelling and dynamic inventory policies informed by the scenarios in our report; incorporate raw‑material exposure clauses and periodic requalification paths into long‑term contracts.
-
For investors and M&A teams: look for targets that provide differentiated service layers (automation, cGMP‑scale custom preparation, niche high‑purity chemistries) rather than pure commodity chemistry plays.
Why PW Consulting’s study should be in your 2026 toolkit
Beyond headline growth and directional forecasts, this study provides the kind of operational granularity that converts strategy into execution. We combined market‑level forecasting with supplier diligence, primary interviews with procurement and process experts, and build‑out of practical tools (ROI calculators, SOP templates and supplier‑qualification checklists) so that your teams can move from insights to implementation within weeks.
Note: this preview purposefully omits detailed region and application splits and other proprietary micro‑segmentation to preserve the commercial value of the full dataset. If you are aligning sourcing strategies, planning capacity investments, or evaluating partnership or acquisition targets in 2026, the complete report contains the segment‑level forecasts, supplier scoring models and scenario outputs you will need to execute.
Next steps
-
Download the full report to access the segment level forecasts, supplier scorecards and executable playbooks.
-
Schedule a workshop with PW Consulting to translate the report’s scenarios into your 2026 sourcing and capital plans — our clients typically prioritize a two‑day rapid‑design session that yields an implementable 90‑day plan.
-
Contact our advisory team for bespoke diligence (supplier audits, M&A screening, regulatory preparedness) informed by the dataset and models underpinning this study.
Buffers are no longer a back‑office line item: they sit at the intersection of quality, cost and operational resilience. The market is sizable, growing at a mid‑single‑digit to high‑single‑digit CAGR through 2032, and evolving in ways that reward foresight. PW Consulting’s full Bio Pharma Buffer Market report provides the empirical foundation and operational playbooks needed to convert that foresight into advantage in 2026.
For detailed analysis of this topic, please visit the official page: Bio Pharma Buffer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com