

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Gas Compressors Market to hit USD 8.23 Billion by 2032 at 4.4% CAGR

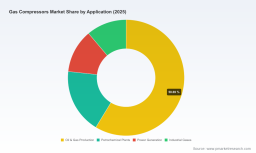
Gas Compressors Market 2026 — Strategic Preview for Decision Makers
As companies plan capital allocation and operational priorities for 2026, the gas compressors market presents a mix of steady expansion, regulatory-driven re‑engineering, and supplier consolidation that demands a calibrated strategic response. PW Consulting’s new industry study distills market intelligence across the full value chain — from OEM technology choice to aftermarket service models — and equips executives with pragmatic frameworks to act with confidence. This preview highlights the report’s strategic value, key macro metrics, competitive dynamics, and the practical tools executives will need to navigate 2026 with reduced execution risk.
Gas Compressors Market
Why this study matters in 2026
-
Market momentum: The market has demonstrated resilient growth over the first half of the decade, expanding from approximately USD 4.6 Billion in 2020 to USD 6.1 Billion in 2025. Our base‑case projection anticipates continued expansion to roughly USD 8.2 Billion by 2032 at a compound annual growth rate (CAGR) of about 4.4%. These aggregate trajectories enable CFOs and strategy teams to align multi‑year capex plans with realistic revenue pools and service demand.
Gas Compressors Market -
Near‑term variability: The roadmap between 2026 and 2032 is not uniformly linear — our scenario suite identifies episodic softening and rebound patterns that affect timing of orders, spares stocking, and overhaul cycles. Firms that integrate timing risk into procurement and inventory strategies will preserve margin and uptime.
Gas Compressors Market -
Regulatory inflection: From emission limit updates to new per‑ton methane charges, regulation is shifting cost and technology choices. The study translates evolving policy levers into quantifiable cost exposures and compliance pathways for operators and OEMs alike.
What decision‑makers get from the full report
-
Actionable financial models — deployable templates for CAPEX planning, total cost of ownership (TCO) comparison across compressor technologies, and scenario sensitivity to fuel prices, carbon/methane levies, and maintenance frequency.
-
Risk heatmaps — supplier concentration, component lead‑time exposures, and labor intensity overlays that reveal where redundancy, localization, or strategic partnerships are warranted.
-
Regulatory playbooks — step‑by‑step compliance strategies for the new wave of methane and volatile emissions rules, translated into equipment retrofits, seal choices, and monitoring investments.
-
Service and aftermarket strategies — profit pools mapped to performance‑based service contracts, digital monitoring monetization, and parts lifecycle management that protect margins as equipment lifecycles lengthen.
-
M&A and alliance intelligence — valuation heuristics and acquisition target archetypes for companies looking to consolidate capabilities, secure technology gaps, or expand service footprints.
-
Procurement playbook — timing guidance for orders, negotiation levers tied to projected demand cycles, and procurement clauses to mitigate raw material and labor cost inflation.
Macro dynamics shaping 2026 choices
-
Policy and compliance cost shocks: Two regulatory developments stand out as immediate decision triggers. First, an effective methane waste emissions charge introduced in 2026 materially raises the operating cost of non‑compliant compressor installations; our scenarios show that economic breakeven for retrofit investments can move from long‑tail to near‑term for many operators. Second, state‑level emission standard updates — exemplified by recent rule changes in Colorado that extend volumetric limits to multiple compressor sealing types — create clear deadlines for retrofit or replacement programs. Executives must bake these timelines into next fiscal year CAPEX cycles.
-
Input cost pressure: Manufacturing cost indices for compressors have reached elevated levels, reflecting upstream material and component inflation. At the same time, large reciprocating units require specialized installation and overhaul labor, which contributes meaningfully to the lifecycle cost base. These twin pressures push organizations to revisit total cost, not just purchase price, when selecting equipment.
-
Technology and service convergence: Customers are increasingly valuing integrated offers — equipment that pairs efficient mechanical design with digital condition monitoring and outcome‑based service guarantees. Winners will be those who reconfigure commercial models to capture aftermarket annuity revenue while de‑risking uptime for end users.
Competitive landscape — positioning and strategic implications
The market exhibits a moderate degree of concentration: the top three suppliers capture roughly half the market, and the top five command a clear majority. This structure creates both defensive and offensive strategic paths for suppliers and buyers.
-
Ariel Corporation — Famous for high‑speed reciprocating designs, Ariel remains the go‑to for pipeline and gas transmission players where familiarity and proven reliability matter. For buyers, Ariel’s strength implies reliable aftermarket availability but also a potential premium in negotiated pricing for specialized configurations.
-
Burckhardt Compression — With a portfolio spanning centrifugal and reciprocating platforms and increasing focus on hydrogen mobility and LNG, Burckhardt is positioning for energy transition demand. Partnerships or licensing deals with technology frontrunners will be an important defensive move for competitors.
-
Siemens Energy and GE / Baker Hughes Energy Innovations — These global scale players dominate large‑frame centrifugal segments, especially where systems integration into gas processing and LNG trains is required. Their capability to bundle compressors with drivers and plant control systems raises the bar for independent OEMs that must either specialize or collaborate.
-
Atlas Copco and Ingersoll Rand — Focused on energy efficiency and industrial process applications, these vendors compete on lifecycle cost and energy performance, which becomes a decisive factor under rising emissions costs and stricter operational limits.
-
Everllence and other niche innovators — Newer entrants and specialized European OEMs are winning orders tied to carbon capture projects and LNG floating solutions. Recent contract awards in 2026 for CCS projects indicate how quickly niche competencies can translate into strategic account wins.
-
Service and rental specialists (e.g., Archrock and others) — Service models that combine equipment rental with performance guarantees are attractive to operators looking to defer CAPEX while meeting regulatory deadlines. Expect growth in hybrid ownership models.
Recent market signals to act on now
-
Large CCS orders and LNG project awards are validating demand for radial and axial solutions in specialized applications — suppliers investing in these capabilities should accelerate commercialization plans.
-
State rule updates that take effect in the near term fundamentally alter retrofit economics. Operators with significant fleet exposure should prioritize emissions audits and phased retrofit roadmaps during 2026 budget cycles.
-
Emergent per‑ton methane charges create direct unit economics for emissions reduction. Early adopters of low‑leakage seals and continuous monitoring will capture differential margin and avoid escalating operating fees.
Practical recommendations for 2026 planning
-
Integrate regulatory cost curves into capex decision trees. Treat emissions charges as recurring operating line items when evaluating new builds versus retrofits; for many configurations the payback period compresses materially under current rules.
-
Move from component procurement toward system procurement where appropriate. Total lifecycle cost advantages from energy‑efficient machines and digital monitoring often outweigh marginal savings from lowest‑price component buys.
-
Design a two‑track supplier strategy: secure long‑lead, high‑criticality components with established majors while nurturing relationships with niche specialists for emerging applications (e.g., CCS, hydrogen). This reduces supply risk without sacrificing innovation access.
-
Operationalize service‑centric business models. For OEMs and service providers, build modular, subscription‑friendly offerings that monetize condition monitoring and predictive maintenance; for operators, seek outcome‑based contracts that transfer performance risk.
-
Stress‑test scenarios against input cost volatility. Given elevated manufacturing cost indices and labor intensity for major overhauls, incorporate material price and skilled labor sensitivity into procurement contracts and contingency planning.
What the full PW Consulting report contains (practical chapter map)
-
Executive summary and five year strategic imperatives
-
Market sizing and forecast models (2020–2032) with downloadable time‑series data and scenario toggles
-
Technology deep dives and TCO calculators for centrifugal, reciprocating, screw, and axial technologies
-
Regulation impact assessment and compliance playbooks tailored to regional enforcement timelines
-
Supplier profiles, capability matrices, and competitive positioning with acquisition and partnership opportunities
-
Supply chain and procurement risk assessment, including lead‑time and cost‑inflation modeling
-
Aftermarket and service monetization playbooks with contract templates and margin models
-
Implementation checklists, board‑level talking points, and a 12‑month action plan for executives
Final note — a strategic invitation
PW Consulting’s full market study delivers the granular datasets, supplier scorecards, and scenario models that strategic and operational leaders need to move from insight to execution in 2026. This preview outlines the macro trajectories and decision levers; the complete report contains the detailed segmentation, regional demand matrices, and downloadable financial models that enable precise procurement, retrofit, and M&A decisions. Reach out to access the full analysis and customized briefings tailored to your asset base and strategic horizon.
For detailed analysis of this topic, please visit the official page: Gas Compressors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com