

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Acrylic Fibers to Hit USD 6,500M by 2032 at 3.46% CAGR

Acrylic Fibers Market 2026: Strategic Preview for Decision-Makers
Executive snapshot
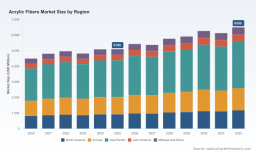
The acrylic fibers market is navigating a period of measured growth, material volatility, and intensifying regulatory scrutiny. Our new PW Consulting study — with base year 2025, a detailed historical window (2020–2025) and a forecast horizon through 2032 — finds the market growing at a compound annual rate consistent with steady, single-digit expansion (CAGR 3.46% for the forecast period). From roughly USD 4.5 billion in 2020 the industry expanded to just over USD 5.1 billion by 2025 and, under our central forecast, is on a trajectory to exceed USD 6.5 billion by 2032. These macro trends create both tactical pressures and strategic opportunities for manufacturers, downstream brands, investors and policy-makers heading into 2026.
Acrylic Fibers Market
Why this research matters for 2026 decisions
-
Timing capital allocation: With upstream feedstock volatility (notably propylene and acrylonitrile) and tighter environmental constraints, capex that is deferred or misallocated in 2026 risks higher operating costs and regulatory friction in the immediate term. Our report translates market momentum and cost trajectories into investment-ready scenarios that optimize timing and scale of capacity initiatives.
Acrylic Fibers Market -
Supply-chain resilience and sourcing strategy: Manufacturers that re-evaluate feedstock sourcing, contract structures, and inventory policies in 2026 will be better positioned to mitigate price shocks and margin compression identified in our scenarios.
Acrylic Fibers Market -
Product and sustainability positioning: As product certification and recycled-content requirements become binding in multiple jurisdictions, 2026 is the pivot year for aligning product portfolios with traceability, recycled content, and lifecycle claims. Our study prescribes prioritized product pathways to capture premium positioning without eroding core industrial volume.
-
M&A and partnership targets: Market concentration metrics reveal room for consolidation and strategic partnerships. The report highlights attractive capability gaps and regional plays that can be converted into value-creating deals or capacity partnerships in 2026.
Market dynamics — what is driving change in 2026?
-
Raw material volatility: Early-2026 movements in propylene contributed to downstream pressure on acrylonitrile costs, with acute price spikes observed in specific markets during the first half of the year. These swings feed directly into margin sensitivity for acrylic fiber producers and underscore the need for active hedging and alternative feedstock strategies.
-
Regulatory tightening and compliance costs: Multiple jurisdictions in North America, Europe and East Asia intensified product certification, safety standards and emissions controls in 2025–2026. Our analysis shows a material portion of producers confronting additional compliance burdens and, in many cases, operational constraints on expansion — a structural headwind that favors companies with established environmental management and certification capabilities.
-
Sustainability and circularity: Recycled-acrylic products and traceability solutions moved from niche to mainstream during 2024–2025. Traceability partnerships and certification schemes are now a table-stakes requirement for many apparel and home-furnishing buyers. Companies that integrated recyclate and verifiable supply‑chain credentials early captured preferential offtake and pricing premiums.
-
Demand composition and end-market shifts: Consumer-facing segments continue to demand performance, comfort and sustainability attributes while some industrial applications prioritize cost and durability. Navigating these sometimes-contradictory demands requires segmentation strategies that go beyond commodity competition.
Competitive landscape — what the leading players are doing
The acrylic fibers industry exhibits moderate concentration (CR3 ~35%; CR5 ~48.8%). This structure produces room for both scale-driven incumbents and agile, differentiation‑oriented challengers. Below we summarize the strategic postures of the core companies profiled in our report:
-
Aksa Akrilik Kimya Sanayii A.Ş. (Yalova, Turkey) — Expanding product breadth to capture both apparel and technical textile segments. Their moves emphasize portfolio extension and customer intimacy in key textile clusters.
-
Dralon GmbH (Dormagen, Germany) — Ongoing operational investments and production optimization indicate a play for margin resilience and flexible product conversion capabilities for European buyers facing stricter compliance regimes.
-
Exlan Japan Co., Ltd. (Osaka, Japan) — Focused on differentiated filament and specialty fiber offerings aimed at performance and value-added textile applications.
-
Kaneka Corporation (Osaka, Japan) — Leveraging chemical and materials competencies to deliver specialty acrylic solutions that meet advanced performance and regulatory requirements.
-
Toray Industries, Inc. (Tokyo, Japan) — Recent adoption of mass balance methodology in staple fiber production signals a strategic commitment to traceable sustainability claims and lifecycle accounting — an important differentiator for brand customers seeking credible environmental credentials.
-
Thai Acrylic Fibre Co. Ltd. (Bangkok, Thailand) — The launch of recycled acrylic products and a traceability partnership positions them as a leader in circular product offerings for apparel and home textiles.
-
Vardhman Acrylics Ltd. (Ludhiana, India) — Emphasizing scale and integration to serve regional textile clusters while pursuing quality and compliance upgrades to meet export market thresholds.
-
Indian Acrylics Limited (Sangrur, India) — Concentrating on cost‑competitive production with incremental moves into value-add segments supported by quality improvements.
-
Jilin Chemical Fiber Group Co., Ltd. (Jilin, China) — A regional heavyweight with capability to serve large domestic demand pools and export channels; strategic emphasis on capacity and operational efficiency.
-
Pasupati Acrylon Ltd. (India) — Focused on regional supply and integration with downstream textile value chains.
Notable recent developments investors and strategists should watch
-
Toray’s roll-out of mass balance approaches in staple fiber production (March 2025) — a signal that lifecycle accounting and credible sustainability claims will be increasingly embedded in supply agreements.
-
Aksa’s mid‑2025 product-range expansion for apparel and technical textiles — reflecting a dual strategy to protect commodity margins while pursuing higher-value applications.
-
Dralon’s sustained operational investments — indicative of a defensive posture to maintain competitiveness under tighter European regulation.
-
Thai Acrylic Fibre’s introduction of a GRS‑certified recycled acrylic and partnership with a traceability provider (2024) — a practical example of how traceability and recycled content can be commercialized.
Report contents — practical, decision-ready deliverables
Our full PW Consulting industry study blends strategic narrative with executable frameworks. Highlights include:
-
Macroeconomic and feedstock scenario modelling that ties propylene and acrylonitrile trajectories to cost of goods sold (COGS) and margin sensitivity under multiple price regimes.
-
Regulatory impact matrices mapping jurisdictional requirements to compliance options, capex implications and time‑to‑market scenarios for certified/recycled products.
-
Commercial playbooks for four strategic archetypes — scale integrators, premium differentiators, circularity specialists, and regional consolidators — each with prioritized initiatives, KPI templates, and a 90‑180‑360 day action plan.
-
Supply‑chain risk heatmaps and supplier optimization guides, including contracting levers and inventory strategies to mitigate price and availability shocks.
-
Investment case frameworks for greenfield, brownfield and bolt-on M&A opportunities, with valuation sensitivity to feedstock and regulatory scenarios.
How to use this analysis in 2026 — practical recommendations
-
Revisit feedstock strategy now: Use the report’s scenario outputs to stress-test supplier contracts and identify feasible alternatives or hedges before midsummer 2026 price cycles close.
-
Prioritize compliance-enabled products: Fast-follow or lead on certification and traceability upgrades for goods sold into regulated markets to avoid commercial exclusion or surcharges.
-
Segment product investments by value capture: Allocate R&D and capex to product lines where premiumization or sustainability claims are most likely to yield margin uplift rather than across-the-board capacity increases.
-
Use targeted partnerships: For companies lacking in-house circularity capabilities, partnerships (technology providers, recyclers, or traceability platforms) can reduce time-to-market and commercialize recycled offerings faster than organic development.
-
Quantify consolidation opportunities: Apply the report’s valuation and synergies templates to shortlist merger or alliance candidates that close capability gaps and extend reach into high-value channels.
Scope note and access to granular intelligence
This preview emphasizes strategic takeaways, macro trajectories and tactical imperatives. In keeping with our “trailer” approach — and to preserve the exclusive commercial value of the full dataset — we have intentionally withheld granular subsegment revenues, region-by-region breakdowns and application-level line items from this overview. The full PW Consulting report contains those detailed tables, proprietary demand curves, supplier scorecards and the model workbooks that underpin our forecast and scenario outputs.
Call to action
For executives planning 2026 budgets, supply-chain hedges, capex roadmaps or M&A pipelines, the full Acrylic Fibers Market study provides the granular intelligence and execution templates needed to convert market uncertainty into competitive advantage. Contact PW Consulting or visit our report page to access the complete dataset, company scorecards and the downloadable scenario workbooks.
For detailed analysis of this topic, please visit the official page: Acrylic Fibers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com