

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Textile Dyes Market Poised for 5.2% CAGR (2026–2032)

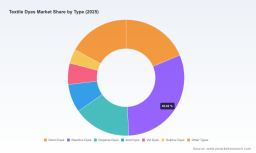
Textile Dyes Market — 2026 Strategic Outlook: A PW Consulting Preview
Introduction — why this preview matters for 2026 decisions
As companies prepare budgets, sourcing strategies, and product roadmaps for 2026, the textile dyes value chain sits at a strategic inflection point. Our Textile Dyes Market study (base year 2025) synthesizes supply‑side volatility, tightening regulation, and accelerating sustainability requirements into a clear line of sight on near‑term risk and opportunity. The global market reached approximately USD 1.19 billion in 2025 and, on the trajectory captured in our modelling, expands at a compound annual growth rate (CAGR) of 5.2% over the 2026–2032 forecast window. By 2032 the market approaches the upper end of our base‑case pathway, signaling meaningful, persistent demand for innovation, compliance services, and differentiated chemistries.
Textile Dyes Market
What the macro figures conceal — and why segmentation matters
Headline growth is necessary but not sufficient for decision quality. The aggregate numbers hide important dispersion across product types, end‑use channels, geographies, and value chain roles (raw material producers, specialty dyestuff formulators, colorants service providers, and finishing converters). Executives must therefore combine the headline growth story with granular, forward‑looking segmentation to prioritise capex, R&D, and commercial investments. This article sketches the strategic implications; the full report contains the detailed time‑series and cross‑tabbed splits companies will need to execute with confidence.
Textile Dyes Market
Key market dynamics shaping 2026
-
Regulatory acceleration — Compliance is the new minimum. Standards and regulatory activity have tightened materially: independent standard‑setters narrowed PFAS thresholds in early 2026, European restrictions on certain PFAS homologues are already in force, and the U.S. EPA’s rule banning specific organophosphate flame retardant articles will affect formulations and downstream article distribution from late 2026. These rules raise the cost of non‑compliance, increase verification demand, and shorten timelines for reformulation.
Textile Dyes Market -
Raw material and price volatility — Upstream inputs are unpredictable. Key intermediates showed price pressure in Q1 2026 and several producers announced meaningful list price increases for disperse dyes earlier in the year. The combination of intermittent feedstock tightness and spot price shock amplifies procurement risk for converters and brands operating thin margins.
-
Operational sustainability as competitive advantage — Product launches that lower effluent load and enable simpler compliance are moving from R&D to commercial scale. Early 2026 saw at least one major supplier release a cellulosic dye range that reduces effluent COD materially versus conventional grades; independent verification bodies and trade shows emphasise low‑PFAS outcomes. These developments compress time‑to‑value for buyers willing to pay a premium for reduced compliance and wastewater treatment burden.
-
Fragmented concentration with pockets of scale — The market remains moderately fragmented. A small group of global specialty chemical firms and regional manufacturers hold leadership positions, but a long tail of independent players and regional suppliers persists. This structure creates arbitrage for acquirers and partnership opportunities for firms seeking rapid access to capability or capacity.
Competitive landscape — who matters and why
The competitive map includes global specialty chemical leaders, regional incumbents with deep dye portfolios, and emerging innovators focused on sustainability. Notable participants we profile in the full study include established specialty chemical players with differentiated routes to market and R&D platforms, as well as regional Indian producers who serve cost‑sensitive segments and global converters that source across tiers.
-
Leading specialty firms drive the innovation agenda. Several heritage chemical companies are commercialising lower‑impact dye lines and performance adjuncts targeted at regulatory and wastewater constraints. These firms deploy integrated R&D, global trial capabilities, and certification partnerships to accelerate adoption.
-
Regional producers remain critical for pricing and fill‑rate. Manufacturers based in major textile hubs continue to influence pricing and provide rapid replenishment for fast fashion and contract manufacturing clients.
-
Services and verification specialists are becoming leverage points. Independent testing, certification, and supply‑chain auditing are scaling as brands demand traceability and demonstrable compliance.
Recent market signals (early 2026) and their strategic implications
-
Product innovation: A commercial launch of low‑COD direct dyes for cellulosics demonstrates that suppliers can materially reduce effluent burden while maintaining color performance. Strategic implication: buyers should fast‑track pilot programs to quantify total cost of ownership (TCO) impacts — not just price per kilo.
-
Price moves: Announcements of steep price increases for selected disperse dyes in early 2026 are a reminder that category‑specific shocks can cascade through finishing and conversion cost lines. Strategic implication: procurement teams must pair short‑term hedging with supplier diversification and formula flexibility.
-
Verification activity: Independent bodies and trade events now foreground PFAS‑free credentials and green‑mark certifications. Strategic implication: marketing and risk teams should treat certifications as risk mitigation and differentiation tools, coordinating product launches with verification milestones.
-
Regulatory enforcement: New limit values and bans change product acceptability timelines. Strategic implication: regulatory affairs should be embedded in product development and sourcing decisions rather than functioning as a post‑hoc clearance gate.
What the PW Consulting report delivers (practical contents)
Our full study is structured to move executive teams from insight to implementation. Deliverables include:
-
Market sizing and validated forecasts (2020–2032) with scenario corridors reflecting alternate regulatory and feedstock shocks;
-
Granular segmentation across types, applications, and regions — fully time‑series enabled (note: detailed splits and underlying tables are available in the subscriber report);
-
Supplier scorecards and capability maps for competitive benchmarking;
-
Regulatory impact matrix that converts rules into procurement and reformulation triggers;
-
Operational playbooks — procurement hedges, pilot evaluation templates, wastewater‑cost modelling, and a step‑by‑step product substitution checklist;
-
M&A and partnership screening logic for buyers looking to consolidate, diversify, or gain fast access to compliant chemistries;
-
Interactive dashboards that allow users to stress the model under custom inputs (feedstock inflation, accelerated regulation, and demand shocks).
Actionable strategic recommendations for 2026
-
Embed compliance into product margins: Recalculate product economics with compliance and wastewater treatment costs fully capitalised. That will reveal where premium repositioning or SKU rationalisation is required.
-
Accelerate pilot adoption of low‑effluent chemistries: Run controlled trials across representative SKUs to measure changes in effluent COD, rewash rates, and dye uptake; make procurement switches conditional on TCO improvements rather than per‑kg prices.
-
Hedge supply and feedstock risk: Use multi‑tier supplier contracts, reserve capacity agreements, and selective vertical integration where margin and strategic control justify capex.
-
Turn certification into client value: Coordinate product reformulation timelines with third‑party verification to convert compliance investments into commercial differentiation for retail clients concerned with traceability.
-
Pursue targeted M&A and partnerships: Look for bolt‑on capabilities that close compliance gaps (effluent‑reducing chemistries, local distribution footprints) rather than scale for scale’s sake.
-
Invest in data and traceability: Digital lot‑level traceability reduces recall risk and accelerates buyer approvals; prioritize investments with clear RIO within an 18–36 month horizon.
How to use this preview — next steps for leaders
This article is a strategic preview: it frames the market and signals where to focus resources in 2026. Executives preparing near‑term plans should use three concurrent workstreams: (1) run rapid portfolio stress tests against regulatory and feedstock scenarios; (2) pilot sustainable chemistries in 1–2 high‑volume SKUs to build operational confidence; and (3) align procurement contracts to include flexibility clauses and verification milestones. Our full report contains the detailed splits, supplier profiles, price series, and downloadable models that make these workstreams operational.
Closing
For companies active in the textile dyes chain, 2026 will be a year when compliance shifts from being a back‑office constraint to a front‑line business driver. The market’s steady expansion (CAGR 5.2% across 2026–2032) creates room for value capture — provided leaders move deliberately to de‑risk supply, adopt lower‑impact chemistries, and convert certification into commercial advantage. PW Consulting’s full Textile Dyes Market study supplies the data, scenarios, and playbooks required to translate those strategic choices into measurable outcomes. For access to the full dataset, granular segmentation tables, and downloadable decision tools, consult our complete report or contact the PW Consulting industry desk.
For detailed analysis of this topic, please visit the official page: Textile Dyes Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com