

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: ESP Market Set to Expand at 6.4% CAGR Through 2032

Electrostatic Precipitators (ESP) Market — Strategic Briefing for 2026
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present a focused pre-release briefing on our latest Electrostatic Precipitators (ESP) market study — engineered to equip C-suite and investment teams with the strategic context they need to act in 2026. This briefing demonstrates the analytical depth and actionable framing contained in the full report while intentionally preserving detailed segment-level figures to encourage direct access to the source intelligence.
Electrostatic Precipitators (ESP) Market
Executive snapshot — why ESP matters now
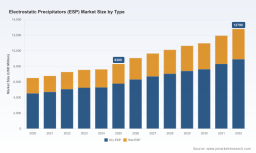
The ESP market is transitioning from a compliance-driven niche into a multi-dimensional, technology-enabled arena shaped by stricter emissions standards, energy and maintenance cost pressures, and the rapid uptake of digital control systems. Our analysis uses 2025 as the base year and shows the global market expanding from roughly USD 6.5 billion in early-decade terms to USD 8.3 billion in 2025, with a forecast compound annual growth rate (CAGR) of 6.4% across 2026–2032. By the end of the forecast window the market is expected to approach the low-double-digit billion range — a size that supports both organic scale plays and targeted M&A strategies for market entrants and incumbents alike.
Electrostatic Precipitators (ESP) Market
Strategic value of the 2026 study
- Decision-grade foresight: The report converts macro trajectory into decision-ready scenarios — retrofit vs new-build demand, fuel-mix sensitivities (coal, biomass, waste-to-energy), and regulatory shock scenarios. This lets procurement, asset management, and corporate development teams stress-test investment cases under alternative policy outcomes.
- Risk-to-reward mapping: We quantify the trade-offs between capital expenditures, lifetime operating costs (notably electrical energy consumption and maintenance for high-performance ESPs), and compliance benefits. That creates a transparent ROI ladder for different technology configurations and service models.
- Commercial playbook: For OEMs and service providers the study outlines go-to-market options — product differentiation (dry vs. wet systems and hybrid filtration), aftermarket and service revenues, digital retrofits, and bundling with gas-conditioning or NOx solutions — prioritized by short-term and medium-term impact.
- M&A and partnership guidance: The research identifies value pools where scale, technology and service capabilities create asymmetric advantages. It highlights acquisition targets and JV structures that accelerate access to end-markets and service ecosystems without requiring full-scale greenfield expansion.
Market trajectory and what it implies for 2026 strategies
Historical momentum through 2020–2025 shows steady growth driven by regulatory tightening and the need to modernize aging installations. The 6.4% CAGR we project for 2026–2032 is a reflection of sustained regulatory enforcement, incremental upgrades at existing sites, and an accelerating replacement cycle as digital control and hybrid filtration technologies mature. For corporate planners this trajectory suggests three practical implications:
Electrostatic Precipitators (ESP) Market
- CapEx planning should account for continued demand for both retrofit and replacement projects — a multi-year pipeline exists for utility and industrial customers.
- Service and aftermarket revenue streams will expand in relative importance; firms that industrialize spare-parts logistics and predictive maintenance stand to improve margins.
- Energy-efficiency and O&M cost optimization will be decisive differentiators — purchasers will pay a premium for solutions that demonstrably reduce life-cycle energy draw and maintenance intervals.
Dynamics shaping near-term demand
- Regulatory tailwinds: Recent and pending particulate and air toxics standards — including stringent limits for mercury and filterable particulate matter — are accelerating ESP deployments in regulated jurisdictions. Compliance timelines and inspection regimes are driving both replacement and augmentation projects.
- Cost and operational pressures: Advanced ESPs incorporate digital control modules and corrosion-resistant materials; while these raise upfront costs, they materially reduce downtime and increase collection efficiencies. The net present value of such investments is highly sensitive to local electricity prices and maintenance labor rates.
- Technology convergence: Integration with gas-conditioning systems, NOx reduction solutions, and AI-driven control systems is changing procurement decision criteria. Buyers increasingly evaluate systems on an integrated performance basis rather than discrete hardware metrics.
- Infrastructure constraints: Large-scale ESP installations have sizable electrical energy consumption and footprint implications; projects that can demonstrate lower operating energy and easier retrofittability have a competitive edge.
Competitive landscape — profiles and strategic postures
The market exhibits a mix of established engineering majors, specialized ESP manufacturers, and vertically-integrated industrial groups. Leading vendors combine installation scale, deep domain expertise, and service networks — but there is still room for differentiation through digital services, hybrid technologies, and targeted regional presence.
- Babcock & Wilcox Enterprises, Inc. — An acknowledged leader across wet and dry ESP systems with a long installed base and strong track record on high-efficiency collection. Recent large rebuild contracts illustrate their strength in lifecycle services and complex retrofit projects.
- DÜRR AG — Differentiates through integration expertise, combining ESP with broader gas cleaning systems for industrial environments. Their position benefits clients seeking bundled engineering solutions.
- Ducon Technologies Inc. — A nimble manufacturer offering custom wet and dry solutions for power, cement, and steel sectors. Competitive where project-specific engineering and flexibility matter.
- FLSmidth & Co. A/S — Strong in cement applications, with growing capabilities in AI-enhanced control systems and an expanding service footprint in the Middle East.
- Fuel Tech, Inc. — Carves out a niche by packaging flue gas conditioning and NOx reduction alongside ESPs — an attractive proposition for coal-fired utilities seeking integrated emissions control.
- GEECO Enercon GmbH, GEA Group AG, KC Cottrell, Monroe Environmental, Mitsubishi Heavy Industries, Sumitomo Heavy Industries, Trion, Valmet Oyj, Wood plc — Each brings specialized strengths: high-efficiency designs, food/chemical industry applications, wet ESP expertise, project delivery in large-scale power installations, and tailored pulp-and-paper solutions. Several have recent contract wins and network expansions signaling continued competition for large retrofit and new-build projects.
Recent market moves — multimillion-dollar rebuild contracts won by major incumbents, new service centers opening in growth regions, and targeted deliveries to pulp and chemical projects — all confirm that incumbents are mobilizing both product and aftersales footprints to capture a long-term upgrade cycle.
What the full report contains (practical, executable content)
- Market sizing and forecast model (2020–2032) with scenario variants for regulatory stringency and fuel-mix shifts.
- Segment-level economic models for technology types (dry, wet, hybrid) and major application verticals — including CAPEX/OPEX breakdowns and LCOE-style life-cycle analyses (note: detailed segment figures are reserved for the full report).
- Procurement and contracting playbook — templates for RFPs, performance-based contracting clauses, and warranty/service SLAs tailored to retrofit and greenfield projects.
- Vendor benchmarking toolkit — scorecards across technical capability, delivery track record, aftermarket reach, digital capabilities, and pricing power.
- Service and aftermarket optimization guide — strategies for spare-part logistics, remote monitoring, predictive maintenance algorithms, and margin capture through service tiers.
- M&A and partnership thesis — prioritized target archetypes, integration risks, and value-capture levers for roll-up or capability acquisitions.
- Regulatory heatmap and policy scenarios — jurisdictional timelines, enforcement risk assessment, and compliance cost modelling for major markets.
- Technology radar — maturity assessment for emerging innovations (e.g., hybrid filtration hybrids, advanced ionization approaches, AI-based controls) and estimated adoption waves.
Recommended executive actions for 2026
- Operationalize the retrofit pipeline: Align capital allocation to capture predictable retrofit demand; prioritize projects with rapid payback from efficiency and emissions reductions.
- Monetize services: Shift commercial models toward long-term service agreements and predictive-maintenance subscriptions to stabilize revenue and improve lifecycle margins.
- Invest in digital enablement: Deploy control-system upgrades and remote-monitoring capabilities that demonstrably reduce downtime and electrical draw — then use those metrics to win tenders.
- Pursue selective partnerships: Where in-house capabilities are limited, pursue JVs or technology partnerships to bundle ESPs with flue gas conditioning or NOx solutions, accelerating market access.
- Prepare for regulatory shocks: Maintain contingency scenarios for accelerated emissions standards; pre-qualify flexible solutions that can be rapidly deployed or retrofitted.
Conclusion — the PW Consulting advantage
This briefing captures the strategic contours of an ESP market that is substantial, growing, and undergoing technological and regulatory evolution. The full PW Consulting report turns this strategic context into executable plans, financial models, and competitive playbooks designed for boards, strategy teams, and commercial leaders planning for 2026 and beyond.
To access the complete set of segment-level analytics, vendor scorecards, and scenario models — including the granular datasets withheld from this preview — please consult the full market study on our website or contact your PW Consulting engagement lead.
For detailed analysis of this topic, please visit the official page: Electrostatic Precipitators (ESP) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com