

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Viscose Filament Yarns: 5.5% CAGR to USD 4,189M by 2032 - PW Consulting

Viscose Filament Yarns Market: Strategic Preview for 2026 Decision-Makers
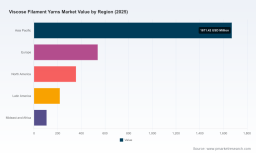
As the global apparel and nonwovens industries accelerate decarbonisation and circularity ambitions, viscose filament yarns (VFY) occupy a uniquely strategic position. PW Consulting’s latest market study — with a 2025 base year and a forecast window to 2032 — synthesises macro trajectory, commercial dynamics and executable playbooks that senior executives must consider when setting 2026 budgets, sourcing strategies and M&A priorities. The market reached roughly USD 2.89 billion in 2025 and, under our base scenario, is projected to grow at a 5.5% CAGR through 2032, approaching an endpoint north of USD 4.1 billion. What follows is a focused preview of the strategic insights contained in the full report: rigorous, actionable, and intentionally reserved on core split tables to guide you to the full dataset on our source page.
Viscose Filament Yarns Market
Why VFY Matters to Corporate Strategy in 2026
-
Material substitution and premiumisation: VFY sits at the intersection of cost-sensitive textile production and premium sustainability-led product positioning. Brands pursuing biodegradable, wood-based alternatives to synthetics find VFY attractive—if supply chains can deliver certified, traceable feedstock.
Viscose Filament Yarns Market -
Sustainability as a commercial lever: Regulatory changes and brand procurement policies elevate certified fibre content from a compliance checkbox to a revenue driver. The next 18–36 months will separate producers that can credibly verify fibre sourcing from those that cannot.
Viscose Filament Yarns Market -
Supply-chain concentration and resilience: Market concentration metrics in our study show meaningful consolidation among top players; this creates both negotiating power and systemic supply risk. Buyers, converters and investors should plan for capacity shifts and feedstock shocks.
Market Trajectory — What the Numbers Tell Us
Our top-line view maps historical movement from 2020 through 2025 and projects the market under scenario lenses to 2032. The base-case 5.5% CAGR reflects a balanced view of increasing brand uptake, regulatory tailwinds for certified materials, and persistent cost pressures from dissolving wood pulp and associated chemicals. Scenario modeling in the report quantifies sensitivity to key inputs — pulp price spikes, anti-dumping measures, and accelerated premium demand — enabling CFOs to stress-test capital allocation and working-capital plans across plausible outcomes.
Key Demand and Supply Drivers
-
Feedstock volatility: Dissolving wood pulp price fluctuations have direct pass-through effects to VFY margins. Recent quarter-over-quarter pulp moves in European markets underscore the need for disciplined procurement and hedging strategies.
-
Regulatory tightening: Major jurisdictions are moving toward stricter verification of sustainability claims. The EU’s Green Claims/Green Deal initiatives and parallel enforcement actions globally will raise the threshold for market access in branded apparel and home textiles.
-
Trade policy risk: Anti-dumping and trade remedy activity can rapidly reconfigure regional competitiveness and routing of volumes. Events in 2025–26 demonstrate how tariff and investigatory measures can alter supply economics for specific denier ranges.
What We Cover — Practical, Tactical, and Executable
The full study is structured to be a working toolkit for commercial, procurement, and strategy teams. Highlights include:
-
Market sizing and topline forecasting with sensitivity scenarios (base, downside, upside) to evaluate implications across pricing and volume pathways.
-
Segment and application analysis (by type, application and geography) with demand drivers, elasticities and growth vectors — presented as modelling modules you can adapt to company-specific parameters. Core split tables are available in the full report.
-
Supply-chain mapping and feedstock analytics: origin-to-yarn flows, dissolving pulp dependency analysis, cost buckets and a pulping-price shock simulator that quantifies margin impacts.
-
Commercial playbooks for producers and buyers: product differentiation, sustainability credentials, premium pricing frameworks, and channel-specific GTM tactics for 2026 rollout.
-
M&A and capacity strategy guidance, including a deal-screening matrix and capex benchmarking calibrated to typical VFY project economics across regions.
-
Regulatory and compliance roadmap: how to operationalise FSC/PEFC verification, chain-of-custody approaches, and Green Claims alignment to reduce market access risk.
-
Risk register and mitigation templates: supplier concentration, feedstock shocks, trade-policy scenarios, and reputational risk from unverified sustainability claims.
Competitive Landscape — Strategic Profiles and Implications
The market exhibits notable clustering among regional champions and global sustainability leaders. Our competitive module profiles the largest and most strategically active producers, analysing product portfolios, upstream integration, certification progress and recent strategic moves that matter to buyers and investors.
-
Grasim Industries Limited (Mumbai): A market leader in India with a broad branded portfolio that now includes traceable sustainability lines. New product launches targeting responsible sourcing strengthen its appeal to regional converters and domestic brands.
-
Jilin Chemical Fiber Co., Ltd. (Jilin): High-volume filament capacity and “next-generation” grades that blend FSC-certified wood with recycled feedstock position Jilin as a supplier of choice where scale and hybrid sustainability claims are required.
-
Xinxiang Bailu Chemical Fiber Co., Ltd. (Xinxiang): A vertically integrated Chinese player recognised for both conventional and specialty filament grades, with product breadth that supports textile and embroidery channels.
-
Yibin Grace Group Co., Ltd. (Yibin): Strategic investment in recycled dissolving pulp capacity signals a deliberate move to control feedstock circularity; this is a model others are likely to emulate or compete against in tender rounds.
-
Lenzing AG (Austria): The sustainability benchmark. Closed-loop processes and premium branded fibres continue to give Lenzing pricing power in premium segments and nonwovens applications where environmental claims are monetised.
-
Sateri Holdings Limited (Shanghai) and Sinopec Yizheng (Jiangsu): Large-scale producers with deep upstream integration and channel coverage across Asia and beyond; their logistics and feedstock capabilities underpin competitive pricing and reliable supply for big-volume buyers.
Concentration metrics from our study indicate a market where the top three and top five players hold material shares of production and influence. This creates a landscape where strategic alliances, long-term contracts and selective capex can meaningfully shift competitive advantage.
Recent Developments and Strategic Implications
-
Product innovation: Branded launches emphasising traceability and lower environmental impact are creating faster product lifecycles and new procurement specifications for retailers. Rapid labelling adoption will change assortment planning and supplier selection criteria in 2026.
-
Upstream integration: New dissolving pulp capacity dedicated to recycled-content streams reduces feedstock exposure and shortens certification timelines for firms that control pulp supply — a structural advantage in ESG-driven tenders.
-
Price dynamics: Regional price volatility tied to cellulose feedstock movements has periodically driven spot-price spikes. Buyers should evaluate forward procurement, formula-based contracts and physical hedges.
-
Trade policy: Anti-dumping investigations and provisional measures create immediate sourcing dislocations for certain deniers and product classes; scenario playbooks in the report quantify likely volume reroutes and margin impacts across trading corridors.
Actionable 2026 Priorities for Executives
-
Lock in feedstock pathways: Secure multi-source pulp supply and evaluate partial vertical integration where economics and scale justify it.
-
Certify early: Fast-track FSC/PEFC chain-of-custody or equivalent verification to avoid market access barriers and to capture premium tenders.
-
Implement price-risk frameworks: Use blended procurement contracts with indexed pricing and contingency buffers for input spikes.
-
Targeted M&A and JV screening: Prioritise assets that add certified feedstock, recycling capability or access to premium brand channels.
-
Differentiate product offerings: Develop graded portfolios (value, sustainable-premium, technical) tied to specific commercial channels and margin expectations.
-
Customer commitments: Offer verified sustainability guarantees for key retail partners with penalty/incentive structures to share transition costs.
-
Operational decarbonisation: Prioritise closed-loop water and solvent recovery projects with near-term paybacks to reduce both cost and regulatory exposure.
-
Scenario planning: Use the report’s stress modules to model 12–36 month capex and working-capital impacts under trade-disruption and high-pulp-price scenarios.
Conclusion — The Strategic Choice for 2026
Viscose filament yarns present a strategic opportunity for firms that can marry credible sustainability claims with reliable, cost-competitive supply. The market’s mid-single-digit CAGR masks important inflection points created by feedstock dynamics, regulatory tightening and supplier consolidation. PW Consulting’s full report provides the quantitative split tables, company-by-company benchmarking, and executable playbooks needed to translate these dynamics into 2026 decisions — from procurement commitments and capex allocation to M&A targeting and go-to-market strategies.
To access our full set of segmented tables, scenario models and vendor due-diligence templates, consult the source page for the comprehensive Viscose Filament Yarns Market report. The full dataset is intentionally granular — designed to convert insight into immediate, measurable action.
For detailed analysis of this topic, please visit the official page: Viscose Filament Yarns Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com