

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Digital Banking Market to Reach USD 3.71B by 2032

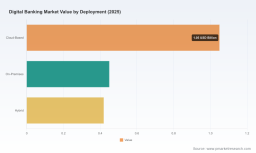
Digital Banking Market 2026: Strategic Imperatives for Decision Makers
Executive snapshot
As financial institutions race to reconfigure customer journeys, risk frameworks, and operating models, the Digital Banking Market has transitioned from a niche efficiency play into a strategic front for growth and resilience. Our latest PW Consulting study—anchored on a 2025 base year with a forecast horizon through 2032—maps the market’s trajectory, quantifies structural concentration, and translates macro trends into executable choices for 2026 boardrooms and executive planning cycles.
Digital Banking Market
Why this research matters in 2026
- Decision velocity: Institutions that can convert data-led insight into vendor, product and operational choices within the next 12–18 months will define competitive positioning across retail, SME and embedded finance channels.
- Regulatory inflection points: Shifts in US and EU rules are forcing architectural, data governance and underwriting changes that ripple through procurement, integration and product roadmaps.
- Technology convergence: AI, API-first design, and cloud economics converge to create new differentiation vectors—if institutions have the right roadmaps and TCO models to act.
Market trajectory — the macro facts you need
From a measurable base in 2020, the digital banking market has shown steady expansion through 2025 and is projected to continue growing at a compound annual growth rate of 8.5% over the 2026–2032 forecast window. This growth is not uniform: it is being driven by accelerating adoption of cloud-native platforms, API-led integrations and AI-enabled customer and operational tooling. Importantly, market concentration is material—our analysis indicates that the top three providers hold a significant share of revenues, and the top five concentrate an even larger portion—an important dynamic for procurement strategy and partnership design.
Digital Banking Market
What the report delivers — practical, board-ready outputs
Designed to inform capital allocation and execution plans in 2026, the report is explicitly operational. Key deliverables include:
Digital Banking Market
- Scenario-based market forecasts and sensitivity tests that translate macro growth (CAGR) into revenue, adoption and margin implications under three realistic paths (baseline, accelerated, downside).
- Vendor decision framework and RFP scorecards tailored to business archetypes (community banks, mid-tier regional banks, global institutions, fintech partners) to accelerate vendor shortlists and negotiation posture.
- Total cost of ownership (TCO) and migration models comparing cloud-first, hybrid and legacy approaches—calibrated to common balance-sheet and operational metrics.
- Regulatory impact matrices that map recent and pending rules to product design, data strategy and compliance roadmaps—complete with mitigation options and implementation timelines.
- AI adoption playbook including use-case prioritization, governance checkpoints and pilot-to-scale metrics to avoid common failure modes.
- Commercial and M&A playbooks: integration checklists, valuation adjustments for digital capabilities, and a shortlist methodology for tuck-in versus scale-up acquisitions.
- Benchmarks and KPIs drawn from primary interviews and vendor telemetry—delivered so leadership can set realistic performance targets and monitor vendor delivery.
Competitive landscape — who matters and why
The vendor field is a mix of long-established core providers, cloud-native disruptors, and internationally oriented infrastructure suppliers. Key strategic moves through late 2025 and the first half of 2026 have reshaped option sets for buyers and altered integration dynamics.
- CSI (Paducah, Kentucky) — A legacy core provider that has accelerated its digital agenda via acquisition and product launches. The integration of a modern digital front-end into its portfolio plus investments in AI-powered customer intelligence broaden its addressable value for community and regional institutions. This dual strategy—protecting incumbent core relationships while upgrading digital propositions—makes CSI a pragmatic choice for buyers prioritizing continuity with modernization.
- Lumin Digital (San Ramon, California) — A cloud-native player focused on AI-enabled experiences and performance tooling. Recent launches signal a move from proof-of-concept AI features to suites designed for production-grade personalization and operational optimization. For banks pursuing rapid time-to-market on customer experience initiatives, Lumin’s positioning is compelling—especially where integration with core systems can be streamlined.
- Thought Machine (London) — A pioneer in cloud-native core technology whose Vault platform remains attractive for institutions seeking to re-architect product factories. Its emphasis on modular core and payments primitives reduces product launch friction for organizations willing to undertake transformational migrations.
- nCino (San Mateo, California) — Provides cloud-based digital banking orchestration with rich CRM and fintech integration capabilities. Its strength lies in connecting front-office origination, credit and deposit experiences to broader ecosystems—a useful strategic choice where momentum is on relationship-led growth.
- SDK.finance (International) — A geographically diverse fintech infrastructure vendor that enables rapid deployment across regions. For institutions targeting cross-border product launches or for fintechs building white-label offerings, suppliers with international deployment expertise shorten time-to-market.
Recent commercial and product events—acquisitions of digital platforms, multiple AI and interface launches, and early-adopter deployments—have intensified vendor differentiation. Buyers should expect an active M&A environment and should prepare both procurement and integration teams for tighter timelines and higher premium for bundled digital-core offerings.
Regulatory and structural dynamics to plan around
- Data portability and API-first enforcement: Regulatory changes that required consumer financial data portability from 2025 have accelerated the adoption of API-first architectures. Institutions must now treat APIs as both a compliance requirement and a strategic distribution channel.
- Expanded open banking scope in Europe: New rules effective in 2026 widen the surface area for data sharing to include investment, pensions and insurance—creating both product opportunity and increased compliance complexity for cross-product offerings.
- Underwriting and credit risk guidance: New executive and regulator guidance on underwriting factors (including novel considerations around wage loss and borrower authorization status) requires immediate revision of credit models, approval workflows and audit trails for digital origination channels.
- Small-business reporting adjustments: Proposed changes to small-business lending reporting offer carve-outs for the smallest community banks, which will affect competitive dynamics in local markets and the cost-benefit analysis for compliance investments.
Strategic implications — a 2026 action checklist for executives
- Prioritize architectural clarity: Decide whether to adopt an API-first layer, re-platform the core, or pursue a hybrid transitional architecture—each path carries distinct cost and time trade-offs documented in our TCO models.
- Design governance for AI: Establish clear data, model and outcome governance before scaling personalization features. The report’s AI playbook identifies gating metrics and regulatory KPIs to keep pilots investment-grade.
- Re-evaluate vendor risk and concentration: Given the measured market concentration among top providers, incorporate counterparty and resilience clauses in vendor contracts, and plan for interoperability to avoid vendor lock-in.
- Embed regulatory change into product roadmaps: Use the regulatory impact matrices to sequence compliance workstreams alongside product releases to avoid costly rework.
- Operationalize partnership and M&A pipelines: Treat digital capability gaps as acquisition targets only after validating integration blueprints and realistic synergies, as detailed in our M&A playbook.
- Accelerate API monetization: Beyond compliance, APIs should be an explicit revenue design exercise—our commercial templates show how to price and package API access across partner segments.
How to use this study in your 2026 planning cycle
The report is structured to serve multiple stakeholders. Boards get a concise strategic narrative and scenario analysis; CFOs receive TCO and investment phasing models; CTOs and Heads of Digital receive vendor scorecards, migration playbooks and integration templates. Use the study as the core input to your 2026 operating plan, updating assumptions in quarterly cadence as vendor roadmaps and regulation evolve.
Why PW Consulting
Our advisory approach blends primary vendor diligence, executive interviews and quantitative market modeling calibrated to institutional KPIs. We do not offer generic checklists; instead, the study gives your team executable templates and decision-ready analytics designed to reduce procurement cycles and increase probability of successful implementation.
Final note — what we intentionally withheld
To preserve the “trailer” value of this introduction and to protect the report’s proprietary intelligence, we have intentionally withheld granular regional and product-split datasets, detailed vendor scorecard weightings, and the full spreadsheet models that underpin scenario outputs. These elements are available in the full Digital Banking Market report, which includes downloadable TCO models, vendor comparison matrices and raw-market tables to support procurement and diligence.
For senior executives preparing strategic choices in 2026—whether that means accelerating a cloud-first migration, selecting a partner for AI-enabled personalization, negotiating a platform acquisition, or re-designing credit underwriting for new regulatory expectations—this study is structured to be the single-point reference that turns insight into action.
For detailed analysis of this topic, please visit the official page: Digital Banking Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com