

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: 3D Reconstruction Market to Reach USD 2.6B by 2032 at 9.3% CAGR

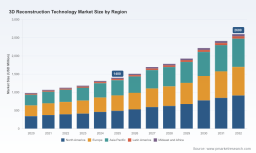
3D Reconstruction Technology Market: Strategic Intelligence for 2026 Decision-Makers
As PW Consulting’s Chief Industry Analyst, I present a focused briefing that positions our new 3D Reconstruction Technology Market study as an operationally useful tool for executive teams planning for 2026. Built on a 2025 base year and a 2026–2032 forecast horizon, the research synthesizes historical performance (2020–2025) with forward-looking scenario analysis. The market exhibits a multi-year compound annual growth rate (CAGR) of 9.3%, growing from roughly USD 980.5 Million in 2020 to an estimated USD 1,400.0 Million in 2025, and projected to reach approximately USD 2,600.0 Million by 2032. That pace of expansion is evidence of both maturing commercial use cases and accelerating adoption across adjacent verticals.
3D Reconstruction Technology Market
Why this research matters for 2026 decisions
-
Timing capital allocation: With a sustained ~9.3% CAGR and an anticipated near-doubling of market size through the early 2030s, the report helps CFOs and strategy teams prioritize CAPEX vs. OPEX for capture hardware, GPU-enabled compute, and software licensing across near-term and multi-year investment plans.
3D Reconstruction Technology Market -
Vendor selection under concentration dynamics: The market shows meaningful concentration among leading suppliers (top three and top five players account for a dominant share), shaping competitive strategy for partnerships, reseller agreements, and M&A. Understanding where platform incumbents control workflow lock-ins is essential when sourcing tools or negotiating exclusivity.
3D Reconstruction Technology Market -
Risk management and regulatory compliance: Recent regulatory milestones and fast-evolving privacy regimes change the cost and feasibility of field capture and medical use cases. The study translates these dynamics into compliance impact maps and procurement guardrails that legal, privacy, and product teams can operationalize by Q2–Q3 2026.
-
Scale-up playbooks for pilots: We identify the practical inflection points at which pilots stop being experimental and become operational — and what to budget for when moving from inspection and one-off scans to continuous digital-twin programs.
Report coverage — what you will find (practical deliverables)
-
Executive dashboards with validated market sizing and trend decompositions (2020–2025) and scenario-trace forecasts for 2026–2032.
-
Actionable vendor assessment frameworks that score suppliers across capture fidelity, end-to-end workflow integration, cloud/edge compute compatibility, data governance, and total cost of ownership.
-
Go-to-market playbooks for three archetypal buyers — engineering-led enterprises (infrastructure, manufacturing), healthcare systems, and media/entertainment producers — including procurement templates and pilot-to-scale milestones.
-
Technology roadmaps mapping trajectories for photogrammetry, LiDAR/laser scanning, structured-light systems, and real-time reconstruction driven by GPU and AI advances. Practical guidance includes compute sizing heuristics and latency budgets for live capture scenarios.
-
Regulatory & privacy compliance matrix addressing cross-border capture, storage, and processing requirements, and a checklist for embedding GDPR/CCPA principles into capture-to-cloud pipelines.
-
Financial tools: ROI calculators, sensitivity analyses (including input cost levers such as high-end cameras and GPU pricing), and break-even scenarios for common implementations (inspection, surgical planning, digital archiving).
-
Proven case studies and vendor negotiation playbooks that preserve confidentiality while highlighting implementation risks and the levers that delivered measurable labor and quality gains.
Competitive landscape — who matters and why
In our qualitative and quantitative analysis we profiling a curated set of solution providers spanning software, hardware, and integrated system levels. Key companies examined include (with HQ and primary focus):
-
Pix4D SA (Prilly, Switzerland) — photogrammetry software for drone and terrestrial mapping that emphasizes precision 3D models from imagery: strong in geospatial workflows and drone ecosystems ( https://www.pix4d.com/).
-
Agisoft LLC (St. Petersburg, Russia) — Agisoft Metashape is a mainstay for image-to-3D processing used across GIS, surveying, and heritage projects ( https://www.agisoft.com/).
-
3dMD (Atlanta, Georgia, USA) — specialized high-precision camera systems and software for human-form 3D/4D capture, with explicit applications in healthcare and research ( https://3dmd.com/).
-
Ricoh Company, Ltd. (Tokyo, Japan) — camera-based capture and AI-driven digital twin offerings that target XR and building documentation ( https://www.ricoh.com/).
-
Quidient LLC (Columbia, Maryland, USA) — developer of Generalized Scene Reconstruction (GSR) solutions for mobile-device-based virtual modeling ( https://quidient.com/).
-
Bentley Systems (Exton, Pennsylvania, USA) — integrates 3D reconstruction with BIM and digital-twin workflows for infrastructure and engineering use cases ( https://www.bentley.com/).
-
Trimble Inc. (Westminster, Colorado, USA) — hardware-software stacks for construction and geospatial applications, with strong field-to-office workflows ( https://www.trimble.com/).
-
Leica Geosystems AG (Heerbrugg, Switzerland) — high-accuracy surveying and photogrammetry equipment used where precision is non-negotiable ( https://leica-geosystems.com/).
-
Topcon Positioning Systems, Inc. (Fremont, California, USA) — surveying and mapping solutions tailored to construction and land management ( https://www.topconpositioning.com/).
-
Autodesk, Inc. (San Francisco, California, USA) — software ecosystem for point-cloud processing and model refinement, enabling integration with design and engineering workflows ( https://www.autodesk.com/).
-
FARO Technologies, Inc. (Lake Mary, Florida, USA) — 3D scanning and metrology systems for industrial reconstruction and QA ( https://www.faro.com/).
-
Matterport, Inc. (San Francisco, California, USA) — turnkey 3D imaging platforms for indoor digital-twin creation, combining cameras and cloud processing ( https://matterport.com/).
-
NavVis GmbH (Munich, Germany) — mobile laser scanning for indoor mapping and navigation ( https://www.navvis.com/).
-
Emergent Vision Technologies (Nashville, Tennessee, USA) — high-speed industrial cameras enabling real-time reconstruction ( https://emergentvisiontec.com/).
Our competitive analysis is structured to expose where vendors compete on capture fidelity, algorithmic differentiation, platform openness, and enterprise-grade support. Important dynamics include vertical specialization (e.g., healthcare vs. construction), horizontal platform plays (cloud/edge ecosystems), and distribution models (OEM, channel, SaaS). The concentration metrics in the market — where top-three and top-five providers hold a material portion of share — reinforce that strategic partnerships or targeted acquisitions remain viable routes to scale quickly.
Industry dynamics and near-term catalysts
-
Regulatory and reimbursement shifts: Regulatory approval for 3D-printed medical devices is unlocking new commercial pathways; healthcare payers and clinical protocols are increasingly receptive to 3D reconstruction-based planning and implant design. Concurrently, privacy regimes such as GDPR and CCPA impose operational constraints on capture and storage workflows, and the report details practical data governance controls for compliance.
-
Technology constraints and cost levers: High-end cameras and GPUs are the primary equipment and computational bottlenecks for real-time, high-fidelity reconstruction. The report quantifies sensitivity to these input costs and offers mitigations — e.g., hybrid local/edge inference, batch processing strategies, and capture-quality thresholds tied to specific use cases.
-
Demonstrable operational value: Automation in photogrammetry and point-cloud analysis is delivering meaningful labor reductions in industrial inspection — we document observed reductions in manual measurement labor of roughly 70–80% in assembly and inspection workflows and translate those into procurement and ROI decision models.
-
Emerging applications and grants: Public-sector and defense-funded research programs are accelerating capabilities for difficult capture scenarios (for example, satellite and space-debris reconstruction from limited 2D views), while trade-show announcements and regulatory clearances are expanding commercial applications such as dental and prosthetic manufacturing.
Strategic recommendations for 2026
-
Adopt a capture-to-cloud architecture that separates sensor procurement from analytics: buy sensors on quality tiers, reserve heavy algorithmic differentiation for software or IP you control.
-
Budget for GPU and storage as first-class line items: treat compute and data retention as operational assets rather than incidental costs.
-
Embed privacy and consent controls into capture workflows now — retrofitting compliance is costly and slows adoption.
-
Design pilot programs with explicit scale gates: define fidelity, throughput, and SLA thresholds that trigger broader rollout or vendor rebid.
-
Evaluate M&A or partnership to close gaps in enterprise-grade services (support, SLAs, integration with BIM/PLM systems). Where top providers dominate, consider niche vertical plays that can be wrapped into larger offers.
-
Stress-test pricing models against input-cost scenarios (camera depreciation, GPU price fluctuations) and regulatory frictions to determine sustainable margins for recurring services.
Next steps — how to use the full study
This briefing intentionally highlights the strategic implications and operational frameworks while withholding granular sub-segment numbers, regional share breakdowns, and vendor revenue-by-segment — content that appears in the full PW Consulting study. For procurement teams, investment committees, and product leaders preparing 2026 budgets, the complete report provides the detailed datasets, downloadable financial models, sensitivity matrices, and vendor scorecards you will need to convert the strategic guidance above into executable plans.
PW Consulting’s 3D Reconstruction Technology Market study is built to be a playbook: combining validated market sizing, scenario planning, and tactical execution tools to accelerate confident decision-making in 2026. Access the full analysis to obtain segment-level intelligence, proprietary vendor benchmarks, and customizable ROI tools that underpin board-ready investment cases.
For detailed analysis of this topic, please visit the official page: 3D Reconstruction Technology Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com