

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Peristaltic Pump Market (2026-2032): Asia Pacific leads at USD 845.3M, 6.2% CAGR

Peristaltic Pump Market — Strategic Imperatives for 2026 Decision-Making
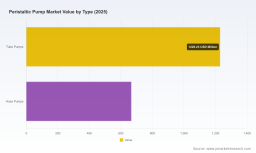
PW Consulting’s newest Peristaltic Pump Market study (base year 2025; historical 2020–2025; forecast 2026–2032) is built for executives who must translate engineering nuance, regulatory complexity, and shifting end‑market demands into executable commercial and investment plans for 2026. The market has demonstrated steady expansion through the first half of the decade, growing from roughly USD 1.45 billion in 2020 to approximately USD 1.90 billion in 2025, and our forecast trajectory — a compound annual growth rate of 6.2% — points to sustained upside through 2032 (ending near USD 2.84 billion in our central case). Those headline figures capture momentum, but 2026 will be the year when strategy must move from high‑level optimism to operational clarity. This study is designed to bridge that gap.
Peristaltic Pump Market
Why this study matters in 2026
-
Convergence of regulation and demand: Peristaltic pumps occupy a unique nexus between regulated sectors (pharmaceuticals, medical devices, food) and heavy‑duty industrial uses (chemical, wastewater, mining). Recent regulatory actions — from stricter FDA validation guidance for pumps used in biomanufacturing, to USP and FDA compliance expectations for tubing materials — are not academic; they alter qualification timelines, supplier selection, and total cost of ownership. Our study maps those regulatory inflection points and quantifies their operational implications for device OEMs, process engineers, and procurement teams.
Peristaltic Pump Market -
Product technology bifurcation: The market is increasingly stratified between hygienic, single‑use and precision lab pumps on one hand and heavy‑duty hose/tube solutions engineered for abrasive or hazardous fluids on the other. This divergence affects service models, margin structures, and aftermarket revenue pools — critical considerations when prioritizing R&D spend or distribution investments in 2026.
Peristaltic Pump Market -
Supply chain and materials risk: Medical‑grade tubing (silicone and specialty polymers) with USP Class VI/FDA/GMP certification is a gating item for many end users. Our research identifies where bottlenecks exist in the tubing supply base and how validation cycles for sterilization methods (e.g., EO or high‑temperature sterilization) can create lead‑time risk for device manufacturers and integrators.
-
Regulation‑driven addressable demand: Policy levers can meaningfully reshape procurement flows. As a practical example, CMS pass‑through decisions for certain pump‑based infusion systems and the continued implementation of EU MDR changes create pockets of incremental demand — and compliance costs. The study quantifies how these shifts propagate through purchasing, validation, and aftermarket support.
What the report delivers — practical, transaction‑ready intelligence
-
Market sizing and forecast model (2020–2032): rigorous, transparent assumptions with scenario switches for conservative, central, and upside cases — enabling rapid re‑calibration to your internal planning cycles.
-
Demand drivers and dynamics: regulatory timelines, end‑user adoption patterns across pharma/medical, water & wastewater, food & beverage, chemical processing, and industrial segments, plus the interaction between single‑use and reusable system economics.
-
Supply chain diagnostics: raw material qualification matrices, supplier concentration indicators, cost‑build analytics for tubing and elastomers, and mitigation playbooks for supply disruption.
-
Commercial playbooks: go‑to‑market archetypes by channel (OEM, distributor, direct), pricing elasticity sketches, after‑sales and service revenue levers, and a vendor selection scorecard you can apply to vendor due diligence.
-
Competitive and M&A landscape: company dossiers, product positioning maps, technology clustering, and an M&A target shortlist — with suggested valuation sensitivity tests keyed to recurring consumables and service revenue.
-
Implementation toolkits: checklist templates for qualification/validation, procurement RFx outlines, CapEx/Opex models for new plant integration, and KPIs for field service networks and spare parts logistics.
Competitive landscape — what practitioners need to know
The market structure is moderately fragmented — our concentration analysis shows that the top three players do not dominate the market, and the top five hold under half of total revenue. That degree of fragmentation creates both opportunity and complexity for 2026: opportunity to consolidate capability at attractive multiples, and complexity when selecting partners that can deliver validated materials and global service footprints.
-
Established OEMs with industrial depth: Companies such as Graco and NETZSCH are noteworthy for robust offerings that target caustic, abrasive, or heavy‑duty process environments. Their engineering bias is toward durability and high throughput.
-
Life‑science specialists: Watson‑Marlow and IDEX Health & Science maintain leadership where bioprocessing, sterile handling, and traceable materials dominate procurement decisions. These vendors are often first choice for validated pharma lines and single‑use workflows.
-
Water & dosing specialists: ProMinent, Blue‑White, and Stenner focus on dosing and treatment solutions with strong aftermarket and service economics tied to consumables and calibration services.
-
Hose and heavy‑duty players: Wanner, Flowrox and other hose‑pump specialists are the go‑to for slurries, viscous media, and abrasive fluids where tube life and mechanical robustness trump disposable consumable models.
-
Regional and OEM OEM/volume players: Multiple Asia‑based manufacturers provide competitive pricing and OEM partnerships, increasingly adding product certification options including explosion‑proof and medical‑grade lines for broader market reach.
Recent market events underscore these dynamics: new product launches aimed at hazardous environments, regulatory enforcement tightening validation for biomanufacturing pumps, and discrete medical device clearances integrating peristaltic pump ports all signal that technical compliance and integration capability will be differentiators in 2026.
Strategic recommendations for 2026
-
Prioritize compliance‑led differentiation: For product teams, build validation roadmaps aligned to the latest FDA and USP expectations. Being first to deliver validated pump + tubing solutions significantly shortens time‑to‑qualification for downstream customers.
-
Lock downstream consumables: For commercial leaders, secure multi‑year agreements with certified tubing suppliers; the economics of peristaltic systems often flip in favor of vendors who can guarantee consumable availability and traceability.
-
Invest in modularization and digital enablement: Field service costs can be materially reduced via modular pump architectures and predictive maintenance enabled by sensor and analytics overlays — prioritize retrofit kits that monetize installed bases.
-
Service and spare‑parts network as a moat: Aftermarket revenue and rapid field response are decisive in regulated sectors; invest in regional service hubs if you expect to pursue pharma or water treatment accounts at scale.
-
M&A focus areas: Look for targets that (a) secure consumable supply chains, (b) add validation expertise for regulated segments, or (c) broaden distribution in attractive geographies. With the market moderately fragmented, opportunistic consolidation can deliver rapid scale.
-
Scenario planning: Use the report’s scenario outputs to stress‑test 2026 procurement commitments under differing validation timelines, regulatory updates, or raw‑material constraints.
How to use this study in your 2026 planning cycle
Think of PW Consulting’s Peristaltic Pump Market study as an actionable decision pack: embed the forecast model into your FY‑26 budget process, use the vendor scorecards in your supplier due diligence, apply the validation checklists to product release timelines, and leverage the M&A signal maps to prioritize targets. Our appendices provide the building blocks — templates, scoring sheets, and model inputs — so that teams can move from insight to execution within weeks, not months.
The analysis presented here is intentionally selective: we surface structural trends, regulatory catalysts, supplier archetypes, and a clear set of playbooks that will influence 2026 outcomes. For detailed segment breakouts, regional and application level demand curves, and the full company‑level financial and product matrices that underpin our valuation and M&A guidance, please consult the full report. That granular intelligence is the differentiator for teams preparing commercial bids, capital projects, or acquisition offers this year.
PW Consulting stands ready to translate the report’s findings into operational plans, vendor negotiations, or acquisition diligence. If your 2026 agenda includes launching validated pump platforms, scaling service networks, or making acquisition decisions in peristaltic pump technologies, this study is the strategic reference that will shorten execution timelines and reduce commercial risk.
For detailed analysis of this topic, please visit the official page: Peristaltic Pump Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com