

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: RF Front-End Module Market Hits USD 22.1B in 2025; 10.04% CAGR to 2032

Radio Frequency Front-end Module Market: Strategic Playbook for 2026 Decision‑Makers
Market snapshot — why this moment matters
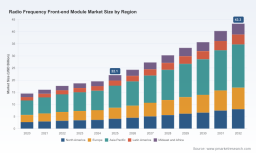
The RF front‑end module market has moved from a supporting role into the center of competitive differentiation across mobile devices, access infrastructure, automotive connectivity and expanding IoT endpoints. After a compound period of steady expansion from 2020 through 2025 — rising from approximately USD 14.5 billion to USD 22.1 billion — the market enters the 2026 planning cycle with a structural acceleration. Our base forecast uses 2025 as the anchor and models a mid‑single‑digit to low‑double‑digit compound annual growth trajectory across 2026–2032, equating to a +10.04% CAGR that drives the market toward roughly USD 43.3 billion by 2032.
Radio Frequency Front-end Module Market
For executive teams setting budgets, negotiating supplier agreements, or assessing M&A targets in 2026, these dynamics translate into three immediate implications: faster revenue pacing for differentiated RF solutions; widening margin dispersion between commodity and high‑value subsystems; and an increasingly strategic role for supply‑chain decisions tied to specialty materials and foundry capacity.
Radio Frequency Front-end Module Market
What this PW Consulting report delivers — practical intelligence for 2026 decisions
- Actionable market sizing and forecast model (2020–2032) built on component‑level cost stacks, adoption curves and technology substitution scenarios — delivered with an interactive model that keeps the headline totals visible while preserving the granular slices for licensed access.
- Scenario playbooks that stress‑test market outcomes under three near‑term vectors: accelerated GaN adoption, constrained compound semiconductor capacity, and an infrastructure‑led 5G refresh driven by Wi‑Fi 7 and mmWave densification.
- Procurement and sourcing heat maps that translate raw‑material, tariff and lead‑time risks into prioritized mitigation steps — from dual‑sourcing and strategic inventory to nearshoring and collaborative R&D with foundries.
- Corporate benchmarking and a supplier scorecard that evaluates design capabilities, integration depth, manufacturing footprint, and commercial resilience — aligned to buyer needs in consumer, automotive and infrastructure segments.
- Go‑to‑market roadmaps and partnership architectures for chipset vendors, module assemblers and OEMs that balance time‑to‑market with capital intensity and IP control.
- M&A and investment thesis playbooks identifying capability gaps, integration risks, and valuation sensitivities specific to RF front‑end technologies and assets.
Competitive landscape — what the leader set tells us
The supplier ecosystem is populated by long‑standing semiconductor houses, component specialists and hybrid integrators. We observe three strategic archetypes among the leading vendors:
Radio Frequency Front-end Module Market
- Highly integrated module specialists who leverage substrate and packaging expertise to deliver ultra‑compact, low‑loss modules for mobile and consumer endpoints.
- Broad semiconductor platform players that couple RF front‑end modules with SoC or transceiver ecosystems, strengthening supply relationships with major OEMs and infrastructure vendors.
- Performance‑focused RF houses that prioritize high‑power and mmWave solutions for infrastructure, satellite and radar, often accelerating capability through targeted acquisitions.
Representative players illustrate these archetypes and the competitive tradeoffs to consider in 2026:
- Murata concentrates on ultra‑small integrated modules, a design and packaging lead that continues to pay off in space‑constrained consumer products. Recent capacity expansion initiatives point to a strategic bet on volume projects where integration and yield discipline matter.
- Broadcom leverages platform scale and supply relationships to secure high‑volume smartphone and infrastructure business. Strategic supply agreements with major OEMs underline its advantage in commercial reach and logistics integration.
- Skyworks and Qorvo bridge consumer and automotive demand with solutions optimized for power efficiency and carrier aggregation. Qorvo’s acquisitions and product launches demonstrate an explicit push into mmWave and Wi‑Fi 7 access point markets — an important signal for buyers evaluating future‑proof supplier roadmaps.
- Qualcomm, NXP, Infineon and the major analog houses position RF front‑end offerings alongside broader silicon portfolios, reducing integration friction for OEMs who prefer single‑vendor stacks but raising questions about supplier dependency and long‑term pricing leverage.
- Regional specialists and passive/component suppliers remain critical: their substrate, filter and antenna‑matching expertise materially affects module performance and cost, particularly as frequency bands multiply.
Supply‑chain and technology dynamics that will shape 2026 outcomes
Three interlinked dynamics dominate near‑term risk and opportunity:
- Material concentration and technology substitution. Restrictions on strategic feedstocks — notably gallium — have already tightened GaN wafer availability and elevated spot pricing. That dynamic is prompting OEMs and module vendors to accelerate dual‑sourcing strategies, qualify alternative foundries, and re‑evaluate the pace of GaN migration versus established compound‑semiconductor approaches.
- Manufacturing bottlenecks and lead‑time inflation. Compound semiconductor capacity constraints and passives supply volatility have extended lead times through 2025–2026. Buyers must decide in 2026 whether to prioritize long‑lead contract capacity, invest in co‑development fabs, or accept modular redesigns to avoid pinch points.
- Geopolitical and regulatory complexity. Export controls, tariffs and regional policy shifts increase the cost of cross‑border assembly and distribution for RF front‑end supply chains. Firms that proactively align manufacturing footprints and contractual terms with expected policy scenarios will retain market access and avoid disruptive replacement costs.
Strategic implications for 2026 planning
Executives and commercial teams must translate market momentum and supply risks into practical 12–24 month actions. Our research highlights the following priority choices:
- Sourcing and inventory posture. Convert supply‑risk intelligence into tiered procurement playbooks: immediate qualification of alternate GaN sources; establishment of safety stock bands for critical passives; and conditional rollover agreements with strategic suppliers to lock capacity without overcommitting capital.
- Product and architecture decisions. Distinguish roadmap bets between high‑value differentiated modules (where customization and co‑design pay) and commodity RF decks (where cost discipline and multi‑source strategies dominate). For OEMs, the question in 2026 will be how many RF‑related subsystems to internalize versus outsource.
- Partnership, M&A and capex allocation. Targeted acquisitions or joint ventures in mmWave, GaN fabrication, or filter/passive capacity are defensible if they shorten lead times and protect gross margins. Our model identifies where vertical moves improve economics versus where strategic supply contracts offer a better risk/cost profile.
- Commercial contracting and price escalation levers. Design supply contracts with indexed pricing triggers, capacity reservation clauses, and shared‑investment mechanisms for tooling or NPI lines to align incentives across the supplier value chain.
How PW Consulting helps unlock tactical advantage in 2026
This report is designed as a working tool for executives who need more than directional commentary. It embeds competitive intelligence, supply‑chain diagnostics and scenario modeling in formats you can use directly: negotiation playbooks, product roadmap stress tests, and an M&A filter tuned to RF front‑end economics. We intentionally surface strategic levers and risks while reserving the granular segmentation tables, vendor scorecards and the interactive forecast model for the full report — because those elements are the tactical currency teams will deploy during 2026 planning cycles.
Immediate next steps we recommend
- Prioritize a rapid supplier risk review for components using GaN or other constrained substrates; establish at least one qualified secondary source by Q3 2026.
- Run a 90‑day product architecture audit to identify modules where integration versus outsourcing materially affects time‑to‑market and margin trajectories.
- Update procurement contracts to include capacity reservation and price indexation clauses reflecting material volatility and lead‑time risk.
- Use the PW Consulting interactive model to quantify the financial impact of alternate GaN adoption paths and to stress‑test M&A scenarios under different supply‑chain shock assumptions.
RF front‑end modules are now a core strategic battleground: the design, supply and sourcing choices made in 2026 will reverberate through product roadmaps, gross margin profiles and market share through the next technology cycle. Our full market study contains the detailed segmentation, supplier scorecards and downloadable forecast model you need to operationalize these conclusions. Contact PW Consulting to access the complete research and the interactive tools that your 2026 teams will use to convert market momentum into defensible advantage.
For detailed analysis of this topic, please visit the official page: Radio Frequency Front-end Module Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com