

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Ethanolamine Market to Reach USD 5,468M by 2032 at 4.9% CAGR | PW Consulting

Ethanolamine Market 2026: Strategic Imperatives from PW Consulting’s Forward-Looking Analysis
As companies prepare strategies for 2026, the ethanolamine market presents a complex mix of steady growth, cost volatility, and a reshaping competitive landscape driven by feedstock dynamics and regulatory pressure. PW Consulting’s latest ethanolamine market study — anchored on a 2025 base year and spanning historical performance (2020–2025) and a 2026–2032 forecast horizon — synthesizes commercial intelligence that senior decision-makers need to convert ambiguity into competitive advantage.
Ethanolamine Market
Why this study matters for 2026 decision cycles
-
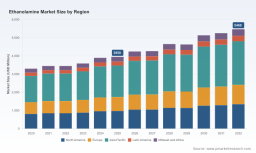
Market trajectory and timing: The global ethanolamine market reached approximately USD 3,950 Million in 2025 and is projected to grow at a compound annual growth rate (CAGR) of 4.9% through the forecast period, reaching the mid‑five‑thousand‑million range by 2032. This steady, investment‑grade growth profile changes the calculus for capacity additions, integration moves, and portfolio rebalancing.
Ethanolamine Market -
Margin pressure and supply tightness: Converging cost and supply signals in early‑ to mid‑2026 will force commercial teams to re‑price and re‑negotiate. Leading producers have already signalled price adjustments; understanding the pass‑through mechanics and contract levers is now a top priority for procurement and sales leaders.
Ethanolamine Market -
Regulatory inflection points: New significant‑use rules and sustainability standards are shifting capital allocation toward bio‑routes and certified feedstocks. Firms that move early to de‑risk regulatory exposure and offer verifiable Scope 3 benefits will capture premium positioning with downstream customers.
What the report delivers (actionable, not academic)
-
Integrated market sizing and scenario forecasts: Multi‑scenario demand models that reflect near‑term cost shocks, substitution risks, and end‑market elasticity. These are calibrated to our base year (2025) and extend across the 2026–2032 forecast window to support 3–7 year strategic planning.
-
Commercial playbooks: Go‑to‑market frameworks for producers, distributor strategies for regional players, and procurement playbooks for large industrial buyers — including pricing architecture, contracting tactics, and hedging approaches for feedstock volatility.
-
Capex and capacity planning guidance: Investment decision templates, IRR sensitivity maps, and near‑term capacity deployment scenarios that reflect realistic lead times, permitting risk, and feedstock availability constraints.
-
Regulatory and ESG roadmaps: Practical steps to align product portfolios with evolving regulatory requirements and customer sustainability targets — including supplier certification routes, Scope 3 emissions strategies, and innovation pipelines centered on lower‑carbon production.
-
M&A and partnership playbooks: Due diligence checklists, valuation stress tests and integration blueprints tailored to the ethanolamine value chain (from EO integration through downstream amine derivatives).
-
Risk register and mitigation matrices: Quantified short‑ and medium‑term risks (price, feedstock, regulation, logistics) with prioritized mitigation actions and contingency triggers tailored to different company archetypes.
Competitive landscape — what incumbents and challengers are doing
The ethanolamine market is moderately concentrated, with the top three companies accounting for a substantial share of global capacity and the top five increasing that concentration incrementally. This market structure supports coordinated commercial behaviour during periods of cost pressure while leaving room for mid‑tier and regional players to carve differentiated positions through specialization and sustainability credentials.
-
BASF SE (Ludwigshafen, Germany) — A global leader with broad ethanolamine product lines and recent strategic capacity investments. BASF’s September 2025 expansion of alkyl ethanolamines at its Antwerp site materially increases its supply flexibility, especially into industrial applications such as gas treating and specialty urethanes. Their recent commercial communications in 2026 indicate active margin management through price realignment in response to feedstock and operational cost pressures.
-
Dow Inc. (Midland, Michigan, United States) — Dow combines global scale with backward integration into key intermediates and has publicly announced price adjustments in early 2026. Their integrated model supports resilience to short‑term feedstock swings and provides a platform for bundled offers into surfactant and detergent value chains.
-
INEOS Group Ltd. (London, United Kingdom) — A significant producer that has strengthened ethanolamine supply via strategic acquisitions. INEOS has signalled commercial tightening with pricing actions in 2026, reflecting a broader industry response to evolving supply dynamics.
-
Huntsman Corporation (The Woodlands, Texas, United States) — Focused on industrial and consumer application segments, Huntsman operates with regional footprint advantages that favor agility in contract negotiation and customer technical support.
-
Nouryon (Amsterdam, Netherlands) — Differentiates through specialty chemistries and sustainability certification. Nouryon’s ISCC PLUS certified routes give it a competitive edge with customers prioritizing proven Scope 3 emissions reductions.
Recent commercial and operational signals to watch (early 2026)
-
Producers across the board have implemented price increases in the first quarter of 2026 in response to rising input and operational costs — a clear signal that cost pass‑through remains feasible given current demand dynamics.
-
Capacity shifts have been focused on higher‑value alkyl ethanolamine derivatives, reflecting producers’ intent to move up the value chain and protect margins against commoditization.
-
Supply‑side adjustments are being complemented by downstream buyers accelerating sustainability sourcing mandates, prompting investment in certified feedstock routes and supplier consolidation.
Feedstock, regulation and cost dynamics — the drivers of margin compression and opportunity
Two structural drivers deserve particular attention. First, regional divergence in raw material pricing and availability is creating asymmetry in regional cost curves; companies with flexible sourcing or upstream integration are better placed to protect margins or selectively pursue market share. Second, regulatory interventions and sustainability frameworks are accelerating the shift to low‑carbon feedstocks and certified supply chains. The combination of these forces is driving both short‑term price volatility and long‑term structural winners and losers.
For procurement teams and financial sponsors, the implication is clear: decisions on long‑lead investments, contract durations, and hedging should be stress‑tested against scenarios that combine tighter regulatory requirements with episodic feedstock shocks.
Where strategic value sits — four priority moves for 2026
-
Prioritize feedstock optionality: Secure diversified EO and ammonia sources, explore tolling and JV options, and quantify the value of vertical integration versus contractual flexibility.
-
Monetize sustainability: Move beyond compliance — offer certified product streams, price differentiated SKUs, and align commercial incentives with downstream customer decarbonization roadmaps.
-
Quality over volume in capacity additions: Target higher‑margin derivatives and tailored amine blends rather than undifferentiated capacity, using our IRR sensitivity models to size projects.
-
Use procurement as a strategic node: Convert short‑term price adjustments into long‑term supplier rationalization or co‑innovation partnerships that lock in feedstock access and innovation advantages.
What we intentionally leave for subscribers — the “trailer” effect
This overview is designed to expose the intellectual scaffolding and practical value of PW Consulting’s full ethanolamine market study while withholding the granular segmentation tables, regional/application percentage breakdowns, and line‑by‑line supplier capacity figures that commercial teams use for contract-level decisions. The full report contains these detailed datasets, scenario‑specific demand curves, and supplier scorecards that operational teams rely on to execute pricing, sourcing, and M&A plays.
How to use this analysis in 90 days
-
Board level: Integrate the 4.9% CAGR baseline and our scenario ranges into capital allocation discussions and update the rolling three‑year strategy with supplier risk heatmaps.
-
Commercial teams: Recast price corridors and contract indices to reflect the new cost pass‑through dynamics and put in place customer segmentation that captures sustainability premiums.
-
Operations and supply chain: Initiate feedstock diversification programs and fast‑track any ISCC or equivalent certification audits for plants targeting sustainability‑sensitive end markets.
-
M&A teams: Use our due diligence templates to stress‑test target valuations under regulated and high‑cost scenarios; prioritize assets that offer integration into higher‑value derivative streams.
Conclusion — the strategic takeaway
The ethanolamine market in 2026 is neither a runaway boom nor a stagnant commodity market; it is a structurally attractive, medium‑growth sector marked by episodic cost pressure, selective capacity additions, and accelerating sustainability requirements. Companies that combine disciplined feedstock strategies, targeted value‑chain moves, and credible sustainability credentials will convert the market’s steady CAGR into outsized economic returns.
For teams preparing budgets, deal pipelines, or operational plans this year, the decisions made now — on sourcing flexibility, product differentiation, and certification paths — will determine competitiveness through 2032. PW Consulting’s full ethanolamine market study provides the granular inputs and executable playbooks to operationalize these insights; access to the complete data and supplier analytics is available via our report subscription page.
For detailed analysis of this topic, please visit the official page: Ethanolamine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com