

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Potassium Acetate Market to Hit USD 203.76M by 2032 at 4.32% CAGR

Potassium Acetate Market — Strategic Briefing for 2026 Decision-Making
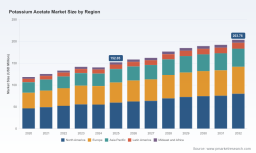
As companies recalibrate portfolios for the mid-2020s, potassium acetate emerges as a small but strategically important chemical with cross-cutting exposure to pharmaceuticals, food ingredients, de-icing, and industrial applications. PW Consulting’s latest market research (base year 2025; historical 2020–2025; forecast 2026–2032) quantifies that the global potassium acetate market expanded from about USD 118 million in 2020 to roughly USD 152 million in 2025, and — under our base case — is projected to reach approximately USD 204 million by 2032, implying a compound annual growth rate of 4.32% through the forecast horizon. This briefing explains why those headline numbers matter to executives planning capacity, procurement, compliance, and M&A strategies in 2026 — and which high‑impact levers will determine who captures value over the next six years.
Potassium Acetate Market
Why potassium acetate matters now
- Regulatory inflection points: Rapid regulatory shifts (notably PFAS restrictions in Europe and increasing PFAS scrutiny in North America) are accelerating substitution away from chloride- and fluorine-based deicers toward acetate-based, PFAS-free solutions — creating near-term demand elasticities for high-purity liquid and formulated potassium acetate.
- Spectrum of end markets: Unlike commodity salts, potassium acetate spans pharmaceutical excipients, food processing aids, specialty industrial formulations (e.g., oilfield, de-icing), and laboratory reagents. This diversity smooths aggregate volatility but requires differentiated go‑to‑market models and certifications.
- Moderate market concentration: The supplier landscape is neither a pure commodity oligopoly nor atomized: leading firms command meaningful share but mid‑tier and regional manufacturers remain commercially relevant — a structure that rewards strategic partnerships and targeted investments.
Interpreting the headline trajectory (2020–2032)
The market’s rise from ~USD 118 million in 2020 to ~USD 152 million in 2025 reflects steady demand recovery and product substitution dynamics after the pandemic shock. Looking to 2032, our base-case scenario projects attainment of ~USD 204 million — consistent with a 4.32% CAGR from 2026 onward. For 2026 planners, the practical takeaway is that growth is positive and predictable at the aggregate level, but competitive advantage will come from capturing disproportionate share within specific applications and grades.
Potassium Acetate Market
Market dynamics that will shape 2026 decisions
- Raw material cost volatility: Acetic acid is the principal upstream feedstock for potassium acetate. In 2025 acetic acid prices fluctuated between approximately USD 1,100 and USD 1,800 per tonne — a range that materially compresses or expands producer margins depending on contract structure, forward hedging, and integration.
- Regulatory momentum: PFAS bans in Europe are driving procurement teams on runways, bridges, and public agencies to specify acetate‑based de-icers that meet environmental compliance. Similarly, PFAS‑free claims are a differentiator for suppliers addressing U.S. and EU public tenders.
- Quality and certification premium: Food-grade and pharmaceutical-grade potassium acetate carry outsized margin potential but require investments in certifications, traceability, and vertical controls — an important trade-off for 2026 capex planning.
- Channel and formulation complexity: Liquid concentrates, crystalline anhydrous products, and formulated blends each follow different logistics, shelf-life, and distribution economics. Choosing which format to prioritize is a strategic manufacturing and commercial decision.
Competitive landscape — where advantage is made
The competitive map combines global diversified chemical majors, regional specialty producers, and distributors that leverage tolling or contract supply. Key participants illustrate distinct strategic archetypes:
Potassium Acetate Market
- Integrated specialty producers (e.g., BASF, Evonik): These global players offer scale, formulation know-how, and global distribution footprints. Their strengths are upstream integration, regulatory compliance capabilities, and the ability to bundle acetate salts into broader chemical portfolios.
- Premium crystalline and pharma-focused firms (e.g., Dr. Paul Lohmann, Kanto Chemical): These companies target high-value, moisture‑sensitive, or reagent-grade niches where product stability and analytical specs command price premiums and long-term contracts.
- Food-grade specialists (e.g., Niacet, select domestic manufacturers): Vertically integrated food-grade producers benefit from certifications and customer trust in supply continuity for food processing and preservation applications — a defensible position if traceability and audits are required.
- Regional manufacturers and exporters (e.g., Chinese and Indian producers): Firms in Asia offer competitive cost structures and multiple product grades, making them natural partners for volume-driven industrial and feed markets; however, they face increasingly stringent buyer expectations on quality and compliance.
- Distributors and toll processors (e.g., Altiras Chemicals, Chemaris): These players enable flexible, bulk supply for industrial users and can rapidly scale logistics for seasonal needs such as de-icing. Their advantage is responsiveness rather than upstream margin capture.
For 2026 strategic planning, assess whether to compete on price and volume, on premium certified grades, or on formulation and service. The market’s moderate concentration (with the top three to five suppliers holding a meaningful share) means that well‑timed capacity additions or strategic partnerships can move the competitive needle regionally.
Report contents — what PW Consulting delivers
Our full study is designed as an operator’s toolkit for 2026 strategy. It combines quantitative rigor with prescriptive, executable guidance:
- Top‑line sizing and scenario-based forecasts (base/low/high) from 2026–2032, with sensitivity to raw-material cost paths and regulatory adoption curves.
- Price and margin modelling that links acetic acid price scenarios to plant-level economics under different integration and contract structures.
- Compliance and sustainability playbook aligning PFAS policy timelines with procurement and product re‑specification strategies.
- End‑use demand maps and buyer profiles for pharmaceuticals, food & beverage, de‑icing, oilfield, and industrial segments — including benchmark purchase contracts and delivery models.
- Supply‑chain risk assessment with mitigation tactics: dual sourcing, tolling arrangements, buffer inventory strategies, and logistics playbooks for liquids vs. solids.
- Competitive landscaping and capability benchmarking of the key players, with acquisition targets, JV candidates, and licensing opportunities prioritized for different corporate strategies.
- Commercial playbooks: pricing strategies, sample contract clauses for long-term offtake, and a tactical guide for certification roadmaps (e.g., food/pharma standards).
2026 playbook — recommended moves by strategic posture
- For manufacturers seeking growth: Prioritize food‑ and pharma‑grade capacity where certification barriers create pricing leverage. Use 2026 to invest in traceability systems and targeted certifications and negotiate long‑dated acetic acid contracts or consider partial vertical integration to stabilize margins.
- For distributors and tollers: Build logistics and blending capabilities for seasonal de‑icing demand. Establish service guarantees and emergency response offers for public-sector tenders transitioning away from PFAS solutions.
- For buyers and formulators: Lock-in supply through multi-year contracts with indexed pass-through on acetic acid spikes. Consider qualification of multiple sources across geographies to reduce risk and leverage spot-market opportunities.
- For investors/M&A teams: Screen targets that combine certification assets, regional market access, and predictable cash flows from long-term public or pharma contracts. Smaller, regionally dominant players can be attractive bolt-ons to accelerate entry without bearing full greenfield capex risks.
Scenarios to monitor in 2026
- Accelerated substitution: Faster-than-expected PFAS regulation adoption in additional jurisdictions — compressed timelines favor suppliers with certified, ready-to-deploy de‑icing solutions.
- Raw-material shock: A sustained upward shift in acetic acid beyond the 2025 observed range would pressure unhedged producers and favour vertically integrated players.
- Premiumization in pharma/food: If buyers tighten supplier qualification, there will be a structural re‑rating of certified producers and increased attrition among low-cost, non-certified suppliers.
Final note — why the full report is critical for 2026 action
The market’s aggregate growth and steady CAGR conceal structurally different profit pools across grades, geographies, and applications. Executives who rely only on headline growth risk misallocating capital between low-margin commodity channels and higher-margin certified niches. PW Consulting’s full report provides the missing granularity: demand elasticities by application, panel-tested procurement clauses, supplier scorecards, and transaction comparables — all the operational detail that translates the macro figures above into a defensible 2026 plan.
To preserve commercial exclusivity of the most actionable segment-level insights, we have intentionally withheld detailed split tables in this preview. For clients and decision-makers ready to convert the market’s steady growth into competitive advantage, the complete study contains the precise datasets, contract language, and supplier comparisons required to execute in 2026. Contact PW Consulting to access the full Potassium Acetate Market report and the supporting data pack.
For detailed analysis of this topic, please visit the official page: Potassium Acetate Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com