

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Rehabilitation Robotics Market to Grow at 15.4% CAGR Through 2032

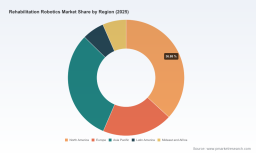
Rehabilitation Robotics Market 2026: Strategic Preview for Decision-makers
Executive snapshot
The rehabilitation robotics market has moved from an experimental niche to a commercially meaningful category. Our PW Consulting analysis (base year 2025; historical coverage 2020–2025; forecast 2026–2032) shows sustained, above-market expansion driven by clinical validation, reimbursement momentum and device-platform convergence. The global market reached approximately USD 172.8 Million in 2025 and, under our baseline scenario, is set to grow at a 15.4% CAGR through the 2026–2032 forecast window — reaching an anticipated USD ~468 Million by 2032. This trajectory transforms rehabilitation robotics from a capital-intensive innovation play into a strategic growth area for health systems, device OEMs, and investors preparing 2026 budgets and business plans.
Rehabilitation Robotics Market
Why this matters for 2026 corporate decision-making
-
Timing capital allocation: With double-digit CAGR and accelerating commercial milestones, 2026 is a pivot year for deploying capital into productization, go-to-market channels and evidence-generation. Firms that underinvest risk ceding early commercial share to first movers; those that overextend without reimbursement clarity risk stranded inventory.
Rehabilitation Robotics Market -
Operational redesign: Quantifiable therapist labor savings (industry sources indicate up to 40% reduction in therapist time per session in certain use-cases) change the economics of care pathways. Health systems planning 2026 budgets need robust cost-impact models to decide between outright purchase, leasing, or service arrangements.
Rehabilitation Robotics Market -
Regulatory & reimbursement inflection points: 2024–2025 developments (including finalized Medicare pathways and recent device clearances and payer approvals) materially lower commercial risk for personal exoskeletons and clinical platforms. Organizations should align clinical trials, HTA dossiers and coding strategies now to capitalize in 2026.
-
M&A and partnerships: Market concentration metrics indicate a fragmented supplier landscape (CR3 ≈ 26.4%; CR5 ≈ 34.2%), which favors roll-up strategies, strategic partnerships with rehab networks, and selective bolt-ons for software and services that accelerate time-to-scale.
What PW Consulting’s full report delivers (practical, decision-grade content)
-
Market sizing & scenario models: Transparent TAM/SAM/SOM constructs that reconcile historical adoption (2020–2025) with five modeled commercialization pathways across 2026–2032. Models are delivered in editable spreadsheets so teams can run internal assumptions.
-
Payer & reimbursement playbook: Detailed mapping of current reimbursement codes, payer precedents, and a step-by-step blueprint for obtaining coverage and developing economic value propositions for both personal and clinical-use devices.
-
Clinical-evidence matrix: Comparative hierarchy of published clinical studies, ongoing trials and real-world evidence for key device classes. The matrix highlights evidence gaps that must be closed to secure broad-scale adoption in hospital, outpatient and home settings.
-
Commercial go-to-market incubator: Channel economics, pricing templates, leasing and subscription structures, and sample RFP language tailored to hospitals, rehabilitation centers and large home-care networks.
-
Operational playbooks for health systems: Workflow redesign guides showing how robotics can be integrated into inpatient and outpatient therapy schedules, staffing models that capture projected therapist-time savings, and pilot metrics for clinical and financial success.
-
Vendor diligence & M&A screening: Scored profiles for incumbent and emerging suppliers (technology readiness, clinical footprint, regulatory status, IP posture, and service capability), plus an M&A shortlist and valuation sensitivity templates.
-
Risk register & mitigation strategies: Regulatory, reimbursement, clinical, and supply-chain risks quantified with mitigation playbooks and contingency triggers for executives building 2026 roadmaps.
Competitive landscape — who to watch and why
The competitive field combines legacy robotics firms, niche orthotics specialists, and agile platform companies. Players have distinct strategic postures — some double down on exoskeleton hardware and clinical services; others bundle hardware with software platforms and remote-monitoring services. Key companies in our coverage include:
-
Lifeward Ltd. (ReWalk): A leader in personal exoskeletons focused on gait restoration. Recent regulatory and commercial momentum — including a 510(k) clearance and U.S. product launches — has materially increased the addressable patient population for personal devices.
-
Ekso Bionics: With offerings spanning inpatient to personal exoskeletons, Ekso’s platform strategy and recent Medicare coverage for a personal model alter payor economics and competitive dynamics for home-use devices.
-
Cyberdyne: Strong clinician adoption in licensed medical facilities for their HAL lower-limb exoskeleton positions them well in facility-based gait training markets, especially in regions with consolidated rehabilitation centers.
-
Fourier Intelligence: An integrated approach (exoskeletons, upper-limb systems and RehabHub software) exemplifies the platform play — hardware + software + data — that many operators will seek to scale efficient care pathways.
-
myomo, Rex Bionics, DIH/Hocoma, Bionik, BioXtreme, AlterG and Tyromotion: Each brings targeted IP and clinical strengths across orthoses, treadmill-assist systems, upper-limb robotics and gait trainers; these firms are logical partners or acquisition candidates for larger device OEMs or clinical networks.
Our profiles include management track-records, recent product milestones, regulatory status, commercial references and a proprietary competitive scoring model that predicts near-term commercial traction. (Note: one company entry appears duplicated in public listings; our diligence reconciles such anomalies.)
Dynamics shaping adoption in 2026
-
Reimbursement architecture: CMS actions in 2024 and subsequent private-payer precedents in 2025 substantially lower the payer barrier for personal exoskeletons. Firms must align coding, claims workflows and value dossiers to capture accelerated uptake.
-
Regulatory momentum: Recent device clearances (notably for leading personal exoskeletons and inpatient systems) reduce market-entry friction. But variations in regional regulatory regimes still require tailored submission strategies.
-
Clinical economics: Demonstrable therapist time savings and throughput benefits create a compelling total-cost-of-care narrative. Contracting teams should be prepared to present cost-offsets over multi-year horizons.
-
Service & software differentiation: As hardware commoditizes, recurring revenue through software platforms, remote monitoring and outcome reporting will be a primary battleground.
Strategic options for different stakeholders (how to use the intelligence)
-
Hospital systems and rehabilitation networks: Run a rapid pilot using our pilot-template to validate ROI metrics locally; use the reimbursement playbook to ensure neutral-to-positive margin within 24 months.
-
Device manufacturers: Prioritize evidence-generation and payer engagement now; consider partnerships to fill gaps in services and software that accelerate adoption in 2026.
-
Private equity & corporate development: The fragmented supplier landscape and differentiated IP profiles suggest attractive roll-up opportunities. Use our M&A screens to prioritize targets with immediate route-to-revenue synergies.
-
Payers: Incorporate robotics into value-based bundles for certain neurologic and orthopedic pathways; our models quantify break-even and upside for multiple reimbursement structures.
Risks & open questions we track
-
Evidence gaps: While many studies show promising improvements in functional outcomes, heterogeneity in trial designs means payers will demand standardized endpoints. Organizations should commit to pragmatic trials and registry participation.
-
Capital intensity & utilization: Device economics are visit- and utilization-sensitive. Low utilization rates can negate expected savings; operators must optimize scheduling and cross-train staff to sustain ROI.
-
Regulatory unpredictability in certain markets: Not all regions will pace with U.S. payer developments; international commercialization plans must factor varied approval and adoption timelines.
How PW Consulting’s industry-grade deliverables accelerate your 2026 plan
Our report does more than present numbers. It equips teams to act: editable financial models, procurement templates, clinical evidence roadmaps and a prioritized partner/M&A shortlist. For executives building 2026 strategies, this combination of market foresight and operational toolkits shortens the path from pilot to scale.
Next steps
This preview is designed to surface the strategic implications and practical levers you need to address in 2026. For full, granular segmentation, regional adoption curves, application-specific economics and the complete competitive scoring matrices — including downloadable models and templates — please access PW Consulting’s full Rehabilitation Robotics Market report. Our team is also available to brief leadership groups and run custom workshops to translate the findings into executable plans for next fiscal-year cycles.
For detailed analysis of this topic, please visit the official page: Rehabilitation Robotics Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com